


Philip Morris International (PM) Lifts Its Dividend, Is The Stock Fully Valued?
Philip Morris International (PM) recently lifted its dividend by nearly 9%, a move that puts the tobacco group’s income profile in focus as it accelerates its shift toward smoke-free products.
Philip Morris International’s latest dividend increase comes after a strong run for investors, with the share price delivering a 24.7% year to date return and a 1 year total shareholder return of 32.69% at a closing price of US$199.90.
Scan income-focused opportunities with resilient cash flows by comparing Philip Morris International to our hand picked 8 dividend fortresses.
After a near 9% dividend lift and a strong share price run, Philip Morris International now trades only a little below the average analyst target. Is that gap pointing to upside or to stretched expectations?
Most Popular Narrative: 4% Undervalued
At a last close of $199.90 against a widely followed fair value of about $208, the current Philip Morris International share price lines up closely with that narrative, leaving only a modest valuation gap tied to its smoke free transition and earnings mix.
The accelerating global adoption of smoke free alternatives, driven by increasing health awareness and regulatory moves away from combustibles, is still supporting strong growth in IQOS, ZYN, and VEEV. Smoke free products are now delivering double digit revenue and gross profit expansion at around a 70% gross margin, which can continue to support higher net revenue and operating margin mix over time.
See why 96 investors see Philip Morris International as 4% undervalued.
Result: Fair Value of $208 (UNDERVALUED)
Still, the Philip Morris International story can change quickly if higher U.S. marketing spend on ZYN and IQOS ILUMA caps margin progress or if cigarette volume declines accelerate.
Find out about the key risks to this Philip Morris International narrative.
Another View: Philip Morris International Looks Expensive On Earnings
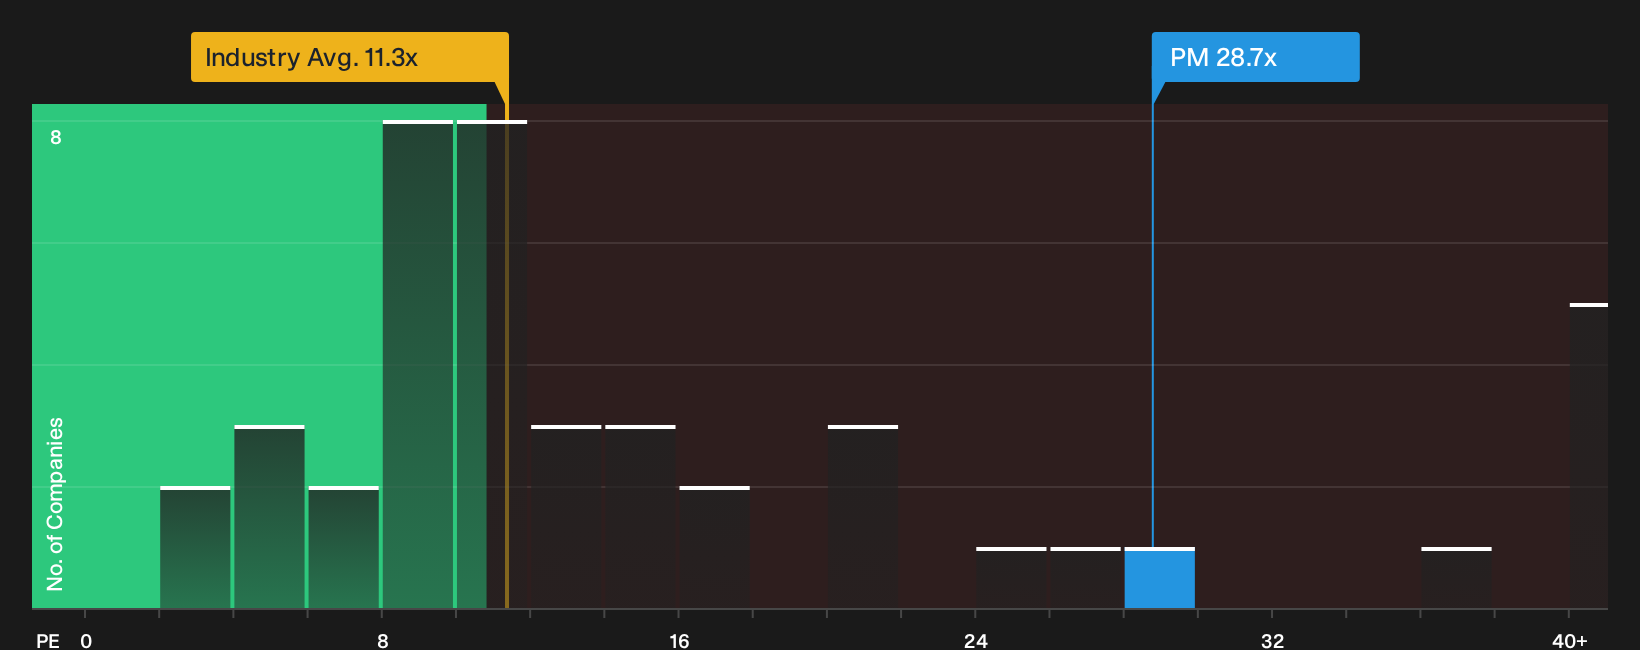
Philip Morris International screens as fully loaded on earnings. The current P/E of 28.7x sits above both peers at 21.6x and the global tobacco average of 11.3x, and also above a fair ratio of 25.8x that the market could eventually lean toward, which would mean less room for error if sentiment cools.
That kind of premium can work while the smoke free story holds together, but it leaves investors asking whether this is justified by future execution or whether a closer look at the numbers suggests the market is paying up for comfort rather than clear value. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There is a mix of optimism and caution around Philip Morris International right now. Move quickly to study the numbers and form your own stance with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Philip Morris International?
If you only stop at Philip Morris International, you risk missing other opportunities that might suit your goals even better, so broaden your watchlist intelligently today.
- Target powerful income opportunities by scanning high-yield stocks in the 8 dividend fortresses that combine substantial payouts with disciplined financial profiles.
- Hunt for mispriced potential by checking the 20 high quality undiscovered gems where fundamentals and market attention are still out of sync.
- Prioritise resilience by focusing on companies in the list of solid balance sheet and fundamentals (25 results) that pair sturdy finances with the capacity to reinvest through different cycles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com