


Where Does Fulton Financial (FULT) Value Sit After A 102% Run?
Fulton Financial has delivered a strong share price run in recent years, which naturally raises the question of whether today's valuation still lines up with the earnings power of the regional bank. With the market already rewarding the stock, the key issue for you is how much of its profit profile is already reflected in the current price.
- Over the past 3 years the stock has returned 102.5%, which puts real weight on whether current earnings fully support that step up in market value.
- The business leans on interest income and fee-based banking services, so any shift in loan growth, credit quality or funding costs can reshape the sustainability of its profits and the multiple investors are willing to pay.
- Your read on Fulton Financial is one view; the desks covering it have another. See what analysts think Fulton Financial's shares could be worth.
The stock's next move may depend on whether Fulton Financial's recent share price level is justified by the earnings it is generating today and is expected to produce over time.
If you want a broader starting point while you assess Fulton Financial's earnings support for its recent 102.5% three year return, apply the same approach to 33 high quality undervalued stocks.
Where Does Fulton Financial Sit on Earnings?
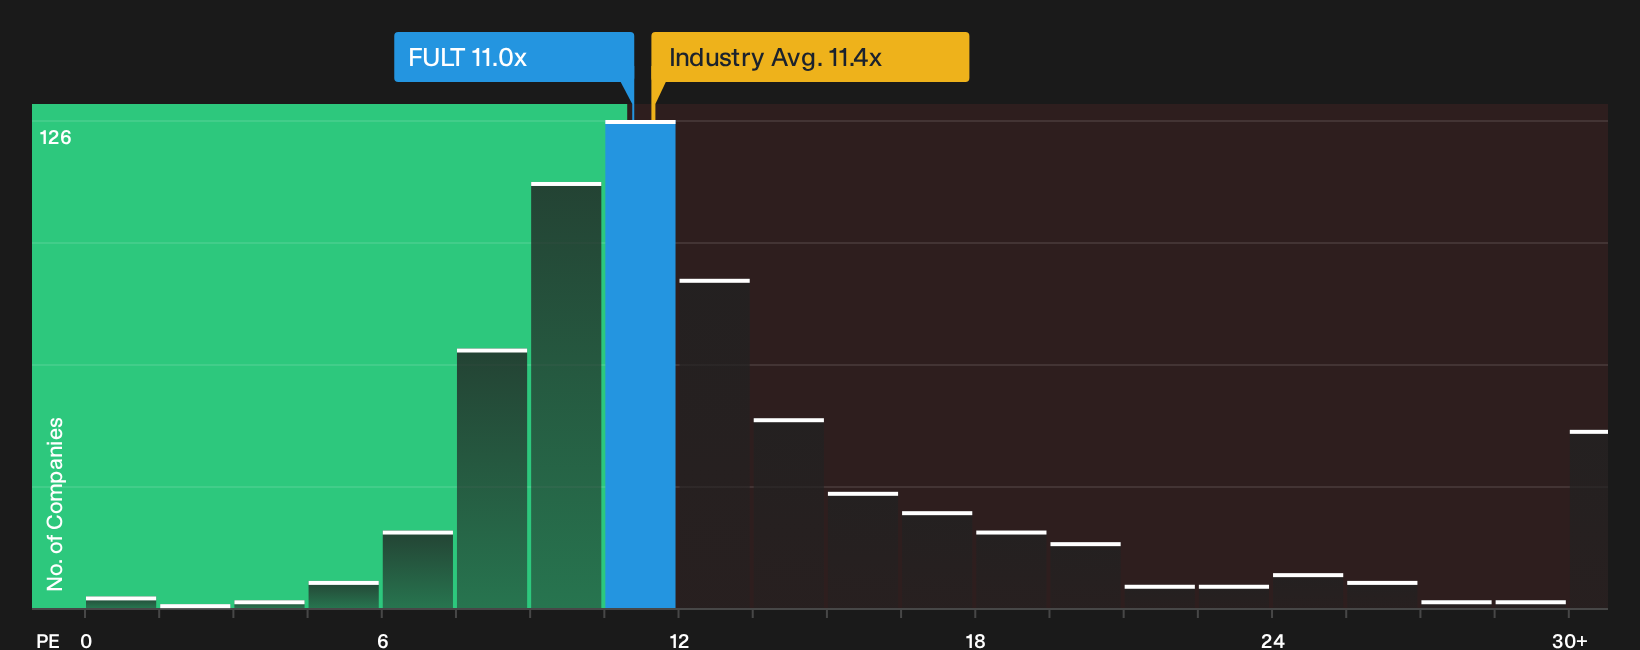
The P/E ratio suits Fulton Financial because earnings remain a primary anchor for how investors look at regional banks. The stock trades on a P/E of 11.0x, which sits close to the Banks sector average of 11.4x and well below a wider peer group around 24.4x. That mix suggests the market is pricing Fulton Financial more like a typical regional lender than a higher rated peer, at least on headline earnings.
A fair P/E for Fulton Financial, based on its own return on equity profile and analyst expectations, sits close to where the shares trade today, so the current 11.0x multiple appears broadly in line on this framework. For a decision, investors still need to weigh how reliable those earnings look across a full credit cycle, how funding costs shape net interest income, and whether fee income can support profitability if loan growth softens. Explore the numbers behind Fulton Financial's P/E valuation.
The Fulton Financial Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Fulton Financial's valuation puzzle leaves off and spell out which assumptions on growth, margins and earnings would need to hold for the share price to sit meaningfully higher or lower than it does today. These scenarios can be compared against future results as they are reported.
Each narrative sets out the key building blocks behind its view of Fulton Financial's worth in plain terms rather than collapsing everything into a single P/E or model output. This way, you can track how those inputs line up with actual performance over time.
One of the top community narratives on Fulton Financial: 15% undervalued
"Fulton Financial is progressing its acquisition led expansion in Philadelphia and Northern New Jersey, where the Blue Foundry deal has already added about US$1.6b of loans..."
Discover why this Narrative puts Fulton Financial at 15% undervalued.
One more Fulton Financial check that sits beside the P/E
Price multiples give you a snapshot of Fulton Financial today, but the analyst road map for the next few years offers a different lens on where earnings expectations currently sit. Explore where analysts expect Fulton Financial to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com