


TomTom (ENXTAM:TOM2) Q3 Results Contrast Profitability With Automotive Revenue Declines
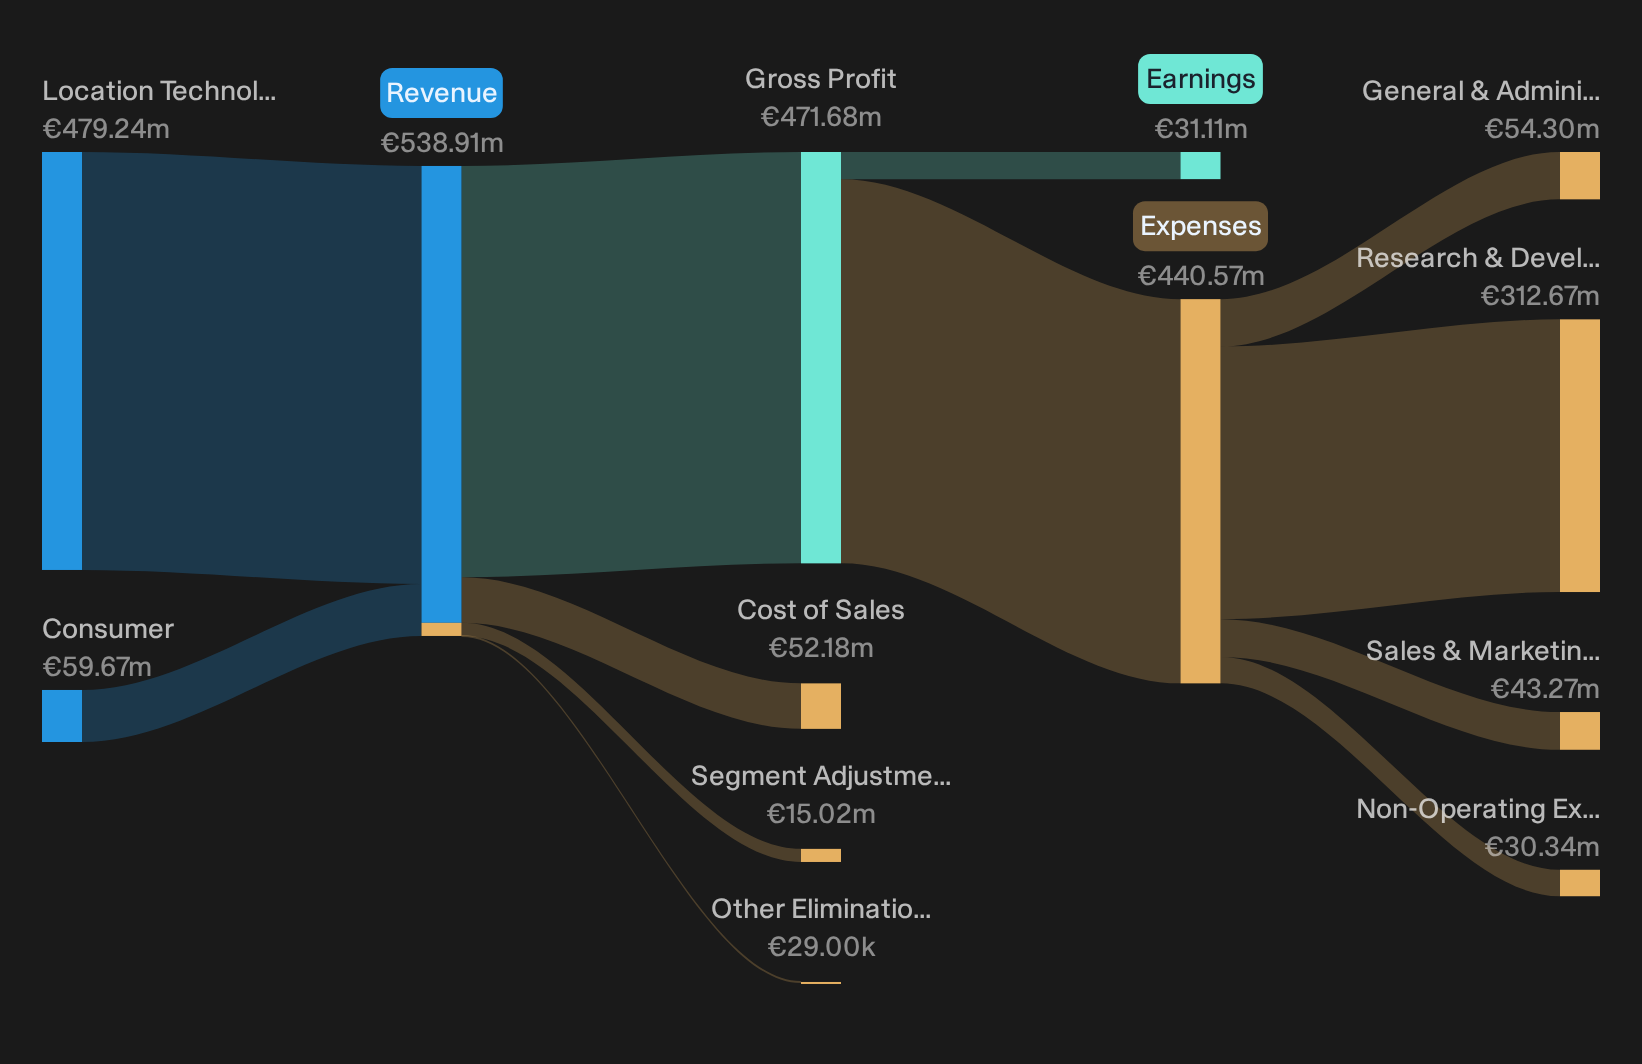
TomTom stock closed at €3.80 on Friday, a level that still reflects a cautious mood after a choppy few months, yet the fresh Q3 2026 numbers tell a more nuanced story. The headline is simple: revenue came in at €128.93m and net income reached €5.121m, keeping the business profitable while the restructuring machine is already in motion.
In the very short term, those figures may not move the needle much. Over a multi year view, restored earnings power, a P/E of 15.2x and a sizeable net cash position of €239m frame a very different debate about what this stock is actually worth.
Love TomTom's return to profitability but wondering where you might find a similar earnings profile backed by even stronger balance sheets and fundamentals? You can compare it against our curated list in the list of solid balance sheet and fundamentals stocks (203 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €128.93m vs. €136.88m (declined 5.8%)
- Net Income (Q3 2026 vs Q3 2025): €5.121m vs. €9.098m (declined 43.7%)
- Basic EPS (Q3 2026 vs Q3 2025): €0.04 vs. €0.07 (declined 42.9%)
- Trailing 12M Net Income (to Q3 2026 vs to Q3 2025): €31.109m vs. a loss of €30.723m (moved from loss to profit)
Ask Charlie what TomTom’s Microsoft deal could mean for growth.
Evaluating TomTom’s Transit Partnership And Buyback Claims
Supporters argue that TomTom’s recent moves in transit and capital returns can reshape the equity story.
"TOM2: Transit Partnership And Buyback Program Will Drive Future Upside Potential"
The earnings and news flow give this a mixed scorecard. The Transit Technologies deal is now live, with Orbis Maps and Live Traffic embedded in US and Central American fleet platforms, so the commercial milestone exists rather than being theoretical. The share buyback is also concrete, with 2,942,342 shares repurchased for €15.01m and net cash still at €239m. At the same time, Q3 revenue of €128.93m and Automotive operational revenue down 19% year on year show that meaningful top line acceleration is not yet visible.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
TomTom Bear Case: Contract Gaps Still Biting
The cautious view hangs on the idea that expiring automotive deals create revenue holes before fresh programs and partnerships can fill them.
"the gradual discontinuation of existing automotive programs and a wide 2026 revenue range suggest that new contracts may not fully offset near term gaps, which can restrain revenue growth and delay earnings momentum."
Q3 results lean toward that concern. Automotive revenue of €78m sits against Automotive operational revenue, which is down 19% year on year as phase outs drag. Group revenue of €129m is 6% lower, and Enterprise slipped 4%, so contract churn is still flowing through despite Transit Technologies and other new deals.
Hunt Quiet Fundamental Shifts
TomTom’s latest quarter shows how headline revenue and restructuring can shape a complex equity story. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 21% below our estimate - expands low carbon and recycled metal supply agreements under tighter climate policies for manufacturers.
- Company 2 - 17% below our estimate - advances a copper development aiming to increase production while lowering the cost base.
- Company 3 - 23% below our estimate - transitions from conventional shipbuilding toward underwater technology and digital systems integration for defense.
Three companies from the same screener. Open every one of the 193 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com