


Broker Upgrade Could Reframe The Case For ArcelorMittal Stock (ENXTAM:MT)
- ArcelorMittal was upgraded by J.P. Morgan to overweight after a period of share price weakness, with the broker highlighting expectations for stronger EBITDA in 2027 and 2028 supported by operations in North America, Europe and Brazil.
- The interesting angle is less the rating change itself and more J.P. Morgan’s focus on ArcelorMittal’s underlying earnings power across key steel regions, pointing investors back to fundamentals such as regional demand mix and cost efficiency.
- Next, the focus shifts to how ArcelorMittal’s investment narrative might be influenced by this renewed emphasis on future EBITDA strength.
What Is ArcelorMittal's Investment Narrative?
To own ArcelorMittal, you need to buy into a global steel producer that lives and dies by execution across several heavy industrial cycles. The group runs integrated steel and mining operations across North America, Europe and Brazil, supplying construction, automotive and machinery customers, and tying profitability closely to demand and pricing in those end markets. Cash intensive plants and mining assets require steady discipline on maintenance, cost control and capital spend. J.P. Morgan’s fresh focus on EBITDA potential mostly reinforces that story rather than changing it, since it leans on the same regional mix and operational footprint already in place.
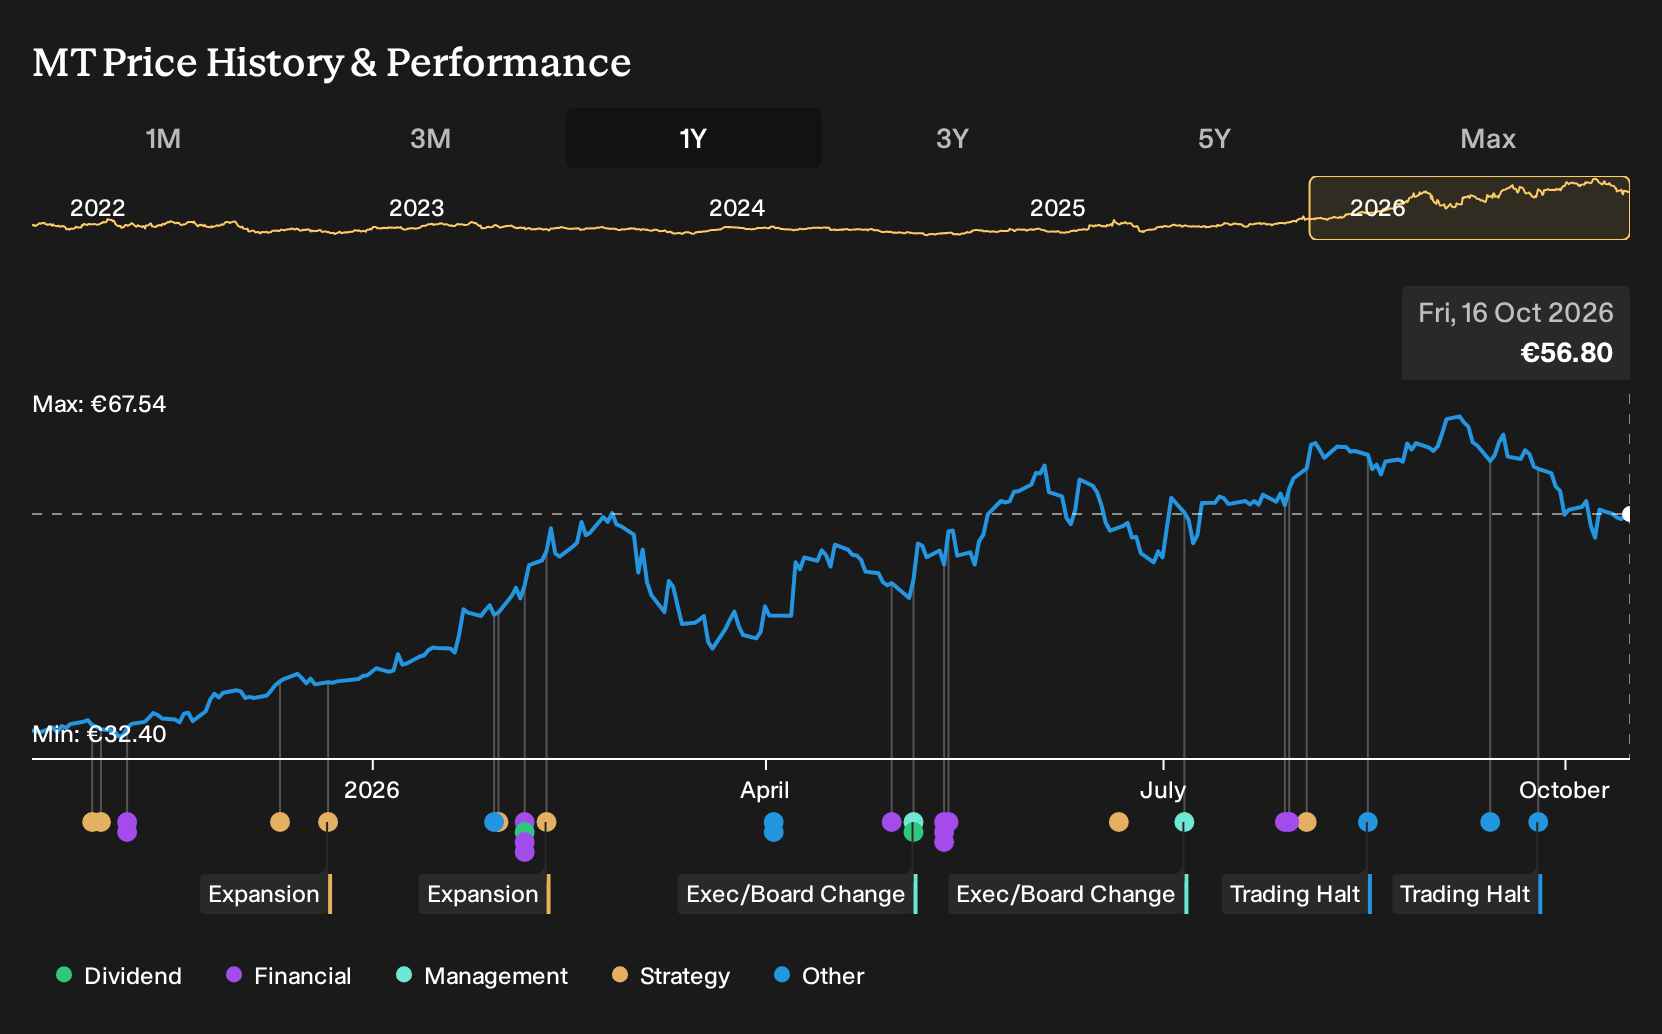
In the short term, the upgrade comes after a share price that is down roughly 12% over the past month, which may influence sentiment more than fundamentals. The bigger swing factors still look operational. Steel pricing, volume trends in Europe and the Americas, and ArcelorMittal’s ability to translate forecast earnings growth of about 31% per year into actual cash flow matter more than any rating label. At the same time, the stock trades on a P/E of 26.6x and is viewed as good value against some reference points, yet expensive versus the European metals and mining peer average of 14.3x. This keeps the valuation debate active if execution stutters.
Even so, one tension inside the ArcelorMittal story does not fully show up in the headline earnings forecasts and comes from ...
There's only one way to know the right time to buy, sell or hold ArcelorMittal. Head to Simply Wall St's company report for the latest analysis of ArcelorMittal's Fair Value.
Exploring Other Perspectives
For ArcelorMittal, the sharpest contrast comes from analysts who worry that heavy decarbonization and modernization spending could drag on returns. The most cautious forecasts were built on revenue growing about 4.2% a year and earnings reaching roughly US$5.3b by 2029. Those pre upgrade estimates show how far opinions can stretch; treat this J.P. Morgan call as a prompt to compare several narratives rather than accept one story.
Explore 2 other ArcelorMittal fair value estimates, including one that suggests it could be worth just €69.66!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ArcelorMittal research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ArcelorMittal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ArcelorMittal's overall financial health at a glance.
Looking For More Investment Ideas Beyond ArcelorMittal?
If the ArcelorMittal story has sharpened your thinking about earnings power, balance sheets and valuation, you can use that same lens on a wider set of companies using the Simply Wall St Screener.
- For investors who want potential mispricing combined with quality fundamentals, review 193 high quality undervalued stocks that might align better with your margin of safety goals.
- If steady income is a priority, scan 213 dividend fortresses that focus on higher yields and resilient payout histories.
- For those who prefer financial strength and fewer balance sheet surprises, filter for a 233 resilient stocks with low risk scores that could better match a more defensive approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com