


What Investors Got Wrong About Tata Elxsi Before The Drop
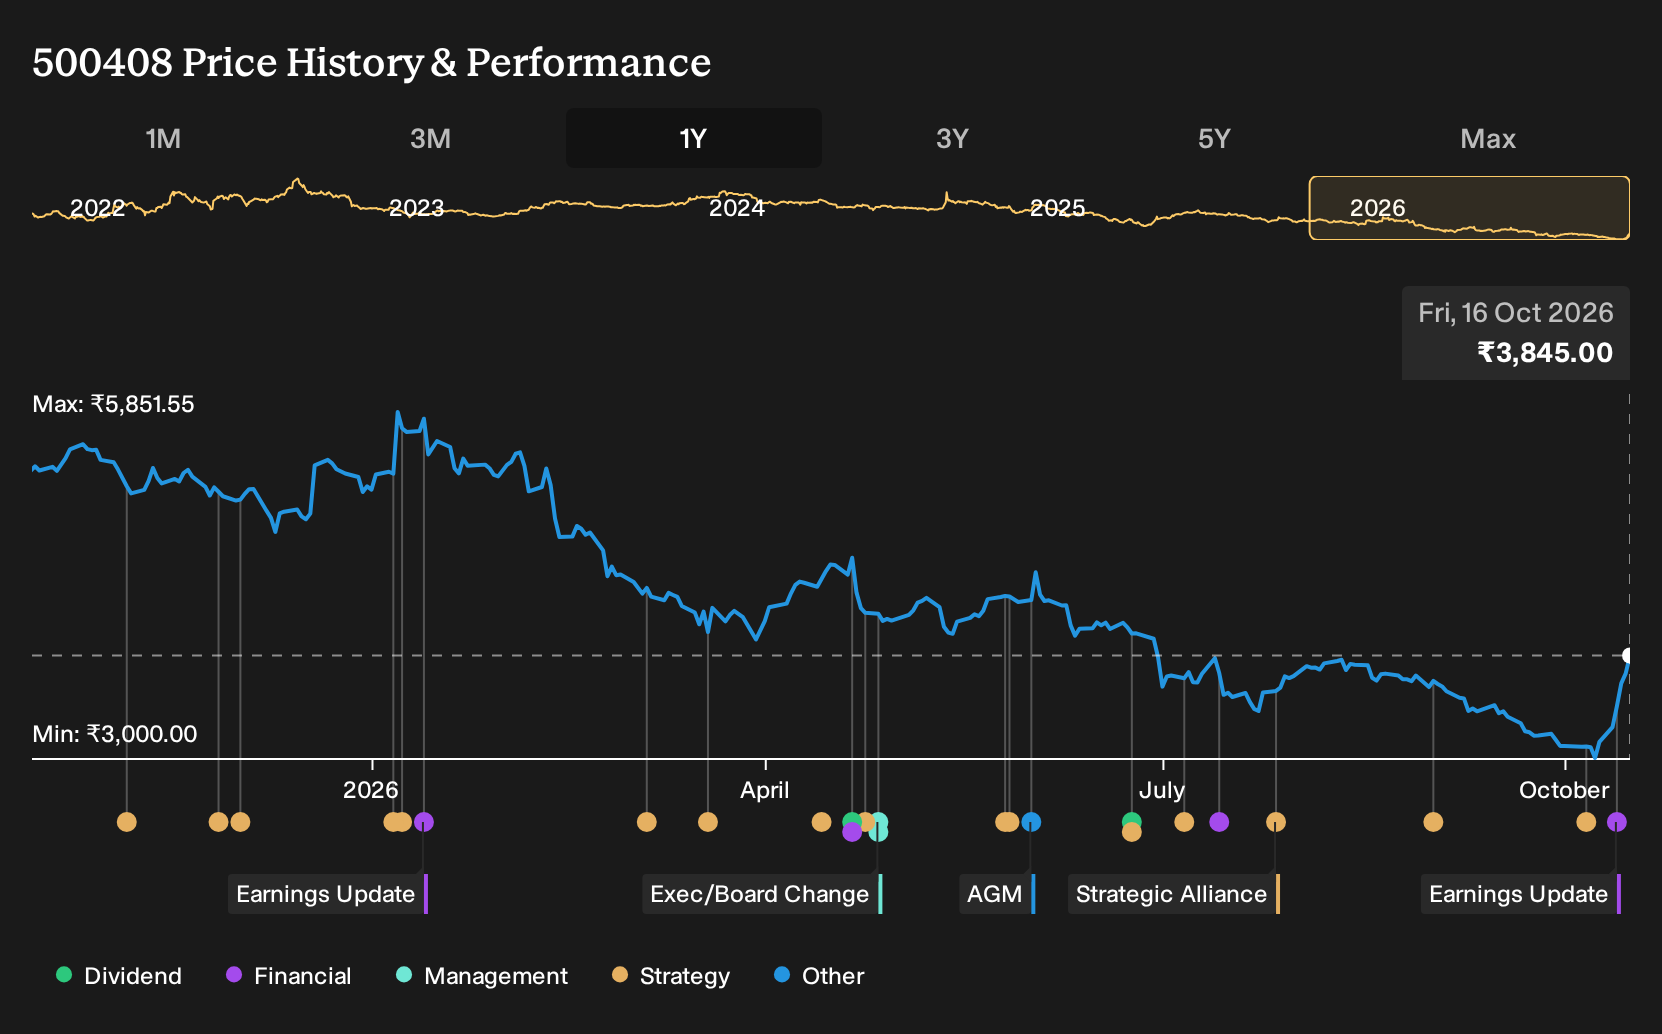
If you only looked at Tata Elxsi’s latest quarter, with higher revenue and profit but a slightly thinner net margin, the share price outcome might come as a surprise. Investors who held Tata Elxsi over the past year are down 27.1%, including dividends. If you were deciding on 16 October 2025 whether to commit fresh capital, which early clues would have mattered most before that drawdown showed up in your account?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Tata Elxsi has already moved. Pinpoint other ways to investigate the theme among 150 AI small caps.
The Two Tata Elxsi Stories Investors Had In Front Of Them
The shares cost ₹5,404 at the start of the period, and Tata Elxsi sat between two very different but reasonable stories about where the business could head next.
The bullish narrative put Fair Value at ₹5,782, based on the idea that EV and software defined vehicle programs, plus aerospace and defense work, would support 13.3% annual revenue growth and a higher 21.4% profit margin.
The more cautious view set Fair Value at ₹4,663, assuming 9.3% revenue growth and a 20.6% margin, and highlighting delays and tariff risks in key automotive projects as a central concern.
What The Results Changed For Tata Elxsi
The biggest fresh clue came from Q2 FY27. Tata Elxsi reported operating revenue of ₹10,556.6m, up from ₹9,181.0m a year earlier, and net income of ₹1,703.0m versus ₹1,548.2m. That outcome supported both the bullish and cautious stories on growth, but the slip in net margin from 16.9% to 16.1% leaned toward the more measured case on profitability.
The lesson is simple. When a thesis depends on rising profitability, you track the net margin line just as closely as revenue, then check whether each new quarter moves that percentage toward or away from the original assumption.
What You Would Be Paying For In Tata Elxsi Today
Tata Elxsi now trades at ₹3,845, after a fall of 27.1% over the past year. The selected Narrative sees Fair Value above that level, based on a belief that the business model can support stronger earnings than the price implies.
The core question for a buyer today is whether Tata Elxsi can translate AI platforms, software defined vehicle programs and consolidation deals into higher utilization and a margin recovery that turns the share price drop into opportunity rather than warning.
"Some analysts expect Tata Elxsi to compound the shift towards OEM and software defined vehicle work, AI platforms and consolidation deals into sustained earnings growth that is not yet reflected in the current share price. The main factor that has to go right is that Tata Elxsi converts its AI and platform led model, offshore centric delivery and large transition deals into higher utilization and a recovery in margins, while Healthcare and Life Sciences return to growth."
One Narrative disagrees with today's price. → See where this Narrative says Tata Elxsi should trade
Go Straight To The Source
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 50% below our estimate - tests whether a dominant payments and marketplace ecosystem can extend its moat into adjacent services.
- Company 2 - 34% below our estimate - rolls out shared technology platforms that cut costs while nudging clients toward premium offerings.
- Company 3 - 21% below our estimate - sells cloud based forensic tools agencies adopt as digital investigations displace legacy workflows.
Those are three of them. See every one of the 195 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com