


Glaukos Is Up 94%, But The Story Has Changed
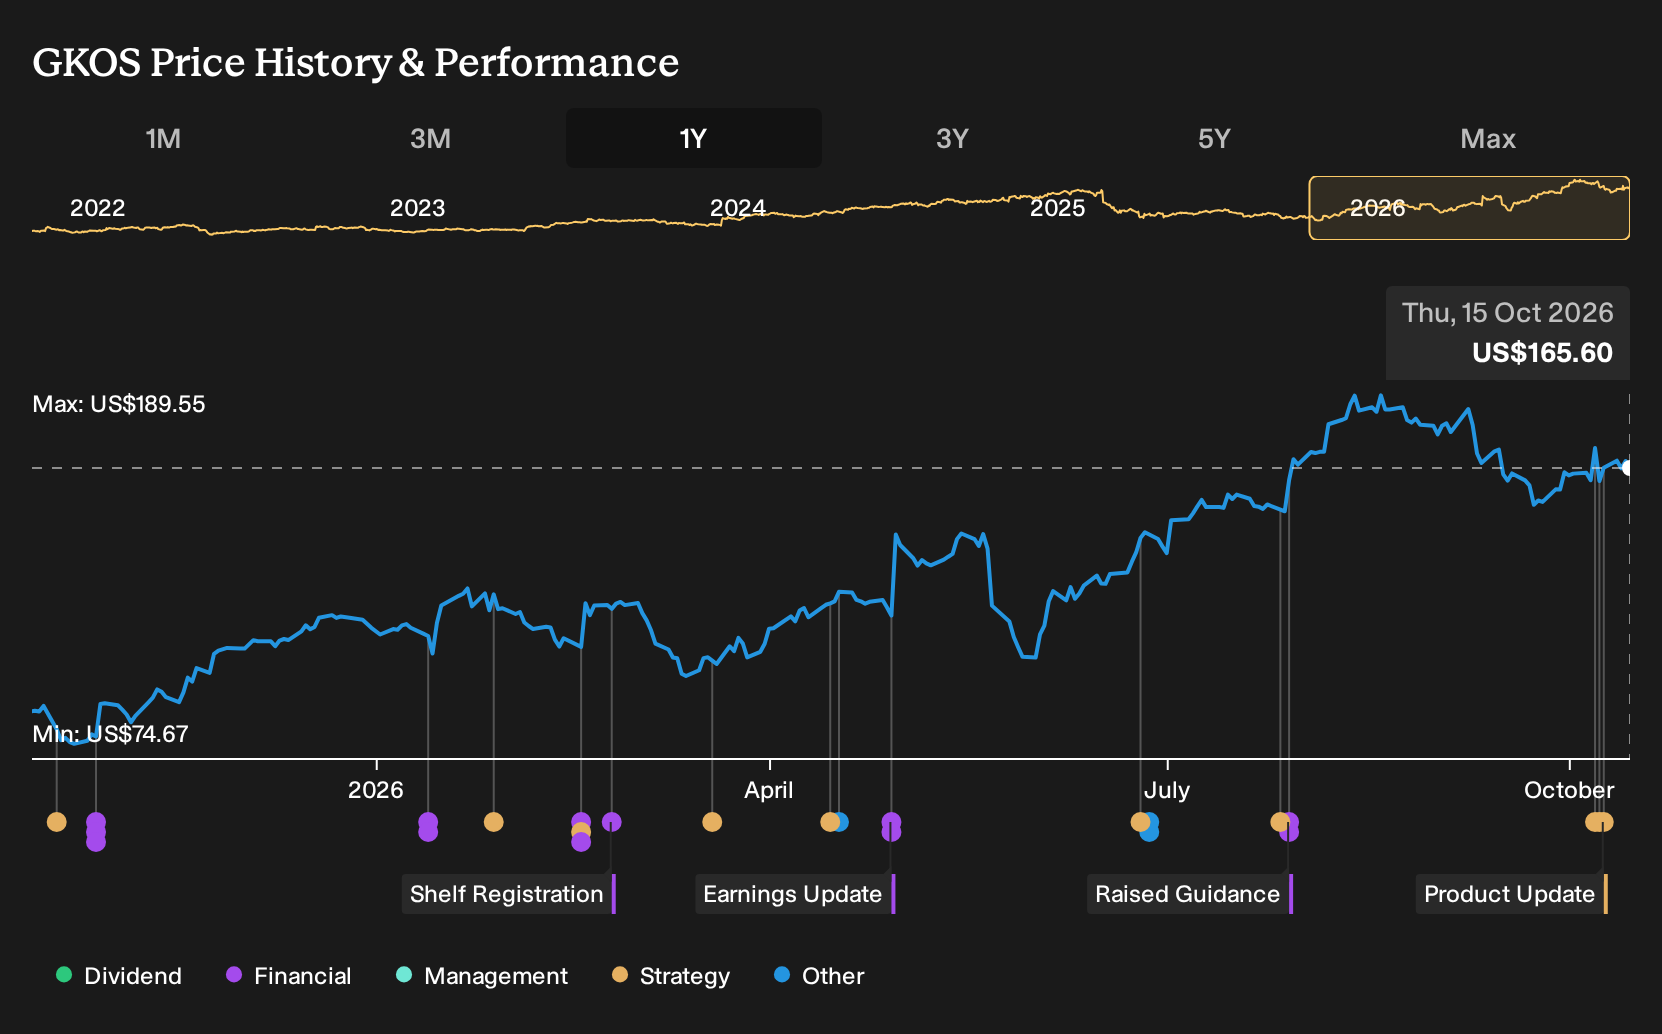
Glaukos spent the year posting record quarters, richer guidance ranges, and cleaner margins, yet the real surprise sat in shareholders’ brokerage accounts. Holding Glaukos over the past year would have returned 94.1%, including dividends. If you had bought on 15 October 2025, that gap between solid but still loss-making results and a near doubling of your capital raises a sharper question: What exactly were investors rewarding so aggressively?
Glaukos has already moved. Pinpoint other ways to investigate the theme among 34 healthcare AI stocks.
The Two Glaukos Stories Investors Had To Weigh
The shares cost US$85.6 at the start of the period, and every investor in Glaukos had to decide which future seemed more believable.
On the upbeat side, the bullish narrative pointed to a Fair Value of US$123, a theoretical price implied by its assumptions, built on strong uptake of iDose TR and a broadening pipeline across glaucoma, corneal disorders, and retinal disease therapies.
The more cautious case put Fair Value at US$74.28 and focused on risks such as reimbursement cuts, slower payer adoption, and heavier reliance on a narrow set of core products.
What The Evidence Did To The Glaukos Debate
Glaukos then reported Q2 2026 revenue of US$185.61 million versus US$124.12 million a year earlier. The loss narrowed from US$19.657 million to US$18.377 million and net margin improved from -15.8% to -9.9%. That combination of higher sales and less negative profitability supported the optimistic case, although continued losses left the profitability part of that story still unproven.
The lesson is clear. When you see a bullish pitch built on margin expansion, check whether net income and net margin are actually moving toward positive territory in reported numbers, not just whether sales for a company like Glaukos are rising.
What Glaukos Buyers Are Paying For After A 94% Run
With Glaukos now at US$166 after a 94.1% gain over the past year, this Narrative’s Fair Value sits above the current price, reflecting a more optimistic stance than the market is pricing in.
The argument leans on iDose TR, Epioxa and an early retinal biologics platform to support a higher earnings mix. A buyer today has to judge whether high gross margins and the expanding O2N treatment network can truly convert into sustained cash generation.
"A key factor is whether Glaukos can translate its expanding O2N treatment network, payer access and high gross margin profile into sustained, scalable cash generation in the face of reimbursement and competitive pressures."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 22% below our estimate - helps utilities and defense clients test, diagnose and modernize complex electrical infrastructure systems.
- Company 2 - 36% below our estimate - turns a swelling advisory pipeline and senior hires into higher-fee capital and restructuring mandates.
- Company 3 - 48% below our estimate - supplies specialized steel reinforcement products into infrastructure projects backed by federal highway funding.
Three companies from the same screener. Open the full list of 33 companies trading below our fair value estimates →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com