


How Investors May Respond To West (WST) Raised Guidance
- West Pharmaceutical Services recently presented at CPHI Milan 2026, where senior leaders highlighted the Synchrony S1 prefillable syringe launch and Dublin facility expansion as part of its broader commercial and manufacturing agenda.
- The company lifted full year revenue and earnings guidance after reporting strong demand for high value pharmaceutical packaging components and improved operating margins, underlining how execution on new products and added capacity is feeding into its outlook.
- We will now explore how West Pharmaceutical Services' upgraded full year guidance could influence the wider investment narrative around its high value components.
Scan how West Pharmaceutical Services’ momentum in high value components compares with other specialists in drug delivery and packaging by zeroing in on list of solid balance sheet and fundamentals (25 results)
West Pharmaceutical Services Investment Narrative Recap
To own West Pharmaceutical Services, you need to buy into a simple idea. High value components for injectables, especially in GLP 1 therapies, biologics and Annex 1 upgrades, remain the engine of the business. The raised full year guidance signals that current demand and execution in these areas are tracking ahead of what management previously laid out.
The key near term catalyst is whether that high value mix and operating margin progress can hold as contract manufacturing transitions away from CGM work and Dublin drug handling slowly ramps. The main risk is that this handover introduces lumpiness in West Vantage margins, while a premium P/E near 47x leaves little room for operational missteps.
The Synchrony S1 prefillable syringe launch is the announcement most tied to this recent update. It plugs directly into West Pharmaceutical Services high value components focus and into the trend of more complex injectable therapies that rely on tighter containment, inspection and finishing standards. Stronger guidance suggests early traction is feeding into both volumes and mix.
Your watchpoints now are practical. Synchrony S1 adoption relative to GLP 1 and biologics pipelines, how quickly additional customers qualify the platform, and whether this offsets any softness in lower value packaging. If uptake slows or buyers pivot to simpler formats, the margin mix story around high value syringes and seals could look less convincing.
West Pharmaceutical Services' current analyst narrative points to revenues of US$4.0b and earnings of US$814.5m by 2029, assuming revenue grows at 6.4% per year and earnings rise by about US$249.6m from US$564.9m today.
Uncover why West Pharmaceutical Services' fair value indicates a 6% potential upside to its current price before that discount closes.
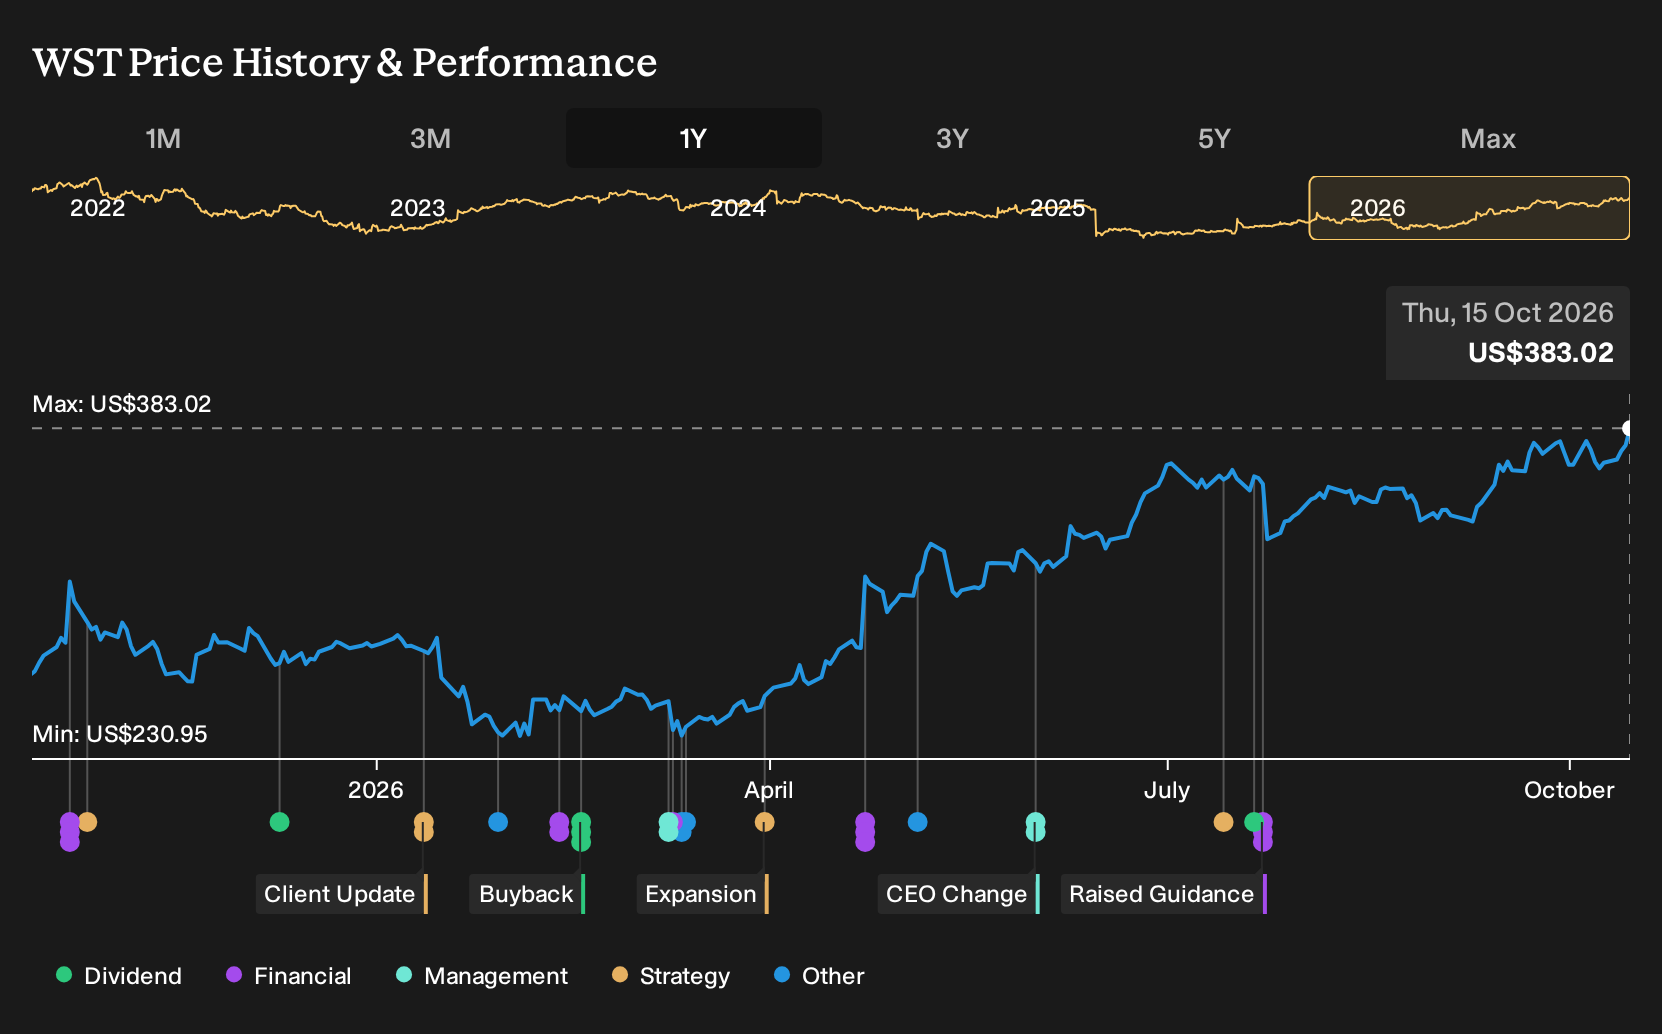
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$316 to US$405 per share, which already shows how far apart private investors can be on West Pharmaceutical Services. Set that against the premium P/E near 47x and the reliance on GLP 1, biologics and Annex 1 momentum, and you are looking at a story where opinions can diverge sharply. It can be useful to test your own view against these alternative takes.
Explore another West Pharmaceutical Services fair value estimate, including one that suggests as much as 18% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your West Pharmaceutical Services research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for West Pharmaceutical Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate West Pharmaceutical Services' overall financial health at a glance.
Looking for more investment ideas beyond West Pharmaceutical Services?
Once you have a handle on West Pharmaceutical Services, it can help to widen the lens and compare it with other listed businesses that share similar qualities or offer a different balance of risk and reward. The Simply Wall St Screener lets you do that quickly by filtering for the traits you care about most, from financial resilience to income potential.
- If capital preservation is high on your list, you can start with companies that pair solid finances with lower risk profiles by scanning 32 resilient stocks with low risk scores.
- If you are hunting for businesses that the market may be overlooking, you can broaden your research with 20 high quality undiscovered gems that already show strong underlying fundamentals.
- If you want a mix of quality and resilience in the balance sheet, you can compare West Pharmaceutical Services with a list of solid balance sheet and fundamentals (25 results) to see how it stacks up on debt, cash and core strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com