


Earnings Preview: What to Expect From Eversource Energy's Report
Springfield, Massachusetts-based Eversource Energy (ES) is a public utility holding company that delivers energy. Valued at $24.9 billion by market cap, the company provides electric service to customers in Connecticut, New Hampshire, and western Massachusetts. It also distributes natural gas throughout Connecticut. The utility giant is expected to announce its fiscal third-quarter earnings for 2026 in the near term.
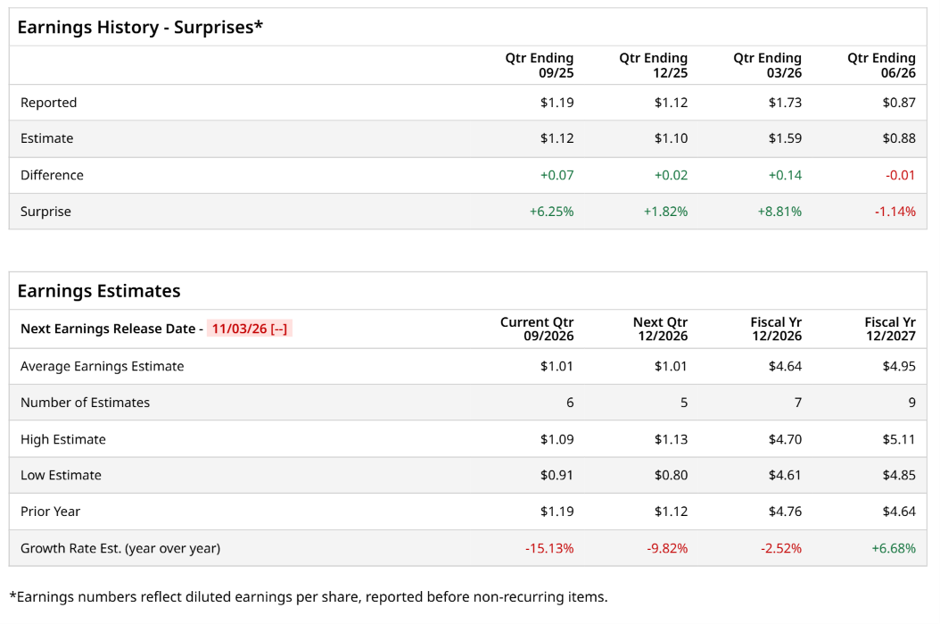
Ahead of the event, analysts expect Eversource Energy to report a profit of $1.01 per share on a diluted basis, down 15.1% from $1.19 per share in the year-ago quarter. The company beat the consensus estimates in three of the last four quarters while missing the forecast on another occasion.
For the full year, analysts expect Eversource Energy to report EPS of $4.64, down 2.5% from $4.76 in fiscal 2025. However, its EPS is expected to rise 6.7% year over year to $4.95 in fiscal 2027.
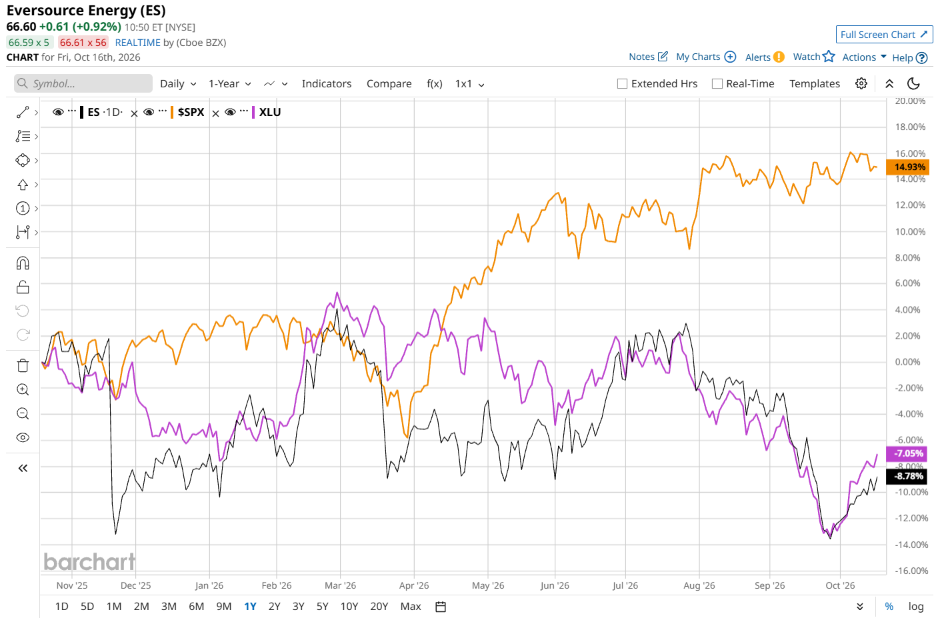
ES stock has underperformed the S&P 500 Index’s ($SPX) 16.1% gains over the past 52 weeks, with shares down 6.6% during this period. However, it outperformed the State Street Utilities Select Sector SPDR ETF’s (XLU) 8.3% losses over the same time frame.
ES’ underperformance over the past year has been driven by a combination of adverse regulatory decisions, heavy one-time charges, and investor concerns over balance sheet pressure. The company has faced headwinds from strict regulatory rulings, including lower transmission return on equity adjustments, alongside substantial financial hits from its costly exit from offshore wind investments and asset sales. Furthermore, massive capital expenditure requirements and plans for future equity issuances to protect credit metrics have sparked dilution worries, weighing on the stock despite steady underlying utility operations.
Analysts’ consensus opinion on ES stock is cautious, with a “Hold” rating overall. Out of 16 analysts covering the stock, four advise a “Strong Buy” rating, nine give a “Hold,” one recommends a “Moderate Sell,” and two advocate a “Strong Sell.” ES’ average analyst price target is $72.58, indicating a potential upside of 8.9% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.