


Learn Why The Bull Case For Brunello Cucinelli Stock Could Change Following Raised Revenue Forecast
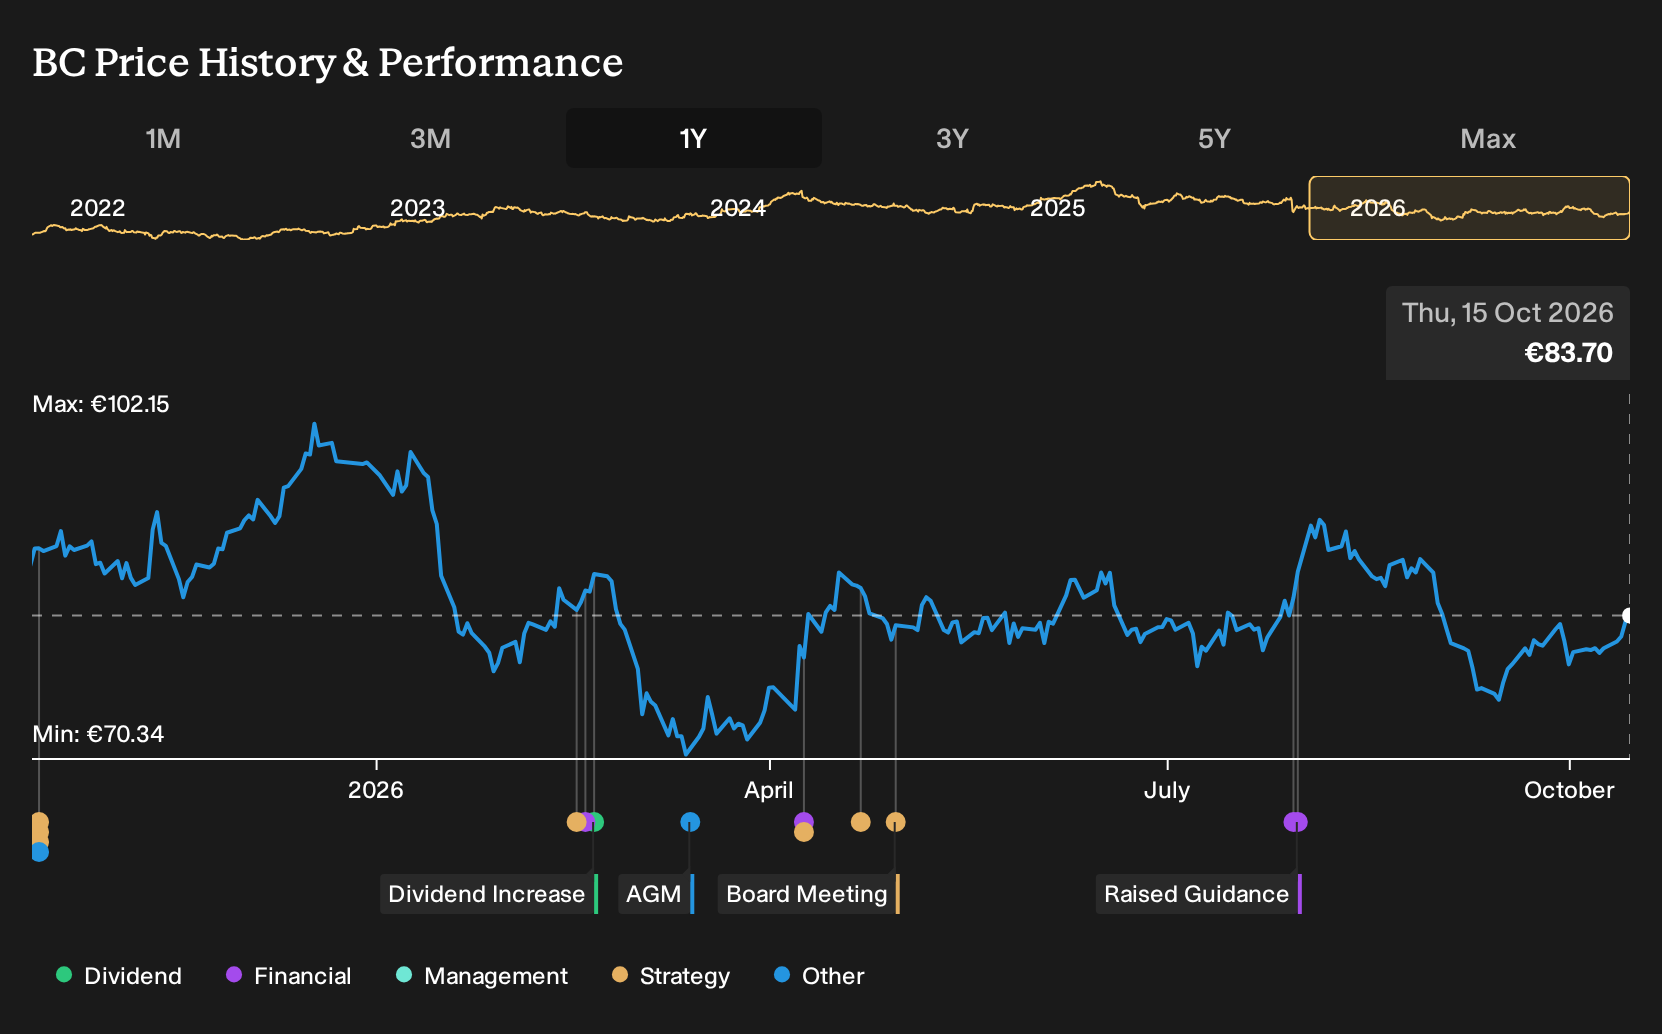
- Brunello Cucinelli recently reported a 10% gain in nine month sales and lifted its 2026 revenue outlook to 12% growth at constant exchange rates, citing broad based strength across North America, China, Europe, and online channels.
- The firm is pairing this higher guidance with continued boutique expansion in China and the United States and an early stage generational handover plan. This ties long term brand stewardship directly to ongoing investment in its retail footprint and artisanal model.
- Now the focus turns to how Brunello Cucinelli’s higher 2026 revenue growth forecast reshapes the existing investment narrative built around quiet luxury.
Brunello Cucinelli Investment Narrative Recap
To own Brunello Cucinelli, you need to believe its quiet luxury positioning, artisanal supply chain, and controlled retail buildout can keep demand healthy even as costs and debt sit higher. The key short term swing factor is whether recent momentum in North America, China, and online keeps offsetting rising personnel and rent expenses that have been running ahead of revenue.
The raised 2026 revenue growth outlook to 12% supports the idea that current investments in boutiques and production capacity still have room to pay off, so the news matters for confidence in execution. The biggest risk remains that luxury spending cools or growth slows while net financial debt and operating costs stay elevated, which could pressure margins quickly.
The clearest announcement tied to this update is management’s decision to lift 2026 revenue guidance from 10% to 11% up to 12% at constant exchange rates after nine month sales grew 10%. That guidance move sits directly on top of the existing catalyst around store expansion, particularly in China and the United States, together with the fully built out manufacturing base in Solomeo.
For you as a shareholder, the question is whether Brunello Cucinelli can keep using this larger footprint, combined with its authenticity and craftsmanship pitch, to support steady revenue and earnings growth despite higher debt and operating costs. If execution on new boutiques or demand from key regions weakens, the risk case around margin compression and an expensive P/E versus European luxury peers comes back into sharp focus.
Brunello Cucinelli's narrative projects €1.9b revenue and €197.3 million earnings by 2029. This implies 9.9% yearly revenue growth and an earnings increase of about €62 million from €135.0 million today.
Uncover why Brunello Cucinelli's fair value indicates a 22% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly €20 to €102 per share, which is a huge gap in what Brunello Cucinelli might be worth. That spread sits beside rising debt, higher operating costs, and unfinished boutique expansion plans. Opinions clearly differ, so treat these contrasting views as prompts to explore multiple scenarios.
Explore 3 other Brunello Cucinelli fair value estimates, including one that suggests as much as 76% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Brunello Cucinelli research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Brunello Cucinelli. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Brunello Cucinelli's overall financial health at a glance.
Looking for more investment ideas beyond Brunello Cucinelli?
Once you have formed a view on Brunello Cucinelli, it can help to line that opinion up against other opportunities that match your risk appetite and income needs. The Simply Wall St Screener is built for exactly this kind of comparison across different styles of stocks.
- If you want potential mispricing plus balance sheet strength, start with a 195 high quality undervalued stocks that combine quality fundamentals with the possibility that expectations are too low.
- If capital preservation matters more than chasing every rally, filter for 228 resilient stocks with low risk scores that score well on resilience and financial robustness.
- If reliable cash returns appeal to you, focus on 217 dividend fortresses that pair higher yields with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com