


Could Otis Stock Gain From Its Indonesia Homelift Platform Launch
- Otis Worldwide has launched an online platform in Indonesia that lets homeowners configure its Gen3 Villa homelift, obtain a price estimate, and submit enquiries remotely.
- This digital sales channel gives Otis Worldwide a way to capture home mobility demand directly from households, not just developers or contractors. It also helps keep product configuration and pricing consistent.
- We will look at how Otis Worldwide's investment narrative could be influenced by this Indonesia homelift configuration platform launch.
Scan how Otis Worldwide’s homelift push in Indonesia compares with other home-mobility and building-technology plays by checking our hand picked list of 91 robotics and automation stocks.
Otis Worldwide Investment Narrative Recap
To own Otis Worldwide, you need to believe the elevator and escalator service engine keeps compounding as more units enter its 2.5 million strong portfolio and the large modernization backlog converts. The Indonesia homelift configurator fits that picture only at the margin in the near term. The more pressing near term swing factor remains whether management can stabilise service retention around current levels and keep the service book from drifting lower.
The biggest operational risk is that weak service margins, higher costs and tempered AI pricing rollouts persist, keeping net margin progress slow even as modernization and service volumes hold up. The Indonesian online channel looks incremental rather than transformational to those margin and cash flow pressures. It is better viewed as an execution proof point on digital tools rather than a change to the core risk reward equation around retention, service profitability and cost discipline.
No fresh filings or guidance changes sit directly alongside this Indonesia launch, so the most relevant backdrop is Otis Worldwide’s existing push on connected systems and digital tools. Management already has 1.1 million units tied into Otis ONE and is using AI driven micro pricing in repair, with expectations that these initiatives support service margins in the second half of 2026. The new homelift configurator simply broadens that digital footprint into the residential channel.
For you as an investor, it links back to the same catalysts analysts have focused on for months. The thesis leans on modernization momentum, a growing service portfolio and efficiency programs such as the global service operating model rollout to do the heavy lifting on earnings, while the share price trades at a lower P/E than both peers and the estimated fair P/E of 22x. The Indonesia platform is another operational experiment within that wider digital and service story, not a separate pillar.
Otis Worldwide's narrative projects US$17.4b revenue and US$1.9b earnings by 2029, based on analyst assumptions of 5.2% yearly revenue growth and an earnings increase of about US$0.4b from US$1.5b today.
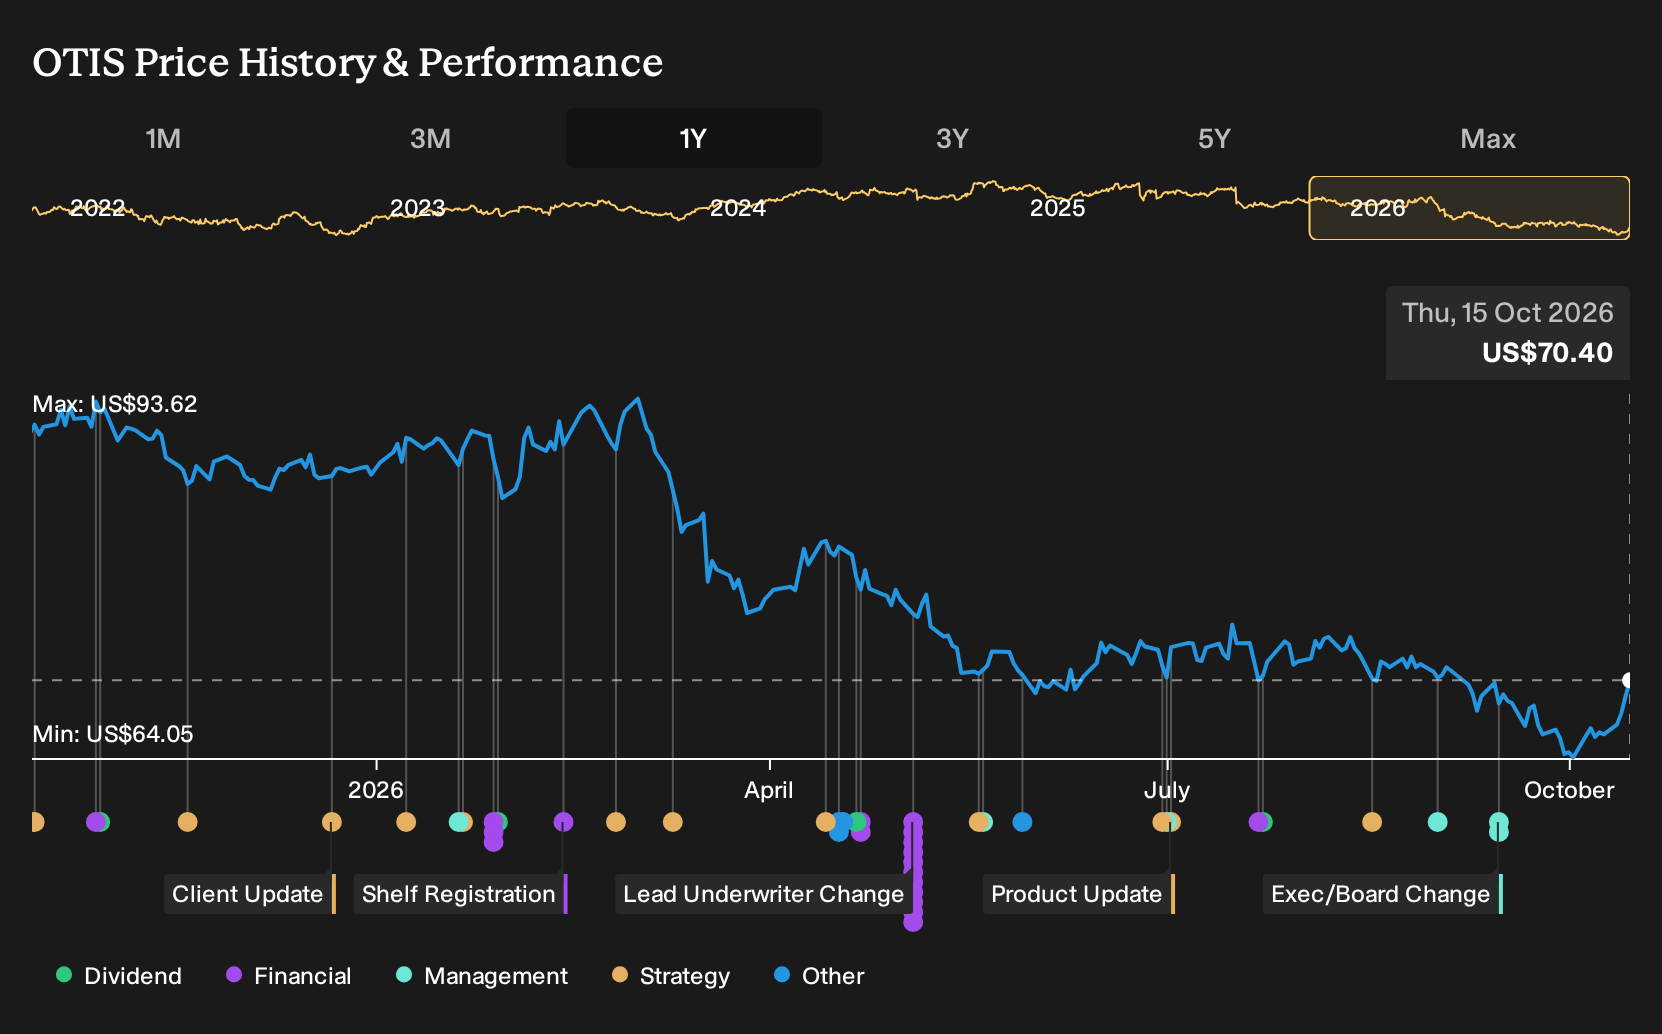
Uncover how Otis Worldwide's fair value indicates a 25% potential upside to its current price, a discount that could narrow quickly if investor sentiment shifts.
Exploring Other Perspectives
One alternate view says the real swing factor is how efficiently Otis Worldwide turns its aging installed base into booked modernization revenue. The most cautious analysts were only baking in roughly US$17.0b of revenue and US$1.9b of earnings by 2029 before this Indonesia homelift platform, so they saw slower progress. Use that gap as a prompt to compare several narratives and decide which assumptions feel more realistic to you.
Explore 4 other Otis Worldwide fair value estimates, including one that suggests it could be worth just $73.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Otis Worldwide research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Otis Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Otis Worldwide's overall financial health at a glance.
Looking for more investment ideas beyond Otis Worldwide?
If the Otis Worldwide story has you thinking about portfolio upgrades, you can use the Simply Wall St Screener to line up other stocks that fit the kind of risk and return profile you want, then compare them against what you see in OTIS.
- For investors who want income to feel more predictable, consider stocks that appear on our 8 dividend fortresses and see which yield profiles line up with your cash flow needs.
- If capital preservation sits high on your priority list, focus on companies in the 32 resilient stocks with low risk scores and weigh their risk scores against Otis Worldwide's profile.
- For those hunting for quality that might be flying under the radar, the 20 high quality undiscovered gems can surface lesser known stocks with fundamentals you can benchmark against OTIS.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com