


What Tripadvisor Investors Missed Before The Fall
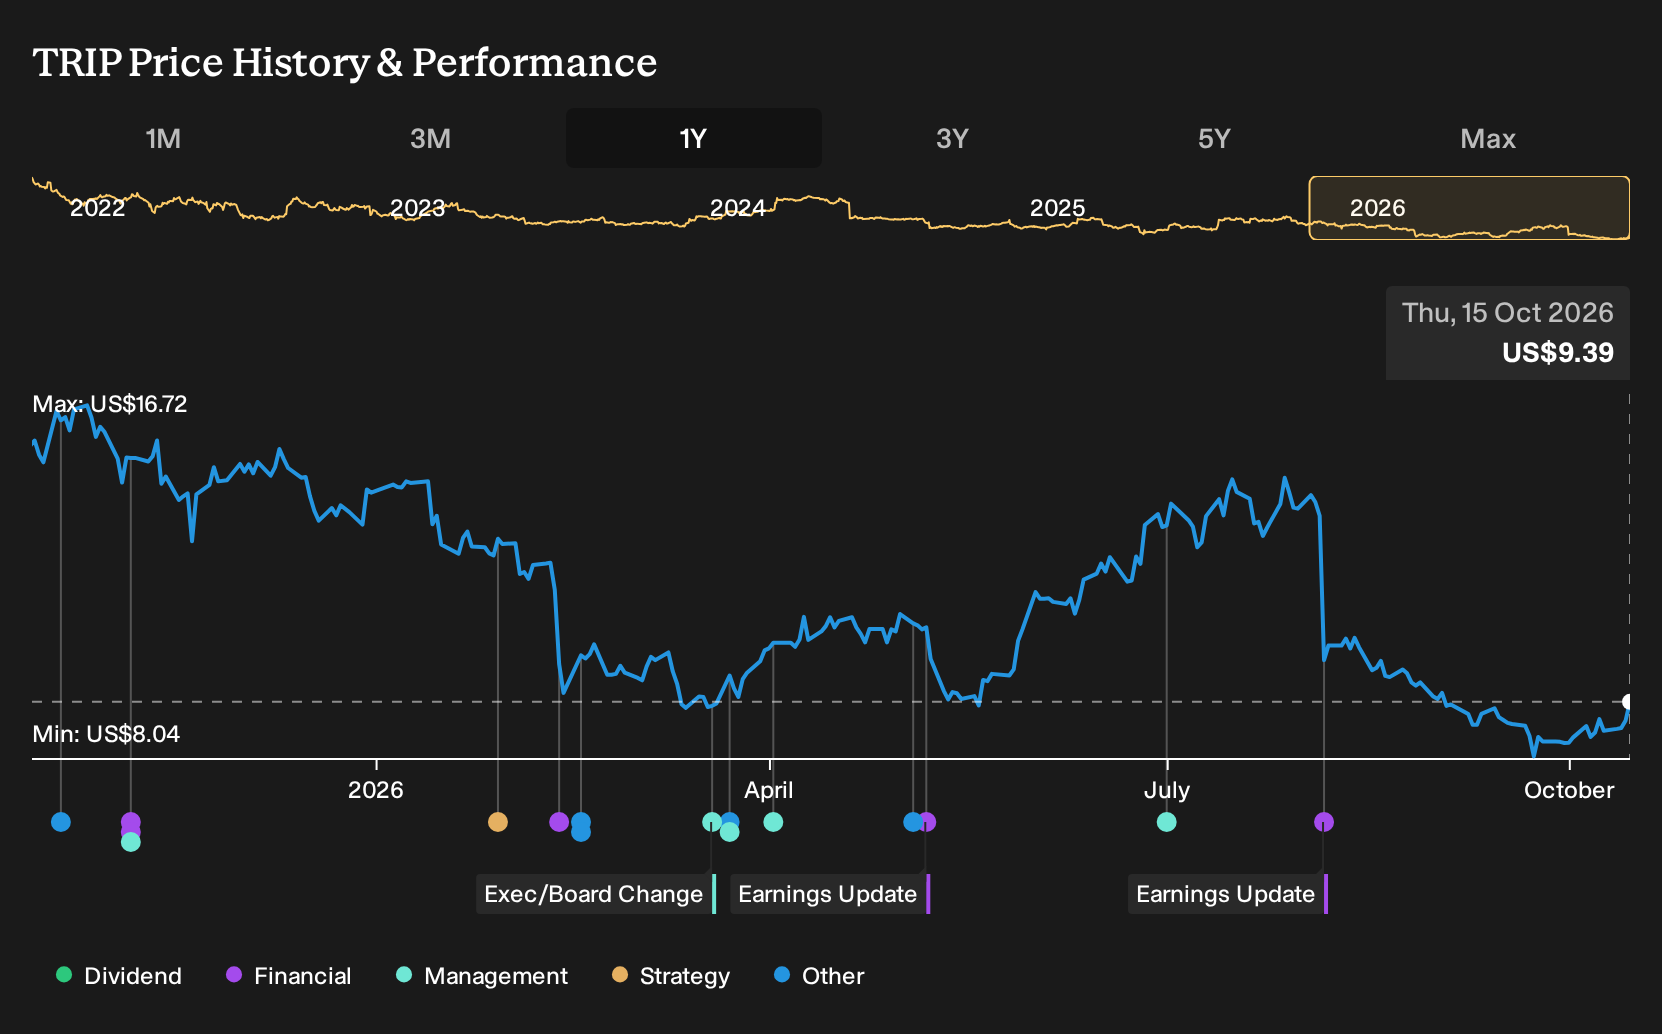
Tripadvisor has dominated recent headlines for agreeing to sell TheFork to American Express for US$700 million in cash, a move framed as a pivot toward Viator and travel experiences. Holding Tripadvisor over the past year would have meant a 39.4% loss, including dividends. If you had committed capital on 15 October 2025 based on the bullish and bearish cases then on record, how does this sale reshape the key question about Tripadvisor’s future role in AI driven travel discovery?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Tripadvisor. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Argument Tripadvisor Investors Actually Faced
The shares cost US$15.85 at the start of the period, and anyone looking at Tripadvisor then had two very different stories on the table.
The bullish Narrative pinned Fair Value at US$17.77 and leaned on Tripadvisor pushing deeper into experiences and B2B. That view relied on AI powered recommendations and loyalty programs keeping users engaged while reducing dependence on costly third party traffic.
The bearish side set Fair Value at US$13 and focused on AI competition and regulation. That camp worried that GDPR style rules and larger platforms would raise compliance costs and squeeze Tripadvisor’s ability to monetize data driven advertising.
What The Tripadvisor Evidence Actually Tested
TheFork’s agreed US$700 million sale to American Express backed the bullish idea that Tripadvisor could recycle capital into Viator and experiences; yet the Q2 2026 figures told a tougher story. Total revenue fell to US$441.9 million from US$476 million, net income slipped to US$22.8 million from US$36.5 million, and net margin declined from 7.7% to 5.2%. The evidence cut both ways.
The clearest hinge in this episode was profitability. For any future Tripadvisor style thesis, focus on whether segment shifts and AI products show up in plain net income and net margin, not just in partnerships, product launches, or upbeat narratives.
What Tripadvisor’s Drop Now Asks You To Believe
Tripadvisor trades at US$9.39, with this Narrative’s Fair Value sitting above that quote. The argument leans on Experiences, AI trip planning, and portfolio pruning doing more of the heavy lifting than the older SEO driven hotel and media lines.
If you buy after a 39.4% loss over the past year, you are implicitly betting that Tripadvisor’s AI products and Experiences shift can offset SEO pressure and softer group revenue enough to support healthier margins and repeat customer economics.
"The main thing that has to go right is that Tripadvisor successfully reallocates capital from shrinking SEO-dependent hotel and media lines into Experiences and AI products that attract repeat customers and profitable B2B2C partners."
One Narrative disagrees with today's price. → See where this Narrative says Tripadvisor should trade
Find Your Own Contrarian Opportunity
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 42% below our estimate - advises on complex product failures and regulations as AI and safety rules tighten.
- Company 2 - 44% below our estimate - converts large data center and industrial backlogs into long-cycle mechanical and electrical projects.
- Company 3 - 50% below our estimate - sells workflow software enterprises adopt once AI driven customer operations outgrow pilot projects.
Three companies from the same screener. Open every one of the 25 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com