


Kidney Research Push Might Change The Case For Investing In DaVita Stock
- DaVita recently outlined plans to present seven kidney care studies at ASN Kidney Week 2026, covering middle molecule clearance, home dialysis practices and patient experience across diverse treatment settings.
- This research push highlights DaVita's effort to link large clinical datasets, real world dialysis operations and patient feedback to inform how emerging therapies are used in everyday kidney care.
- We will look at how DaVita's investment narrative is affected by this expanded research footprint, with particular attention to middle molecule clearance.
Scan how DaVita's push into evidence driven kidney care compares with other health-focused operators by reviewing our curated list of solid balance sheet and fundamentals (25 results).
DaVita Investment Narrative Recap
To stay comfortable as a DaVita shareholder, you generally need to believe the core U.S. dialysis franchise and integrated kidney care can keep offsetting tight reimbursement, payer mix pressure and rising support costs. The ASN Kidney Week research presence looks directionally positive for DaVita’s clinical credibility, although it does not directly change those near term economic pressures.
The nearer term swing factor still sits in execution on integrated kidney care savings and middle molecule clearance rollouts, alongside cost discipline as G&A has recently risen at a double digit pace. Reimbursement updates, payer mix shifts and DaVita’s leverage remain the key operational risks that the conference news does not materially alter.
The Kidney Week 2026 plan to present seven studies, especially on expanded hemodialysis and middle molecule clearance, lines up most clearly with the existing catalyst around broader deployment of expanded dialyzers. Those products were supported by the MOTheR trial and are compatible with existing machines, so evidence from real world datasets can be important to treatment adoption.
For you, the operational question is whether DaVita can translate richer clinical evidence on expanded hemodialysis into better outcomes and stronger adherence without meaningfully increasing cost per treatment. If that happens, it can support the aim of modest treatment growth and earnings resilience, while still sitting alongside reimbursement pressure and higher technology spending as ongoing constraints.
DaVita's current analyst narrative points to revenues of US$16.1b and earnings of US$1.1b by 2029. This is built on an assumed 4.6% yearly revenue growth rate and an earnings increase of about US$277.5m from US$822.5m today.
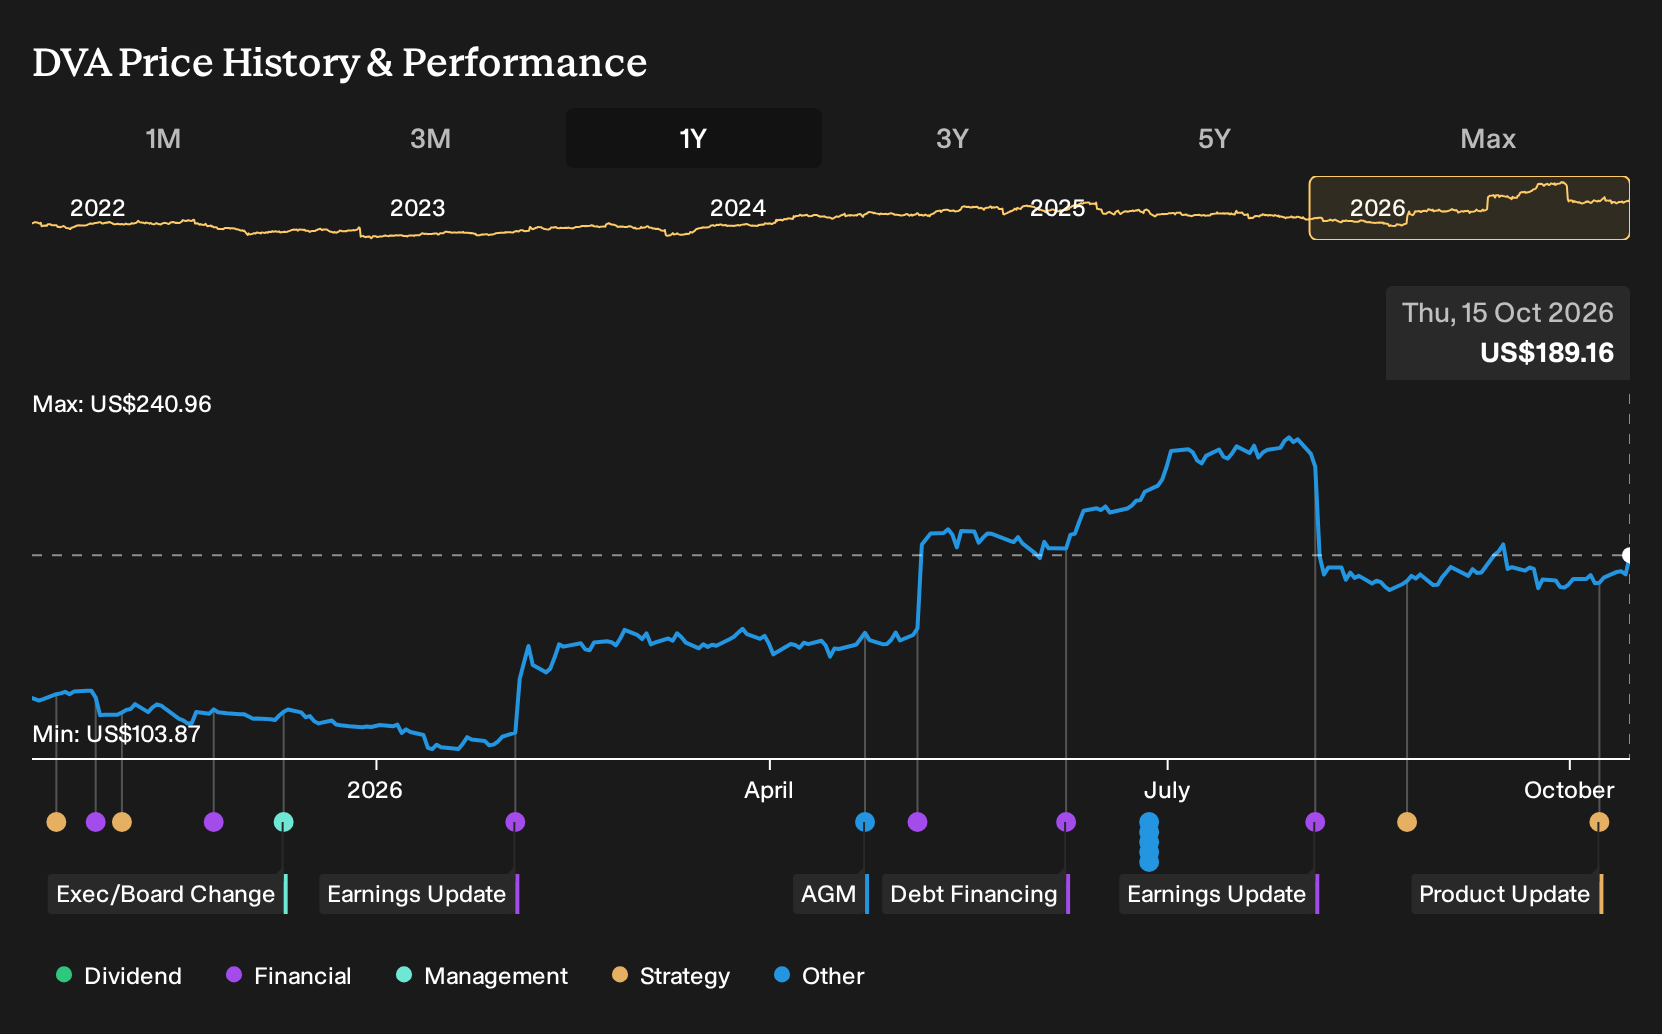
Uncover how DaVita's fair value indicates a 16% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the most optimistic analysts lean on DaVita Clinical Research as a key catalyst, arguing that its large kidney data set and hundreds of trials could support premium reimbursement over time. Before this Kidney Week news, that group was already modeling roughly 6% annual revenue growth to about US$16.5b and earnings of US$1.1b by 2029. You can compare that more upbeat view with the baseline to see how much these research presentations might shift expectations once they are fully reflected.
Explore 2 other DaVita fair value estimates, including one that suggests as much as 142% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DaVita research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DaVita. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DaVita's overall financial health at a glance.
Looking For More Ideas Beyond DaVita?
If you want to balance your view on DaVita with a wider watchlist, the Simply Wall St screener can surface other opportunities that match the type of risk and return profile you prefer.
- For investors who prioritize financial resilience and want to sleep a bit easier at night, start with a 32 resilient stocks with low risk scores that rank well on stability metrics.
- If you like the idea of finding strong businesses before they hit the mainstream, scan through 20 high quality undiscovered gems that pair solid fundamentals with limited current attention.
- Income focused portfolios can use a curated 8 dividend fortresses to spot companies combining higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com