


What Has Actually Changed At Oceaneering International After A 91% Jump
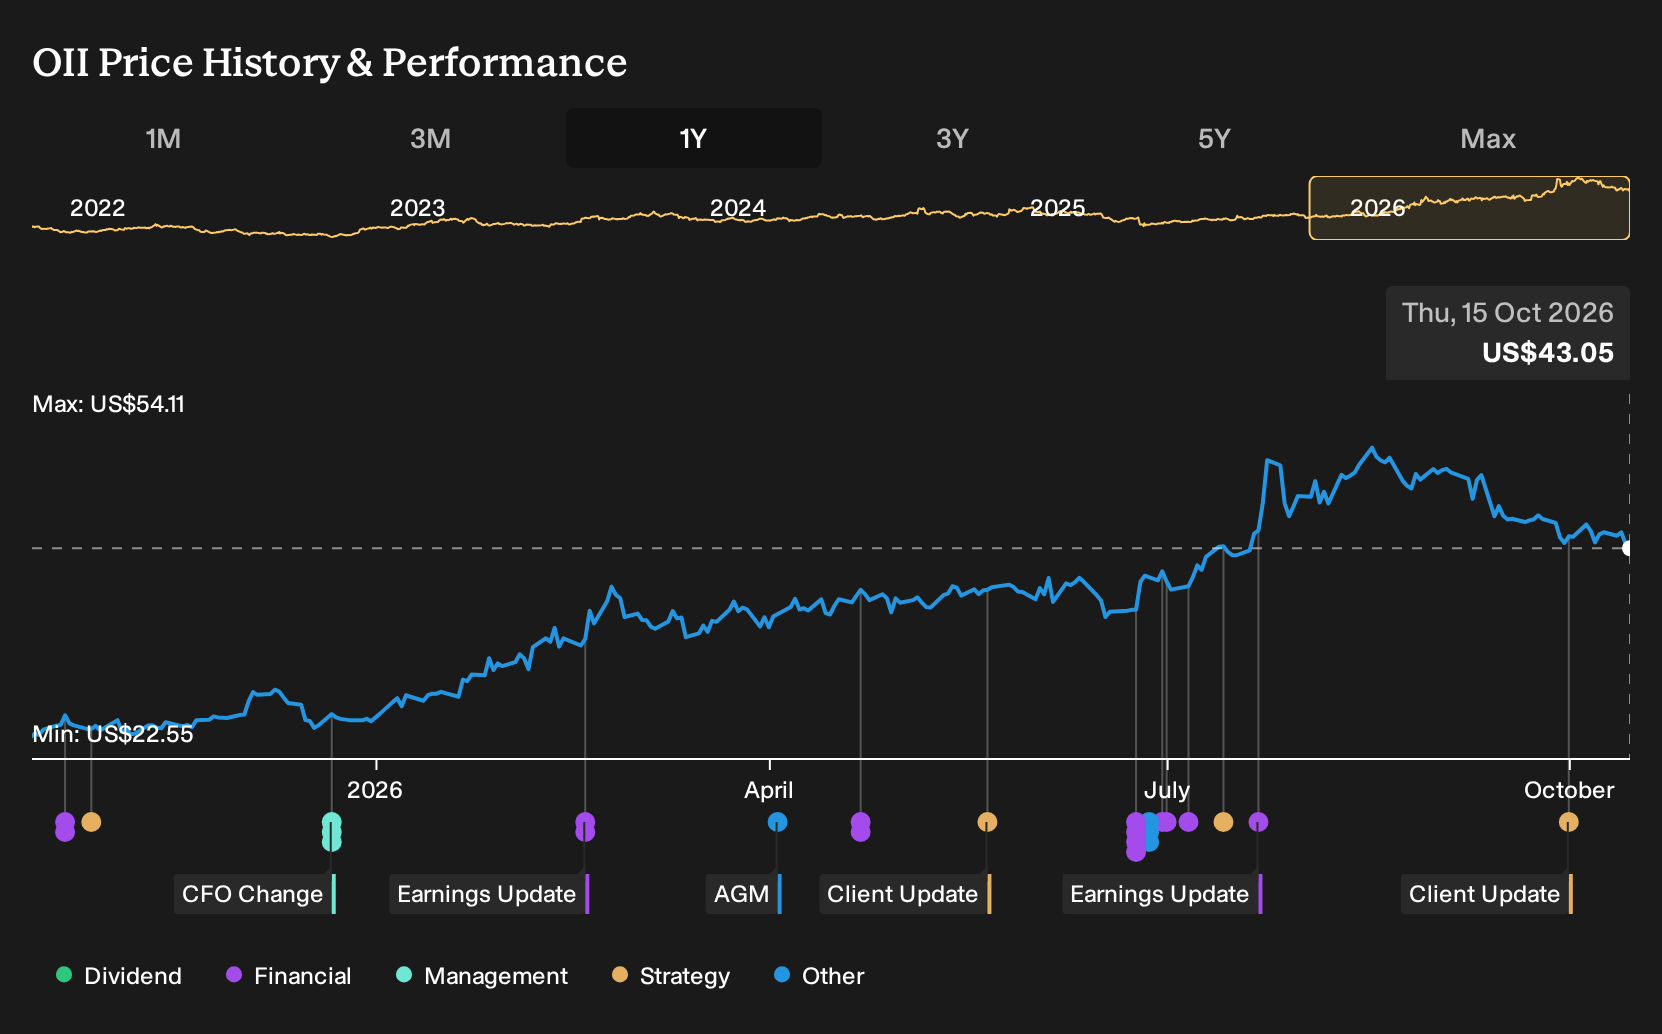
Investors who held Oceaneering International over the past year are up 90.9%, including dividends. If you had been weighing a purchase on 15 October 2025, you were facing conflicting narratives instead of a clear signal. One side argued that offshore ROV demand and defense work could justify a valuation about 10% above the start price, while others warned that ESG pressure and energy transition risk pointed 23% below. Which of those uncertainties would have mattered most to you then?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The move put Oceaneering International in the middle of this trade. Scan 91 robotics and automation stocks for other companies exposed to it.
The Argument You Would Have Weighed On Oceaneering International
The shares cost US$22.66 at the start of the period, and anyone looking at Oceaneering International then had to choose which story felt more realistic.
On the bullish side, a Fair Value of US$25 rested on the idea that revenue might grow 4.1% a year with profit margins settling around 6.0%, supported by demand for offshore ROV work and defense contracts.
The bearish Narrative pointed to a Fair Value of US$17.5 and focused on the risk that the fossil fuel transition and stricter ESG mandates could limit deepwater project funding. In this view, margins were assumed to soften toward 5.9%, and the shares were valued on an 11.5x future P/E.
What The Results Changed For Oceaneering International
The big development came from Oceaneering International’s Q2 2026 results, where revenue moved from US$698.2m in Q2 2025 to US$768.2m and net income also rose, lifting net margin from 7.8% to 8.5%. That outcome leaned toward the optimistic case on utilization and pricing, although margin expectations in the original bullish story are still not fully tested.
The lesson is simple. When a thesis hinges on profitability resilience, keep tracking the net margin trend and compare it directly with the margin path that original forecasts assumed.
What Oceaneering International's Rally Already Prices In
Oceaneering International now trades at US$43.05, after a 90.9% gain over the past year. The selected Narrative sees its Fair Value below that level, arguing the recent climb already prices in a lot of good news.
To buy here, you would need confidence that Aerospace and Defense Technologies and Subsea Robotics keep offsetting weaker areas where backlog and margins are under pressure.
"The main factor that has to go right is that growth engines such as Aerospace and Defense Technologies and Subsea Robotics offset weaker segments such as IMDS and parts of Manufactured Products, where backlog, margins, and regional activity remain under pressure."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where Oceaneering’s World Connects
Once you map Oceaneering International’s offshore story, another pressure point appears. Your attention shifts from subsea robots to what keeps gas moving.
Deepwater projects need steady molecules. So do power-hungry facilities that cannot wait long for grid upgrades.
To bridge that gap, a different specialist designs and runs compression units. These units push gas through gathering systems, pipelines, and on-site turbines.
This work is tied to physics more than sentiment. As pressure needs change and wells age, compression demand can move differently from drilling cycles.
If you follow Oceaneering International, that parallel pressure business might be the next file worth opening.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 53% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com