


3 European Renewable Stocks Retail Investors May Watch For Grid Spending Growth
European renewables now sit at an awkward crossroads. The IMF is flagging tighter public budgets and softer growth, just as governments still need to fund cleaner power, sturdier grids and storage. That mix can punish weaker balance sheets yet reward businesses that already earn their keep. This piece walks through three stocks from our European Renewable Energy and Clean Infrastructure Stocks screener that appear well positioned against those IMF warnings.
The three stocks covered below are just a starting sample from this theme, and the full screen surfaced 20 more European renewables and grid players with equally compelling stories that do not fit into one article. To identify your own highest conviction angles in this space, head straight to the European Renewable Energy and Clean Infrastructure Stocks screener.
NKT (CPSE:NKT)
NKT is one of the more direct ways to gain exposure to Europe’s push to harden power networks for renewables, since its cables, accessories, and related services are used wherever grids are reinforced, interconnectors are laid, or offshore wind farms are connected to the system.
NKT A/S designs, manufactures, and installs low, medium, and high voltage power cable systems and lifecycle services for utilities and energy infrastructure projects that connect renewables to the grid. It reports segment adjustments of €3.76b and intersegment transactions of €168m, and has a market cap of about DKK 45.4b.
"Transmission margins have already reached 20.2% operational EBITDA in a quarter with a 20% organic revenue decline, which indicates a route for NKT to convert future volume growth from the existing transmission backlog into a larger incremental EBITDA contribution than implied by consensus models that focus mainly on backlog size rather than margin sensitivity."
What happens to that earnings path if a single pressure point quietly changes how much profit each extra kilometre of cable actually brings in?
If that sensitivity to each extra kilometre of cable matters to you, read the full narrative for NKT to see whether pricing power is quietly decoupling from volume risk.

Nordex (XTRA:NDX1)
Nordex is one of the clearest pure plays on European onshore wind in this screen, turning the IMF’s renewed push for renewables and energy security into a turbine and long term service business that lives or dies on how efficiently it converts a swelling order book into cash.
"Although Nordex highlights a sizeable order book across turbines and service, the 2026 activity profile is heavily back end loaded, with around two thirds of work concentrated in the second half. Any customer delays or issues at the Turkish blade plant could push revenue recognition and raise working capital swings that weigh on free cash flow and earnings quality."
What really matters for Nordex now is how a relatively quiet shift in project timing and cost pressure filters through to margins and cash generation.
Nordex develops and services multi megawatt onshore wind turbines that feed straight into the renewables theme, with about €7.2b from Projects and €900 million from Service, and a roughly €8.3b market value that signals meaningful scale in European clean energy equipment.
That timing risk cuts both ways, and the full narrative for Nordex shows where delayed projects, cost pressures and service income could be masking a stronger earnings reset for Nordex.

SMA Solar Technology (XTRA:S92)
SMA Solar Technology sits right on the hardware edge of Europe’s renewables push, turning solar panels, batteries and EV chargers into usable power and storage capacity for homes, businesses and large grid scale projects.
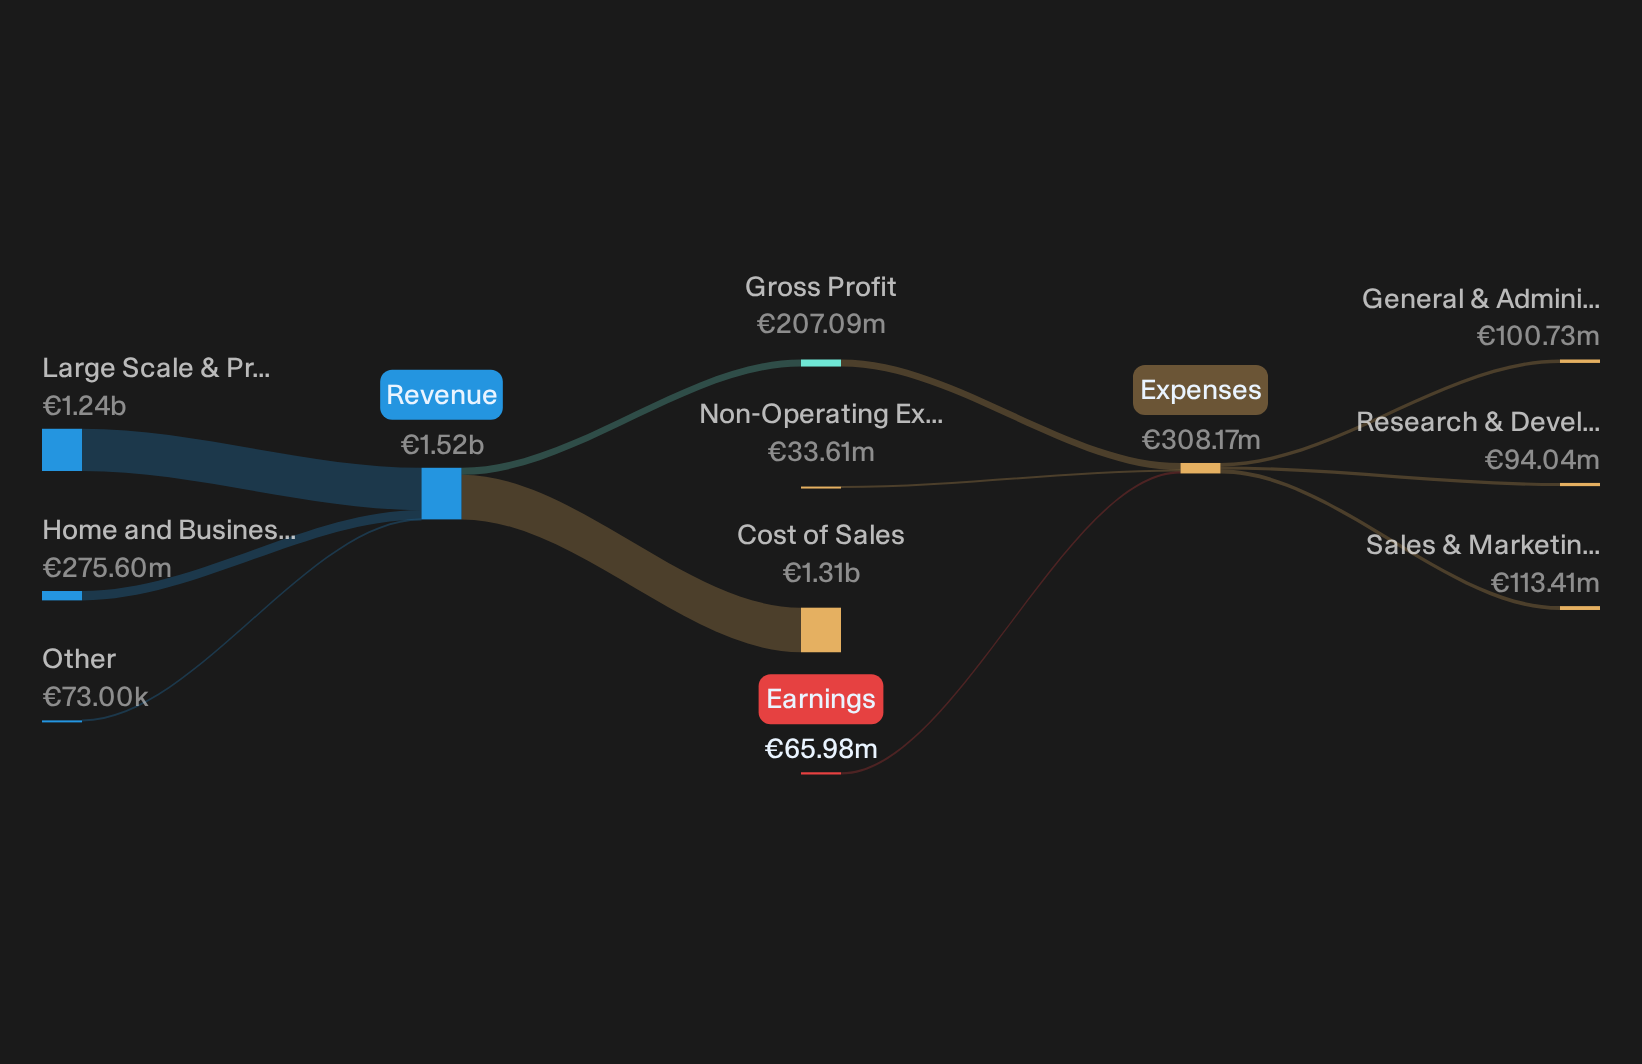
SMA Solar Technology develops PV and battery inverters, energy management systems and EV charging hardware that link straight into Europe’s push for renewable generation, storage and electrification. The group earns about €275.6 million from Home and Business Solutions and €1.24b from Large Scale and Project Solutions, with a market value around €2.0b.
What matters for this stock is not just how many megawatts of solar and storage get installed. It is also how much profit SMA Solar Technology can still squeeze out once policy support, local content rules and grid requirements all feed into its mix of products and contracts.
"Despite a record Large Scale order backlog centered on battery storage and DC coupled hybrid projects, management expects Large Scale EBIT in 2026 to be broadly flat year on year at higher sales because of rising depreciation, service expenses and operating costs, which implies that even full delivery of the backlog might not translate into the margin progression currently embedded in many earnings models."
Everything hinges on how one less visible cost pressure ultimately shapes the payoff investors actually see from that solar and storage backlog.
That cost pressure is only the first layer, and the full narrative for SMA Solar Technology shows how SMA Solar Technology’s backlog, pricing and mix could be quietly resetting the earnings profile.
Seeking Alternatives Before The Crowd
Fresh ideas move first. Breakout themes, new momentum and under the radar sectors can get priced in fast. Screen for them while it matters and get in early.
- Track capital flowing toward resilient balance sheets and let the curated list of solid balance sheet and fundamentals (203 results) show which businesses currently carry the financial muscle to absorb shocks.
- Spot price strength where cash generation already supports payouts by scanning the hand picked 217 dividend fortresses that may keep income streams flying while others stall.
- Ride structural power demand with curated grid players by using the focused 41 power grid technology and infrastructure stocks to see which operators are positioned while electrification momentum is still building.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com