


Did TAG Immobilien's Fall Catch You Out? What Investors Missed
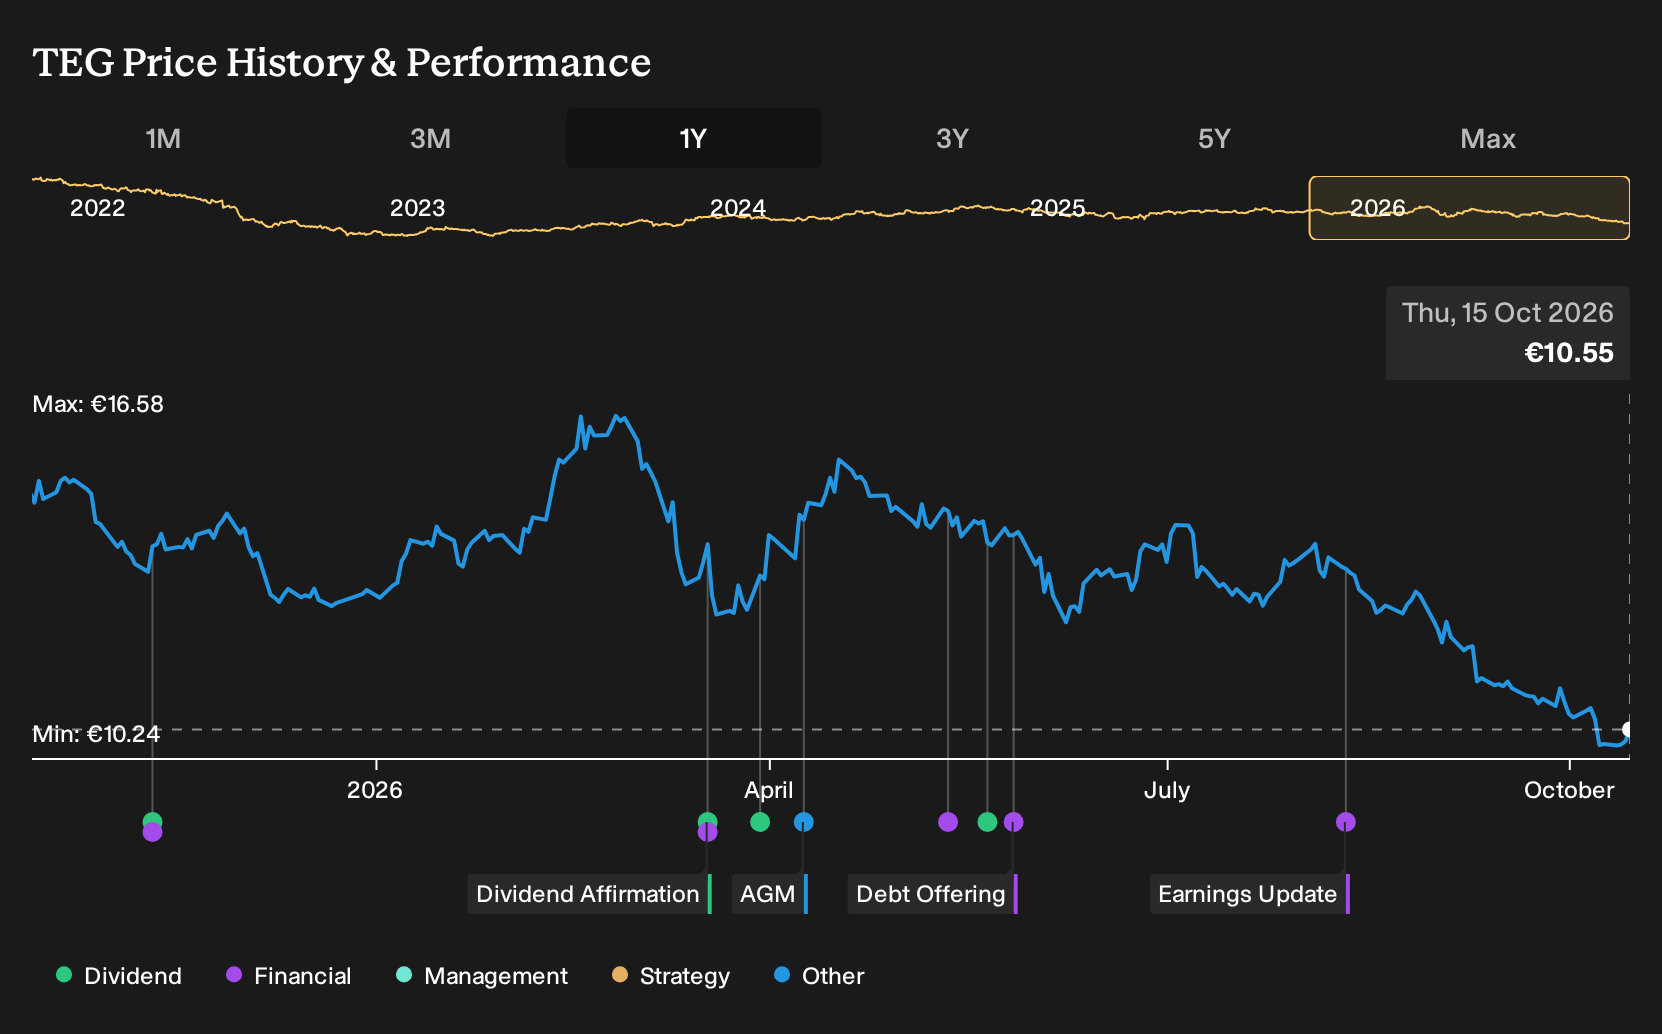
TAG Immobilien opened 2026 by telling the market FFO was up 10% in Q1 and rental growth in Germany and Poland remained firm. The company later secured back to back credit rating upgrades from Moody’s and S&P that highlighted low leverage and strong liquidity. Holding TAG Immobilien over the past year would have meant a 29.2% loss, including dividends. If you had bought in October 2025, how do those strong headlines square with that outcome, and what does the planned Resi4Rent acquisition really need to deliver next?
If the move has made TAG Immobilien harder to judge, start where the gap is still open and scan 195 high quality undervalued stocks.
The Two Stories TAG Immobilien Investors Had To Price In
The shares cost €14.91 at the start of the period, and TAG Immobilien sat between two very different but plausible stories investors were arguing over.
On the optimistic side, the bullish narrative pointed to a fair value of €18.15, essentially a price that would only make sense if assumptions such as revenue shrinking 24.0% with profit margin at 82.5% and a future P/E of 11.4x played out.
The cautious view leaned on a fair value of €13.70 and stressed risks instead, including assumed revenue falling 29.5% per year, profit margin at 89.8%, and a lower future P/E of 10.6x if demographic and regulatory pressures became more pronounced.
What The Results Changed For TAG Immobilien
The key update was TAG Immobilien’s Q1 2026 statement that FFO rose 10%, supported by firm rental growth in Germany and Poland, which leaned toward the optimistic case on cash generation. The later Q2 2026 report told a different story. Revenue moved from €207.0m to €213.6m, while net income dropped and net margin fell from 53.5% to 35.8%. Together, the evidence pointed in both positive and negative directions.
The whole episode turned on one assumption: that stronger rents would translate cleanly into higher profitability. For any other landlord, it may be worth watching the spread between rental income trends and net margin in the quarterly numbers before relying too heavily on FFO headlines.
What TAG Immobilien's Lower Price Now Asks You To Believe
TAG Immobilien now trades at €10.55, after the share price fell 29.2% over the past year from €14.91. The selected Narrative’s Fair Value sits above the current price, based on confidence that recent pressure on the business does not fully capture its longer term earning power.
The Narrative leans on firm like for like rent trends, asset valuations, and a solid balance sheet to argue the stock underestimates that cash generation. For that higher figure to be reached, a buyer today would need to believe that robust rental demand and disciplined expansion can translate into sustained revenue and earnings growth.
"The company is experiencing robust like-for-like rental growth both in Germany (2.9 percent in H1 2025) and Poland (3.3 percent in H1 2025), supported by consistent demand fundamentals. This is described as a factor that could drive sustainable growth in revenue and operating cash flow in the coming years. Strong valuation uplifts were recorded in both German and Polish portfolios, with German residential properties increasing in value by 1.4 percent in H1 2025 and the Polish rental portfolio seeing a step-change uplift linked to increased sales prices. These trends are presented as potential supports for continued growth in EPRA NTA per share and overall asset values."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking Beyond TAG Immobilien
TAG Immobilien is about visible assets, leases and financing choices in real buildings. Yet every contract, tenant change and refinancing decision also produces information.
Real estate investors and lenders increasingly look for reliable data alongside property portfolios. They want consistent records, comparable benchmarks and tools that help them assess risk.
One specialist business focuses squarely on that digital layer across the market. It compiles property details, tracks deals and builds software to turn archives into insight.
The aim is fewer blind spots when capital moves into housing, offices or hotels. While TAG Immobilien shows the physical side, this quieter engine is reshaping how decisions get made.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 17% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com