


Waters (WAT) Launches AI Link, Is The Stock Still Undervalued?
Waters (WAT) has drawn fresh attention after launching its Waters AI Link software, which ties Anthropic's Model Context Protocol and Model Hardware Standard into its lab systems to let AI agents autonomously run experiments and instruments.
These AI and diagnostics announcements have arrived during a strong run for Waters. The 90-day share price return of 20.37% and year-to-date share price return of 16.28% point to building momentum, while the 1-year total shareholder return of 32.63% and 3-year total shareholder return of 76.02% show that recent optimism sits on top of already solid long-term gains.
Scan beyond Waters and size up hand-picked peers riding similar AI tailwinds with the 38 profitable AI stocks that aren't just burning cash that are already proving they can turn algorithms into real earnings.
Waters now looks like a company whose lab automation story is catching up with the share price, rather than just a ticker riding an AI buzz. Do recent gains still line up with what investors are paying for it?
Most Popular Narrative: 3% Undervalued
Waters closed at $444.15 against a widely followed fair value estimate of about $458 per share. This puts its AI heavy lab franchise in focus for how much of that gap might be tied to workflow demand rather than market hype.
Recurring and application specific revenues continue to build, with chemistry columns growing 10% in Q2 2026, underlying chemistry growth at about 16% after timing effects and GLP 1 testing revenue up more than 40%. This points to a larger installed base and higher consumables pull through that can support revenue visibility and operating leverage.
See why 15 investors see Waters as 3% undervalued.
Result: Fair Value of $458.22 (UNDERVALUED)
Still, Waters carries real pressure points, from BD integration risk to ongoing weakness in parts of China. These issues could quickly puncture the current AI driven optimism.
Find out about the key risks to this Waters narrative.
Another View: What Multiples Say About Waters
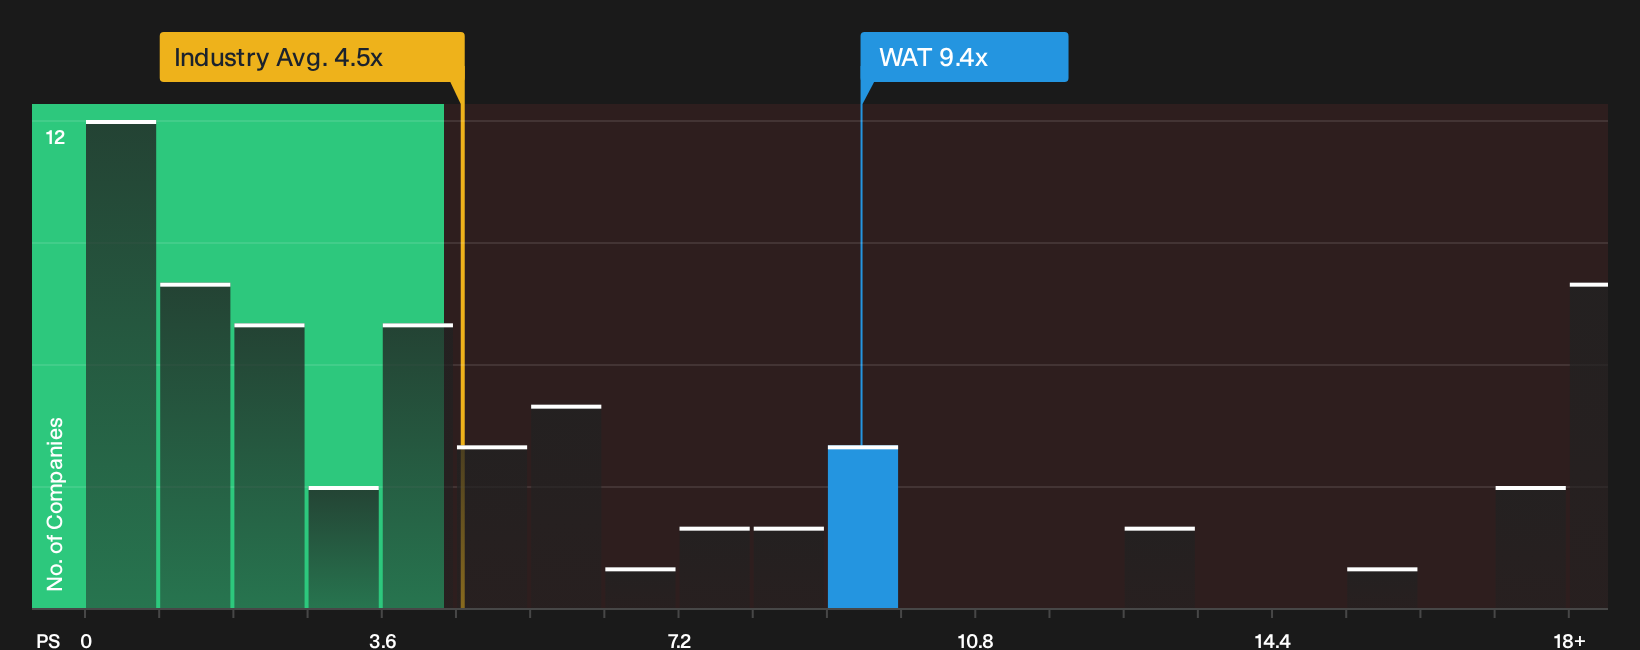
The fair value narrative suggests Waters is about 3% undervalued, yet the market is attaching a rich price tag to its revenue. At a P/S of 9.4x versus a fair ratio of 7.9x, and against a 4.5x industry average and 6.6x peer average, investors are paying a clear premium. The key question is whether that premium reflects a reasonable price for AI and diagnostics momentum or represents a margin of error if expectations slip.
For a closer look at how this pricing gap compares with earnings power and sector norms, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Waters or a clear opportunity forming in front of you? Move quickly and review the full breakdown of 1 key reward and 3 important warning signs
Looking for more Waters-sized investment ideas?
Do not stop with Waters. Broaden your watchlist now and use the Simply Wall Street Screener to uncover opportunities that could suit your goals just as well.
- Target quality at a markdown and scan for companies trading below their estimated fair value through the 33 high quality undervalued stocks.
- Prioritise staying power and filter for businesses with stronger balance sheets and fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Lock in potential income streams and search for higher yielding payers through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com