


Ford (F) Faces Certified Class Action Over Diesel Fuel Pump Defects
- Ford Motor (NYSE:F) faces a certified class action after a federal court approved diesel truck fuel pump claims involving CP4 units.
- The lawsuit now groups together truck owners from five states over alleged safety defects in the CP4 high pressure fuel pump.
- Certification moves the dispute closer to trial, opening the door to coordinated discovery and potential statewide outcomes for plaintiffs.
- The CP4 fuel pump class certification is important. However, investors should weigh it alongside Ford's broader business profile. We have also flagged 3 other big wins for Ford Motor.
Legal risk in autos often rhymes across manufacturers, so it can be useful to study other suppliers tied into vehicle systems via 94 AI infrastructure stocks.
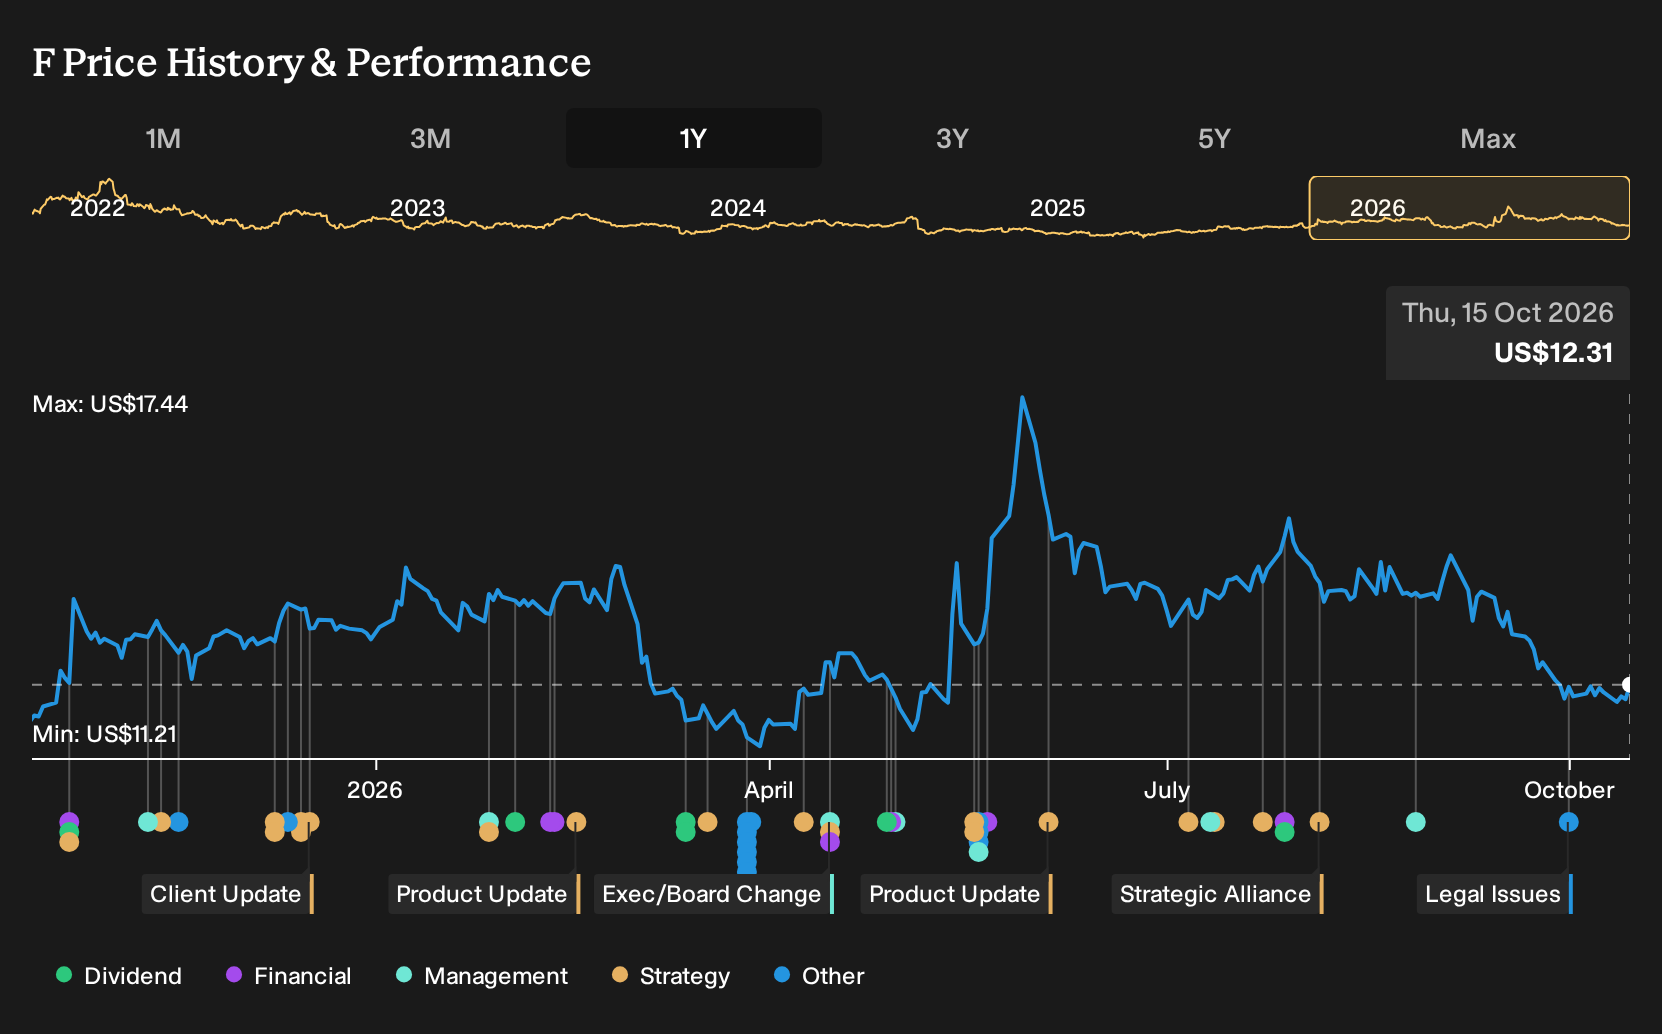
Ford Motor operates a global auto business that designs, builds, and services trucks, SUVs, commercial vans, cars, and Lincoln luxury vehicles. Any dispute involving core components like diesel fuel pumps speaks directly to how its broader product portfolio is engineered and supported across key markets.
See how Ford Motor's balance sheet measures up.
How this Ford Motor lawsuit rubs against a quality-and-software Narrative
The Ford Motor Narrative leans on better quality, lower warranty costs and growing software-style income. A certified class action over diesel pumps pushes directly against that bet on cleaner execution and cost control.
"Ford Motor is targeting an 8% company EBIT margin by 2029 and has highlighted quality improvements such as... a planned US$1b reduction in material and warranty costs in 2026..."
See how the full story points towards a $15.70 fair value for Ford Motor.
The fuel pump case exposes the fragile part of that story. Large recall or repair obligations on older diesel trucks would pull in the opposite direction of Ford’s planned US$1b cut in material and warranty costs, and they would sit alongside earlier F 150 recall pressures that analysts already flag in the Narrative.
At the same time, the claim is narrow compared with the wider push into software subscriptions, Ford Pro services and the Universal EV platform that the thesis focuses on, especially versus peers like General Motors or Stellantis that carry their own legal and recall exposure. The practical question is whether this dispute remains a contained legacy clean-up or starts to change the trend line on quality metrics and free cash flow.
To make sense of litigation like this for Ford Motor, you need a clear view on where management is trying to take margins and software-led earnings, which is exactly what a consistent Narrative spells out.
One more thing about Ford Motor that investors cannot ignore
Analysts have laid out where they think Ford Motor ends up a few years from now, and that roadmap points to a destination today's headlines do not really hint at. See where analysts expect Ford Motor to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com