


Is Antero Resources (AR) Still Undervalued Based On Earnings?
Antero Resources has delivered a strong share price outcome over the past several years, which naturally pushes investors to ask whether the current tag is still supported by its earnings power. With the stock recently closing at US$36.44, the key issue is how that price lines up against what the business is actually generating in profit.
- Over the past 5 years, Antero Resources has returned 86.1%, which puts real weight on whether that kind of gain is matched by the underlying earnings profile.
- The business model is tightly tied to energy prices and capital-intensive production, so valuation now leans heavily on how efficiently those operations convert into sustainable earnings.
- The analysts covering Antero Resources have run their own numbers. See what analysts think Antero Resources's shares could be worth.
The issue now is whether Antero Resources' current share price can be justified by its earnings when set against a Fair Ratio benchmark.
If you are considering whether Antero Resources' earnings support its recent 5 year return, it can be helpful to compare the company with other 33 high quality undervalued stocks
Does Antero Resources Look Undervalued on Earnings?
P/E fits Antero Resources because investors often look at how much they are paying for each dollar of accounting profit in a cyclical energy producer.
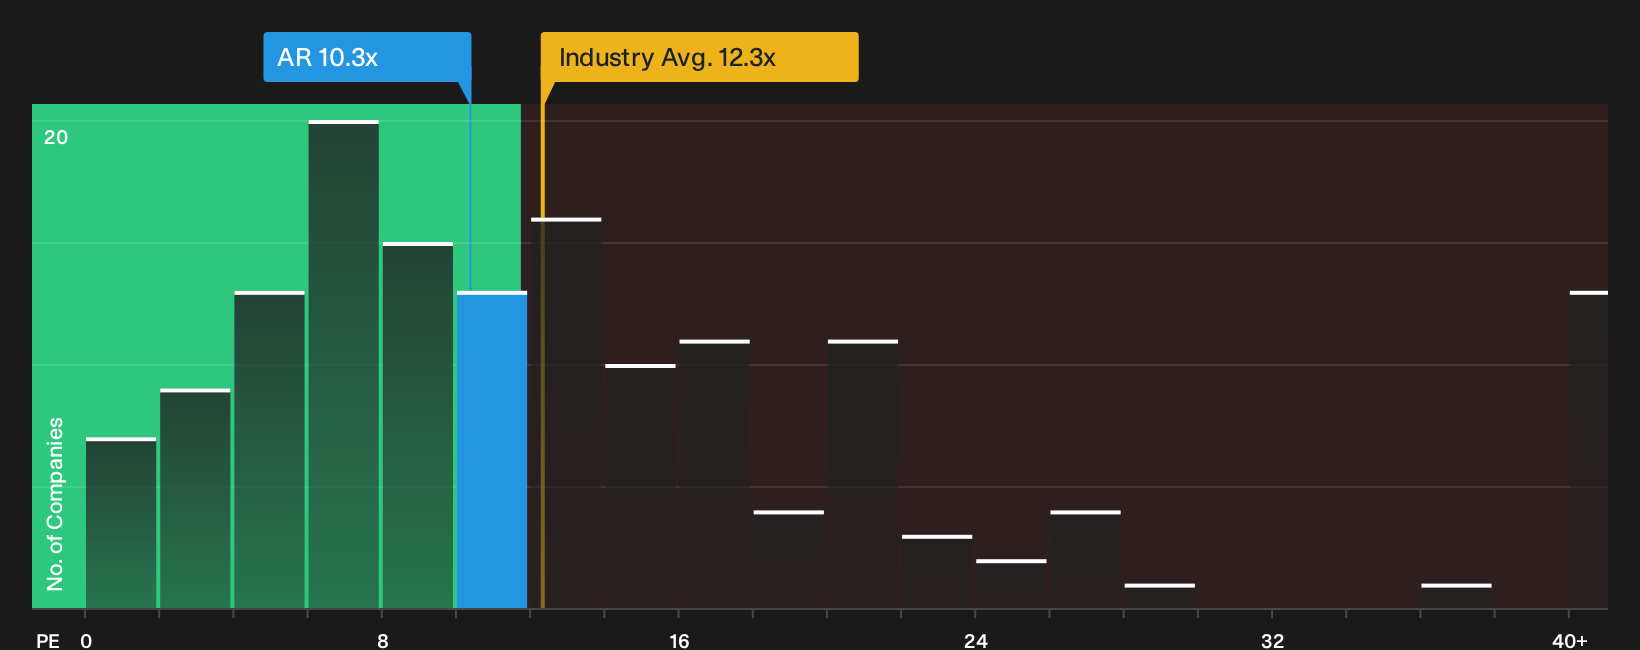
The stock trades on a P/E of roughly 10.3x, compared with an Oil and Gas industry average of about 12.3x and a peer group around 11.1x. On a simple comparison, the shares change hands at a lower earnings multiple than many similar producers. A tailored Fair Ratio, which reflects Antero Resources' sector, size and risk profile, points to a higher level than where the current P/E sits. That suggests the market is assigning a relatively cautious price tag to the company’s earnings stream.
For a holder or potential buyer, the key question is whether Antero Resources' cash generation, capital intensity and exposure to commodity swings justify that lower P/E or argue for something closer to the Fair Ratio benchmark. Explore the numbers behind Antero Resources's P/E valuation.
The Antero Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Antero Resources pick up where the P/E puzzle leaves off and describe what combination of growth, margins and earnings would be required for the stock to trade meaningfully above or below today’s level. Each scenario links Antero Resources' possible catalysts and key risks to a specific fair value marker, allowing you to track over time which version of the story appears to be taking shape on the Community page.
One of the top community narratives on Antero Resources: 9% undervalued
"The main thing that has to go right is that Antero Resources converts its identified structural cash cost reductions, HG integration synergies, and liquids pricing leverage…"
Discover why this Narrative puts Antero Resources at 9% undervalued.
The share price is only one piece of the Antero Resources story
Before you decide how Antero Resources fits in your portfolio, it is worth understanding who is steering the business and how their pay packets line up with your interests. See who runs Antero Resources and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com