


Equinox Gold (TSX:EQX) Posts Fresh Production Data And Buybacks, Is The Stock Still Cheap?
Equinox Gold (TSX:EQX) just paired fresh production data with a completed buyback tranche, giving investors new numbers on both operating output and capital allocation as of mid October 2026.
At around CA$15.72, Equinox Gold has seen a sharp 29.92% 90 day share price return, even though the share price return since the start of the year is down 16.56%. At the same time, the 3 year total shareholder return of 150.15% points to powerful longer term momentum that recent buybacks and fresh production data are helping to refocus.
Scan for other gold producers showing similar production momentum and capital returns by jumping into our curated list of 35 elite gold producer stocks alongside Equinox Gold.
After a sharp 90 day run and a weaker year to date track record, Equinox Gold now forces a timing call. Is it better to step in after this move or wait for a cheaper shot at the same assets and cash flows?
Most Popular Narrative: 36% Undervalued
On the most followed view of Equinox Gold, a fair value of about CA$24.73 sits well above the latest CA$15.72 close, which puts the current rebound against a much higher long term earnings and cash flow story.
Successful ramp-up of Greenstone and Valentine mines, combined with the recent merger, positions Equinox Gold for significantly higher output and scale, supporting meaningful revenue and cash flow growth in the coming quarters as new production fully contributes.
Ongoing operational improvements, including reduced dilution, enhanced mining rates, and technical upgrades at Greenstone, are set to expand net margins through efficiency gains and lower unit costs, directly impacting profitability.
See why 52 investors see Equinox Gold as 36% undervalued.
Result: Fair Value of CA$24.73 (UNDERVALUED)
Still, if ore grades at key mines stay below plan or community issues at Los Filos flare again, the Equinox Gold rerating story could easily stall.
Find out about the key risks to this Equinox Gold narrative.
Another View: What Equinox Gold’s P/E Is Telling You
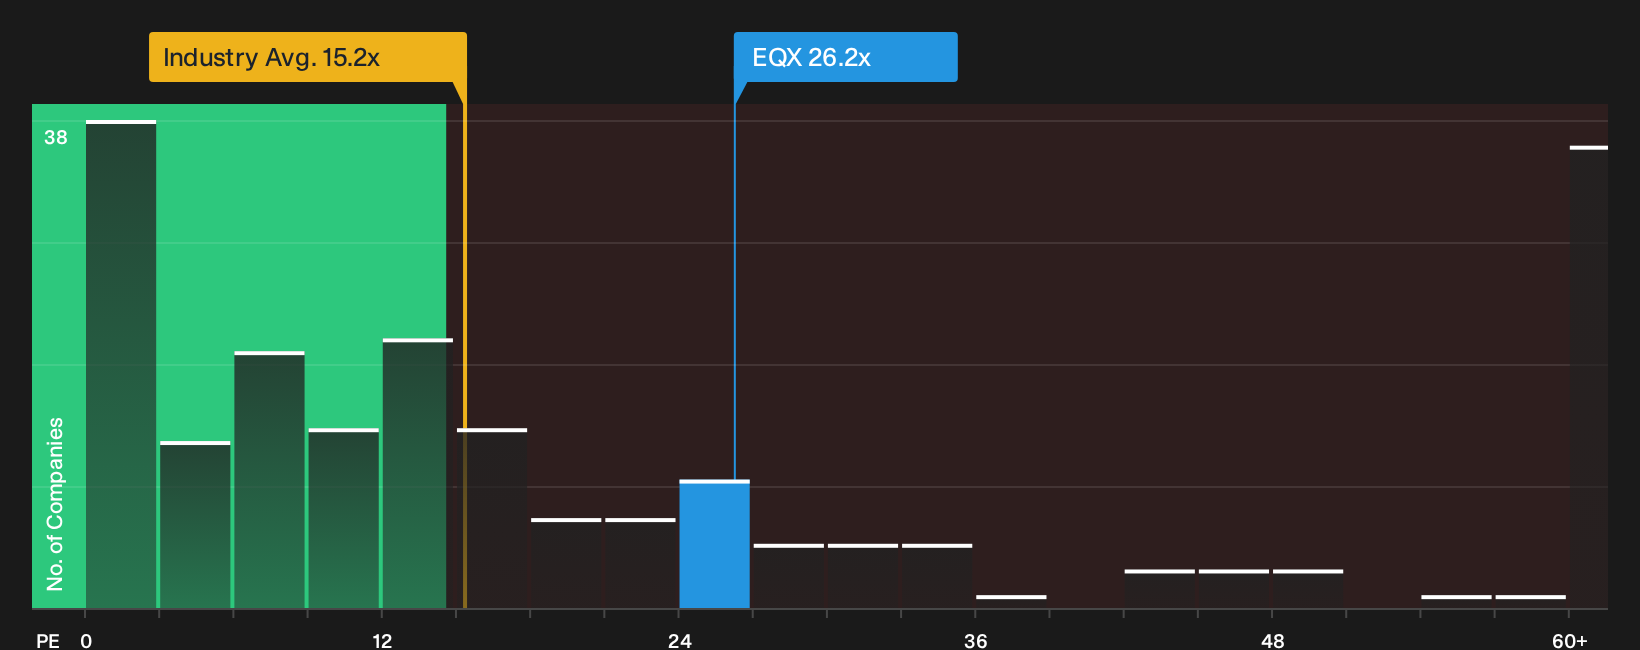
The discounted cash flow work and analyst fair value of CA$24.73 point to Equinox Gold as undervalued. The P/E story is very different. At 26.2x, the shares trade well above the Canadian Metals and Mining group on 15.2x and peers on 14.7x, and even above a fair ratio of 24.2x. That richer multiple can signal investors are already paying up for a lot of the expected growth. How comfortable are you paying a premium today for a business still bedding down new assets and a new leadership bench?
See what the numbers say about this price: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Equinox Gold so far. If you want to move fast and still keep your own independent view, start by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Equinox Gold?
Equinox Gold is only one way to put your capital to work. Broaden your watchlist now so you are not relying on a single story.
- Target resilient compounding potential by scanning a 8 resilient stocks with low risk scores that aims to keep downside surprises in check while still giving you room to participate in upside.
- Hunt for mispriced opportunities by reviewing a 6 high quality undervalued stocks that filters for quality fundamentals with prices that lag what the financials suggest.
- Spot early-stage potential by tracking a 18 elite penny stocks with strong financials that focuses on smaller companies with enough financial strength to support their plans.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com