


Action Growth Might Change The Case For Investing In 3i Group (LSE:III)
- 3i Group recently highlighted that its largest holding, Dutch discount retailer Action, is reporting year-on-year sales growth and higher operating profit, alongside an update that group net asset value per share rose even after paying its second 2026 dividend.
- This combination of Action’s trading momentum and resilient net asset value underscores how a single core holding can materially influence 3i Group’s overall portfolio profile and income capacity.
- We will now look at how 3i Group’s investment narrative is influenced by this Action driven net asset value strength.
Scan beyond 3i Group and shortlist other overseas-focused trusts with strong cash generators in their portfolios using our hand picked 5 high quality undiscovered gems.
3i Group Investment Narrative Recap
To own 3i Group, you need to be comfortable with a private equity style vehicle where net asset value and cash distributions are driven heavily by a few large holdings, especially Action. The latest update that net asset value per share rose even after paying the second 2026 dividend supports the idea that the existing portfolio is currently supporting income and valuation.
The short term swing factor is how Action and the wider European exposure trade through currency moves and political noise, given prior foreign exchange translation losses and regional risks. The biggest operational risk remains concentration. Any setback in Action or in weaker sectors like autos or North American recruitment could weigh on 3i Group’s earnings profile.
With no fresh regulatory announcements flagged alongside this update, the most relevant reference point is still 3i Group’s earlier guidance around expanding its private equity investment and realisation pipeline. That focus on disciplined dealmaking and exits is what links Action’s performance today to future cash generation and potential reinvestment opportunities across the wider portfolio.
For you as a shareholder, the key question is whether management can keep crystallising value through disposals and refinancings while managing leverage and funding risk, especially after Action’s refinancing increased debt at that asset. Execution on those plans, combined with November’s half year results, is likely to shape how the market views both the sustainability of dividends and the robustness of net asset value from here.
3i Group Consensus Forecasts In Focus
Analysts looking at 3i Group are effectively asking you to weigh a portfolio that is highly skewed to Action against a set of forecasts that stretch out to 2029. The picture that comes through their numbers is one of rising revenue expectations paired with softer profit margins and slightly lower earnings, which is a useful contrast with the recent strength in net asset value and dividends.
On their assumptions, the top line is expected to grow by 9.2% a year for the next three years, yet profit margins are projected to move from 94.8% today to 71.6% in three years. That drop in profitability means consensus earnings are forecast to sit at £6.2b by 2029, compared with £6.3b today, so the market narrative here is not one of runaway profit expansion even with revenue rising.
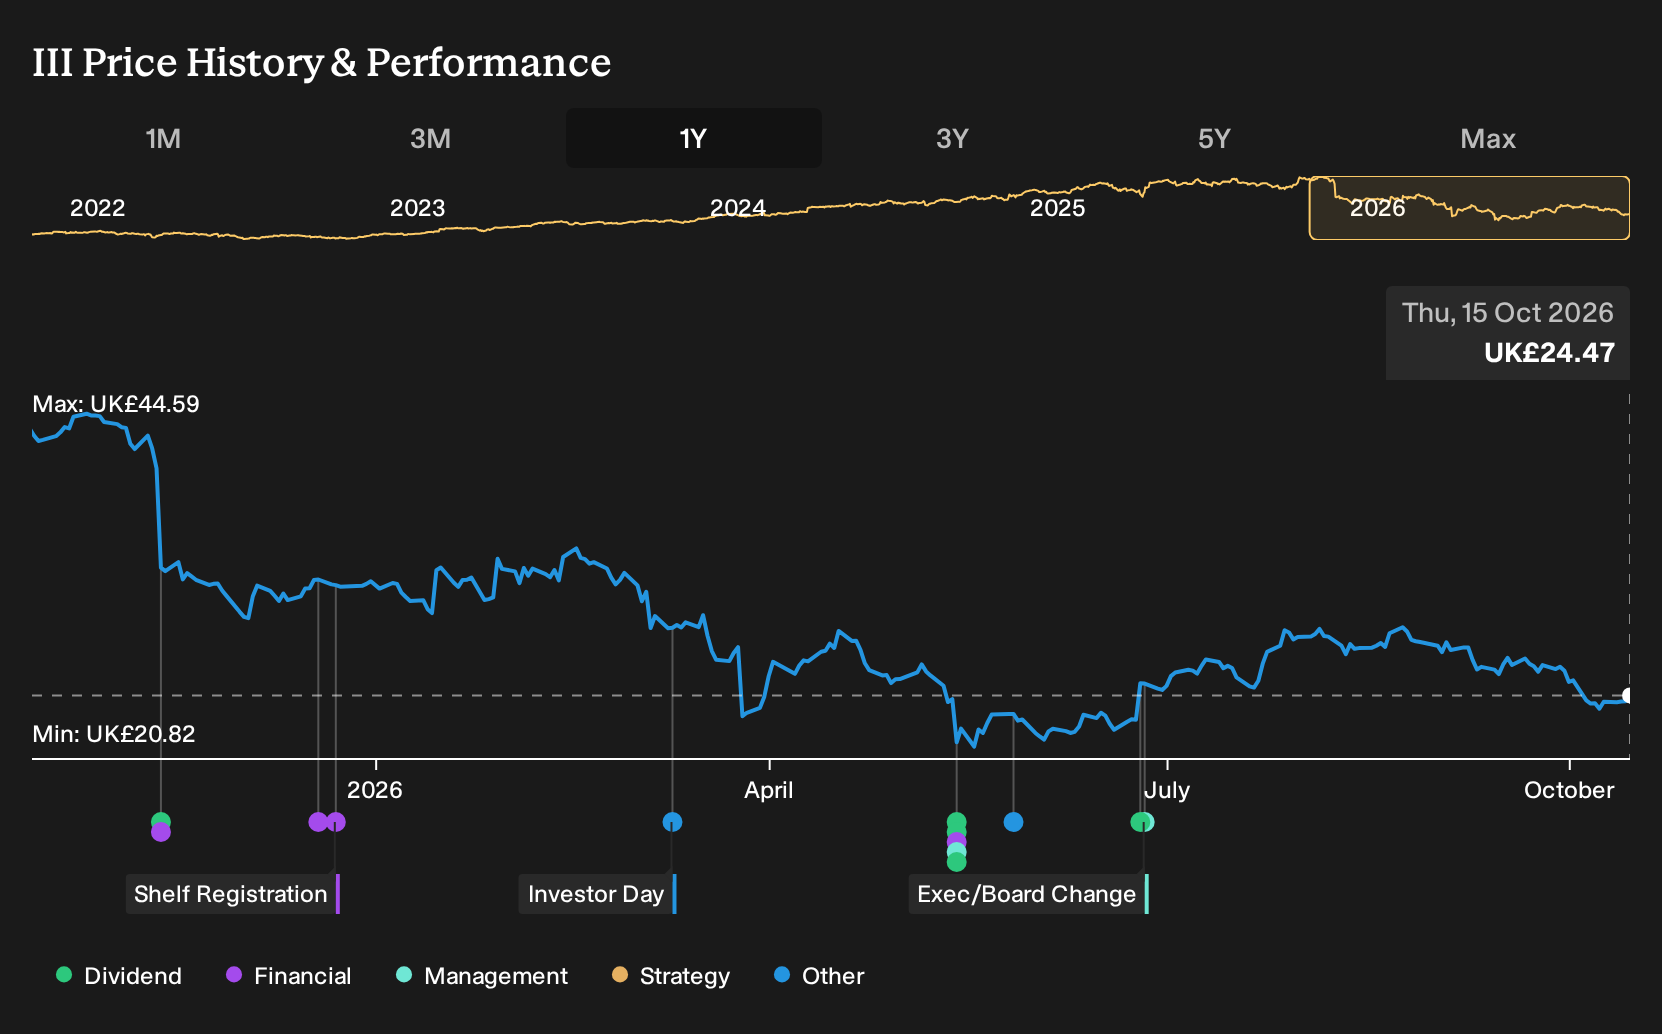
Analysts stitching these inputs together reach a consensus target price of £38.44, against a current share price of £26.01. The most optimistic forecast is £52.00, while the most cautious stands at £19.50. To square those targets with 3i Group’s current valuation, the forecasts point to 2029 revenue of £8.6b and earnings of £6.2b, and a P/E ratio of 8.3x on those projected profits, compared with 4.2x today and an industry level quoted at 12.8x for GB Capital Markets.
Under that framework, you are being asked to assume the share count grows by roughly 2.19% a year and to discount future cash flows at just over 8%. Currency swings, changes in European sentiment and the performance of more cyclical sectors like autos and North American recruitment all sit in the background as variables that could tilt earnings, especially now that Action’s refinancing has lifted leverage at that asset.
3i Group's narrative projects £8.6b revenue and £6.2b earnings by 2029. This rests on 9.2% yearly revenue growth and an earnings decrease of about £0.1b from £6.3b today.
Uncover why 3i Group's fair value indicates a 57% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans heavily on Action’s rapid store rollout as the real swing factor for 3i Group. Bullish analysts were already pencilling in roughly 20.6% yearly revenue growth and earnings of about £7.1b by 2029, far above consensus. Those projections were set before this latest Action update, so opinions may evolve.
Explore 3 other 3i Group fair value estimates, including one that suggests as much as 211% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your 3i Group research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for 3i Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 3i Group's overall financial health at a glance.
Looking for more investment ideas beyond 3i Group?
Once you have formed a view on 3i Group, it can help to line up a few contrasting opportunities so you are not dependent on a single theme or region.
- If you want potential income with a focus on resilience, start with a shortlist of companies offering reliable yields through the 4 dividend fortresses.
- For investors who care most about quality at a reasonable price, filter for businesses that combine strong fundamentals with attractive valuations using the 9 high quality undervalued stocks.
- If capital preservation and smoother returns matter to you, concentrate on companies screened for more resilient profiles through the 4 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com