


OneMain Holdings (OMF) Stock Looks Below Fair Value On Earnings
OneMain Holdings has had a bumpy share price path recently, yet the bigger story is how its earnings stack up against what investors are paying today. With the stock pulling back in the short term after a strong multi year run, the question now is whether current earnings can support that valuation.
- Over the past 3 years the stock has returned 88.7%, which puts a lot of weight on whether OneMain Holdings' profit power really underpins that gain.
- The business model leans heavily on turning interest income into consistent net earnings, so the durability of those profits may shape how comfortable you feel with the earnings multiple the market is assigning.
- There is a second opinion on OneMain Holdings worth weighing. See what analysts think OneMain Holdings's shares could be worth.
The stock's next move may depend on whether OneMain Holdings' current share price is justified by the earnings it is generating today.
If you are weighing whether OneMain Holdings' earnings justify its current P/E, it can help to compare them with a broader set of companies with 33 high quality undervalued stocks that meet similar value focused criteria.
Is OneMain Holdings a Bargain on Earnings?
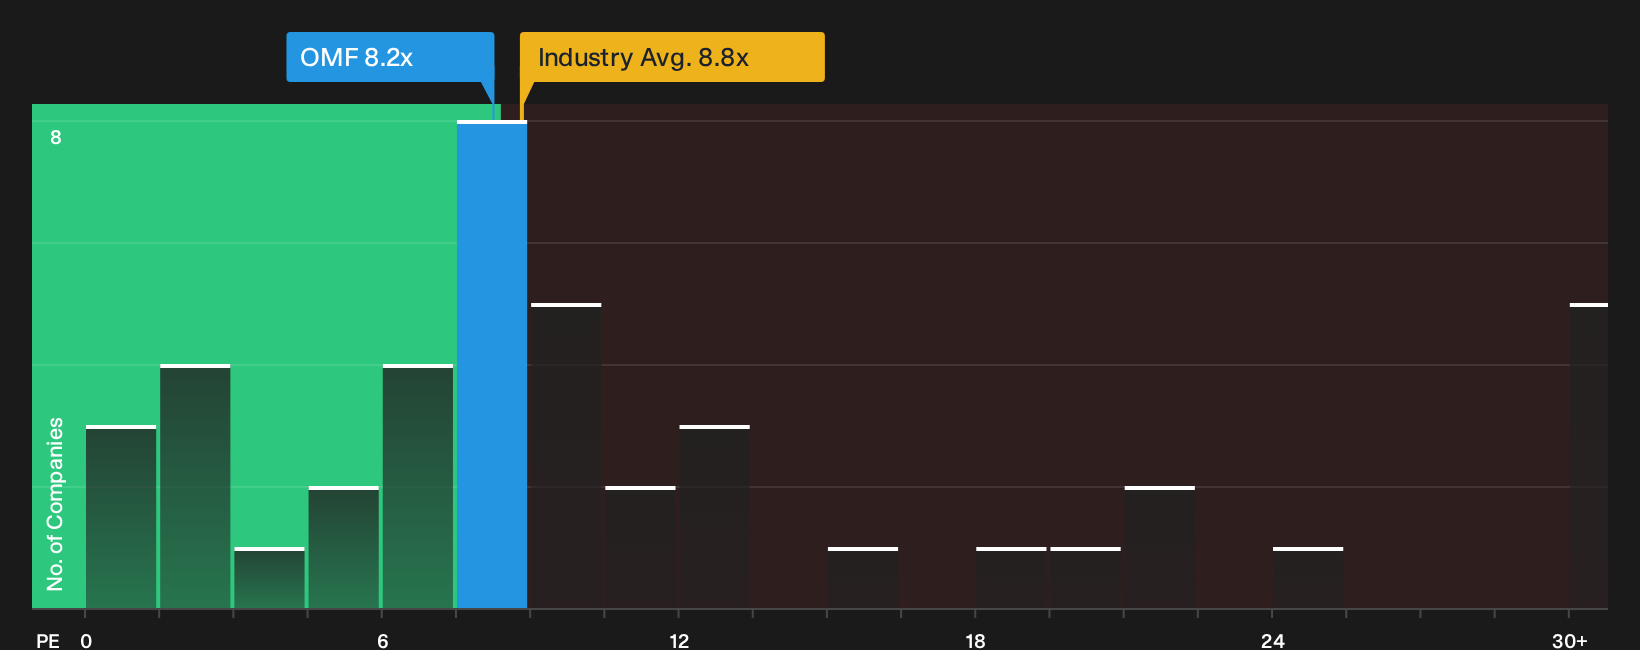
The P/E lens fits OneMain Holdings because earnings are the main driver of how investors value a consumer finance business. The stock trades on a P/E of 8.2x, which is slightly below the Consumer Finance industry average of 8.8x and far below the broader peer group at 18.5x. That gap signals the market is applying a lower earnings multiple to OneMain Holdings than many similar companies, even though the sector benchmark is already restrained compared with the wider market in many periods.
A tailored model that factors in OneMain Holdings' profitability profile, balance sheet intensity, size and risk suggests a higher P/E would be consistent with those fundamentals. This points to the current 8.2x level screening as undervalued on this framework. For an investor weighing the stock, the key question is whether the earnings that support this ratio look steady enough for that discount to matter over time. Explore the numbers behind OneMain Holdings's P/E valuation.
The OneMain Holdings Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the P/E puzzle leaves off by spelling out which paths for OneMain Holdings' growth, margins and earnings would need to play out for the shares to look meaningfully cheaper or more expensive than today. Each storyline on the Community page ties a fair value estimate to a specific mix of potential catalysts and setbacks, so you can track over time which version of OneMain Holdings' future seems to be unfolding.
One of the top community narratives on OneMain Holdings: 19% undervalued
"The current valuation implies the share price does not fully reflect growth in managed receivables, the contribution from auto and card products…"
Discover why this Narrative puts OneMain Holdings at 19% undervalued.
Before you act on OneMain Holdings' valuation, there is one more angle to check
The price tag on OneMain Holdings only tells part of the story. The people directing capital and the way their rewards are structured can heavily shape future decisions and risk. See who runs OneMain Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com