


What to Expect From Eaton’s Q3 2026 Earnings Report
Eaton Corporation plc (ETN), with a market capitalization of approximately $158.8 billion, is a global power management company operating in more than 160 countries. Based in Dublin, Ireland, the company manufactures electrical, aerospace, hydraulic, and vehicle products and provides related services that help businesses manage power more safely, efficiently, reliably, and sustainably across critical industries and infrastructure.
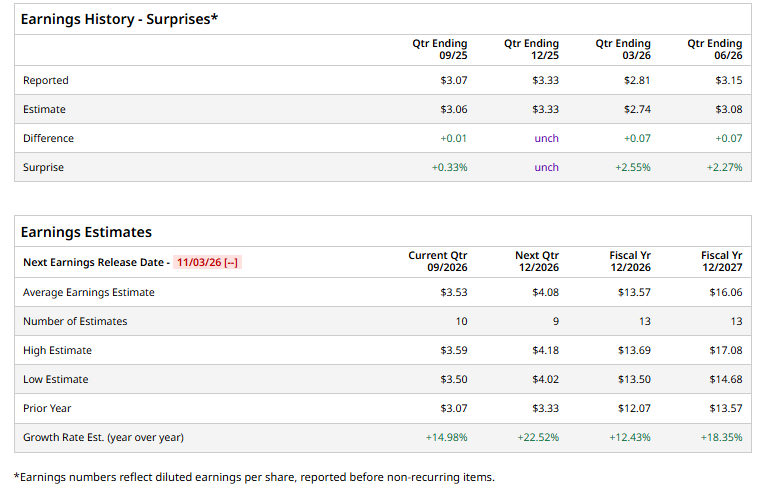
ETN is set to report its Q3 earnings shortly. Ahead of the release, analysts expect the company to report diluted EPS of $3.53, up 15% from $3.07 in the year-ago quarter. Additionally, ETN has met or exceeded Wall Street’s EPS estimates in each of the past four quarters.
For fiscal 2026, analysts expect ETN to report EPS of $13.57, up 12.4% from $12.07 in fiscal 2025. EPS is projected to grow another 18.4% year over year to $16.06 in fiscal 2027.
ETN stock has gained 5.4% over the past 52 weeks, underperforming the S&P 500 Index ($SPX), which returned 16.1%, and the State Street Industrial Select Sector SPDR ETF (XLI), which gained 10% over the same period.
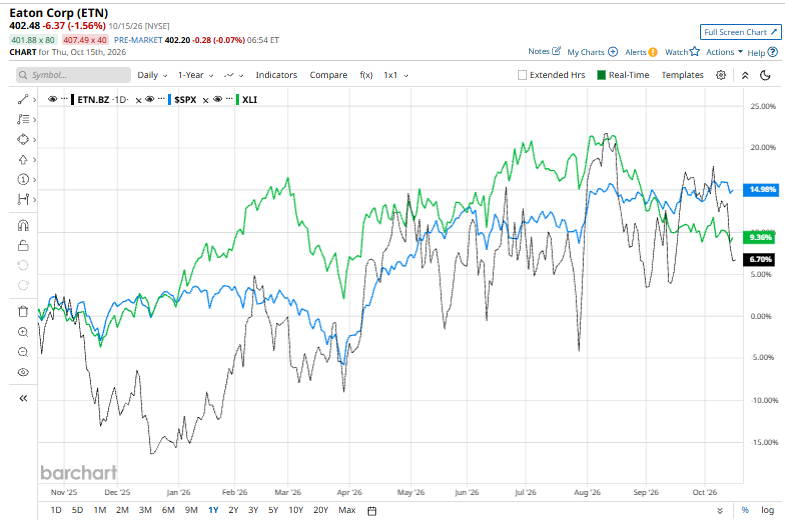
Despite its grim price performance over the past year, Eaton’s growth outlook remains supported by rising demand for digitalization, electrification, the energy transition, and infrastructure spending. Strong orders and record backlogs, particularly in data centers, are expected to drive long-term EPS growth through revenue expansion, margin improvement, and increased production capacity.
More recently, on Oct. 1, Eaton expanded its manufacturing facility in Schrems, Austria, adding 5,000 square meters of production space to meet rising European demand for electrical protection and power management solutions. The investment increases regional production capacity, strengthens supply chain resilience, and incorporates advanced automation and digital technologies, positioning Eaton to capitalize on growing demand for electrification and digitalization.
Analysts remain bullish on ETN, with the stock carrying a consensus “Strong Buy” rating. Of the 23 analysts covering the stock, 18 recommend a “Strong Buy,” two rate it a “Moderate Buy,” and three recommend a “Hold.” Meanwhile, the average price target of $497.82 implies potential upside of 23.7% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.