


Exploring 3 Undervalued Small Caps With Insider Action Across Regions
Over the last 7 days, the United States market has remained flat, yet it has seen a notable 14% increase over the past year with earnings forecasted to grow by 17% annually. In such a dynamic environment, identifying small-cap stocks that are potentially undervalued and exhibit insider activity can offer intriguing opportunities for investors seeking to capitalize on growth potential across various regions.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.8x | 0.5x | 28.27% | ★★★★★★ |
| Financial Institutions | 9.5x | 3.2x | 25.78% | ★★★★★☆ |
| Surgery Partners | NA | 0.6x | 23.64% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.0x | 34.77% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.7x | 2.4x | 27.99% | ★★★★☆☆ |
| Union Bankshares | 9.3x | 2.0x | 46.35% | ★★★★☆☆ |
| Tilray Brands | NA | 0.5x | 4.91% | ★★★★☆☆ |
| German American Bancorp | 13.1x | 4.9x | 25.86% | ★★★☆☆☆ |
| Shore Bancshares | 11.4x | 3.3x | 36.54% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 8.17% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
QNB (QNBC)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: QNB operates as a community banking institution with a focus on providing financial services, and it has a market capitalization of $0.11 billion.
Operations: The company generates revenue primarily from community banking, with recent quarterly revenue reaching $65.59 million. Operating expenses are a significant component of the cost structure, with general and administrative expenses consistently forming a large portion. The net income margin showed fluctuations but was recorded at 20.44% in the latest period analyzed.
PE: 21.2x
QNB, a smaller company in the U.S., has shown potential despite recent challenges. Earnings are projected to grow 93% annually, suggesting future growth. However, past shareholder dilution and decreased net income from US$3.88 million to US$3.02 million in Q2 2026 present concerns. Insider confidence is evident with recent share purchases, while its addition to the NASDAQ Composite Index highlights market recognition. The declared quarterly dividend of US$0.39 per share signals steady returns for investors amid these dynamics.
- Take a closer look at QNB's potential here in our valuation report.
Gain insights into QNB's past trends and performance with our Past report.
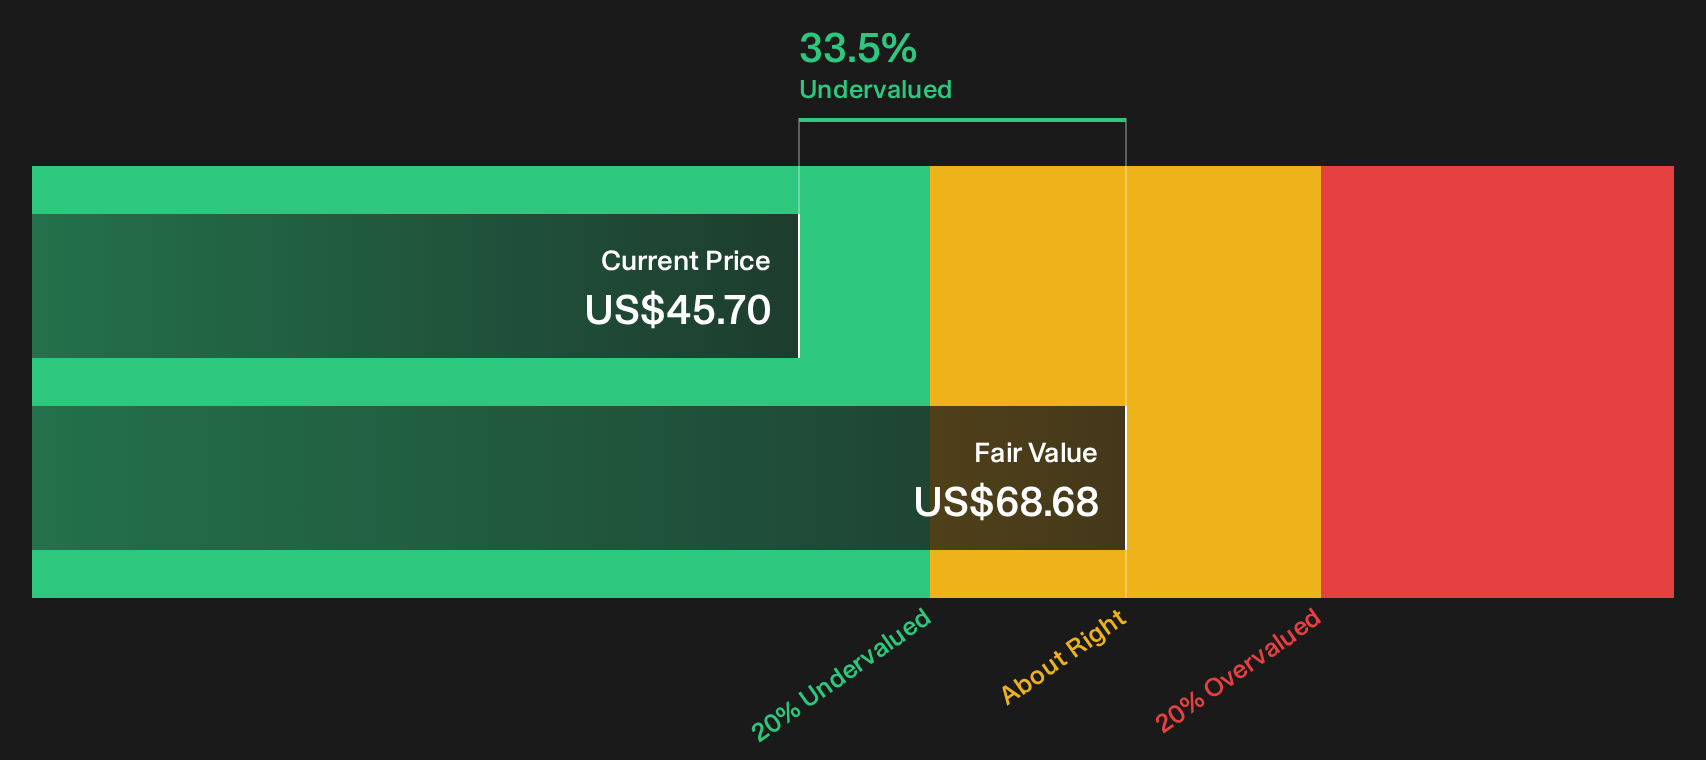
Grocery Outlet Holding (GO)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Grocery Outlet Holding operates a chain of discount grocery stores, offering brand-name products at reduced prices, with a market capitalization of approximately $3.09 billion.
Operations: The company generates revenue primarily through its retail grocery stores, with the latest reported revenue at $4.74 billion. The cost of goods sold (COGS) is a significant expense, amounting to $3.32 billion in the most recent period, impacting overall profitability. Notably, the gross profit margin has shown fluctuations and was recorded at 29.99% in the latest financial data provided.
PE: -3.4x
Grocery Outlet Holding, a smaller company in the retail sector, recently reported second-quarter sales of US$1.19 billion, slightly up from last year. Despite a net loss of US$174.7 million over six months, they raised their annual sales guidance to US$4.70-$4.72 billion for 2026. Insider confidence is evident as Jason Potter purchased 286,097 shares worth approximately US$1.69 million between April and July 2026, reflecting potential belief in future growth despite current financial challenges and reliance on external funding sources.
- Get an in-depth perspective on Grocery Outlet Holding's performance by reading our valuation report here.
Assess Grocery Outlet Holding's past performance with our detailed historical performance reports.
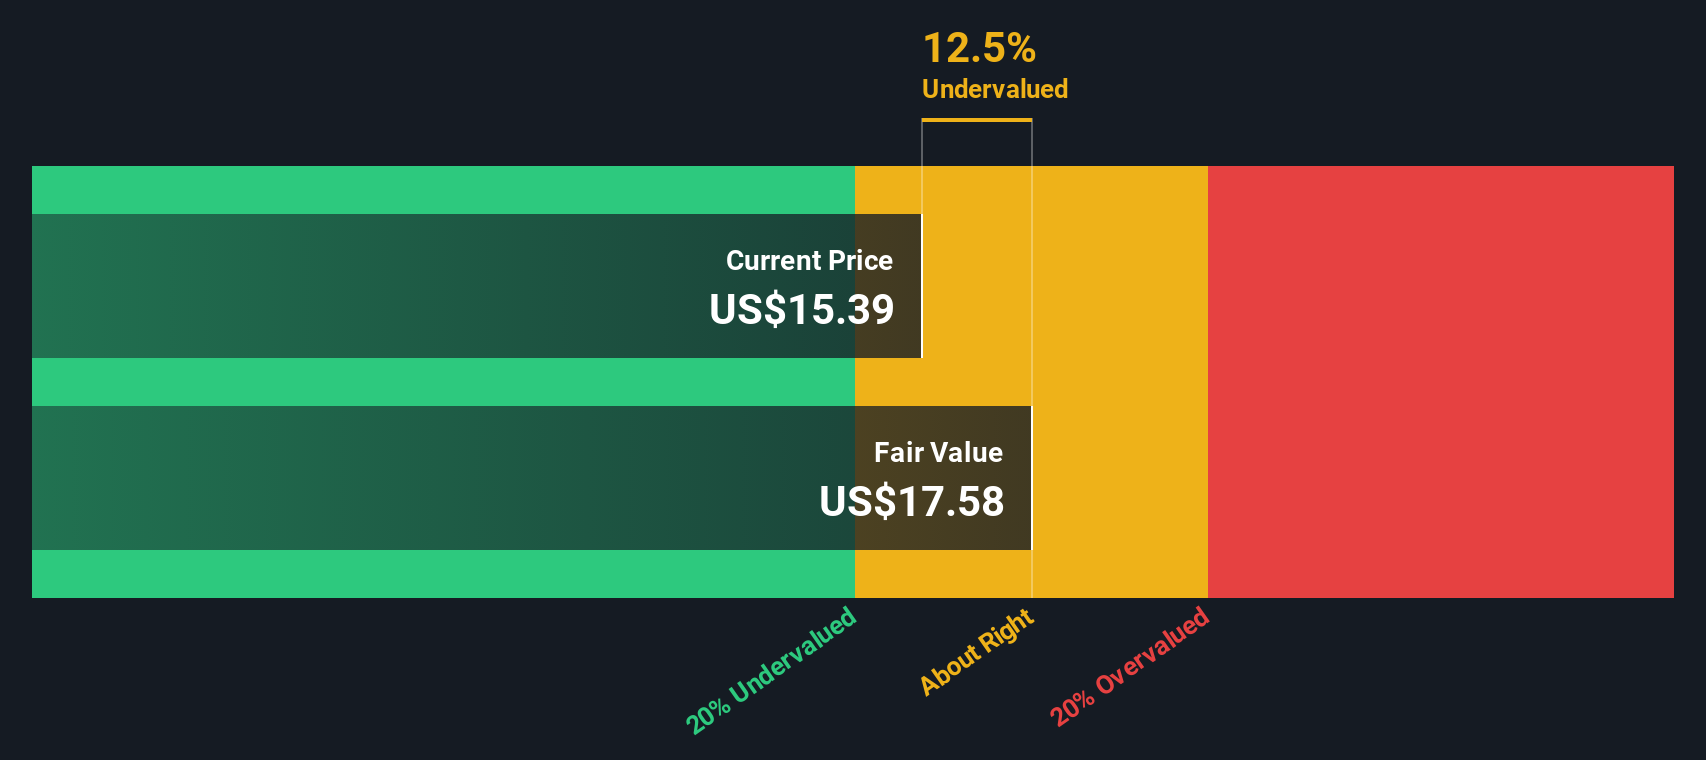
Huntsman (HUN)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Huntsman is a global manufacturer and marketer of differentiated and specialty chemicals, with operations spanning polyurethanes, advanced materials, and performance products, holding a market cap of approximately $5.86 billion.
Operations: Huntsman's revenue is primarily generated from Polyurethanes, Advanced Materials, and Performance Products. The company's cost of goods sold (COGS) significantly impacts its gross profit margin, which was 14.85% as of the latest period ending in September 2023. Operating expenses include research and development (R&D) and general & administrative costs, with R&D expenses consistently around $100 million per quarter recently.
PE: -8.9x
Huntsman, a smaller player in the U.S. market, has caught attention with its insider confidence as Chairman Peter Huntsman acquired 100,000 shares for US$981,000 in August 2026. Despite grappling with a net loss of US$6 million for Q2 2026 and debt not fully covered by operating cash flow, the company forecasts earnings growth of over 113% annually. The firm completed a significant share buyback program worth US$1.45 billion since November 2021 and declared a dividend of US$0.0875 per share payable on September 30, highlighting ongoing shareholder returns amidst financial challenges.
- Click to explore a detailed breakdown of our findings in Huntsman's valuation report.
Examine Huntsman's past performance report to understand how it has performed in the past.
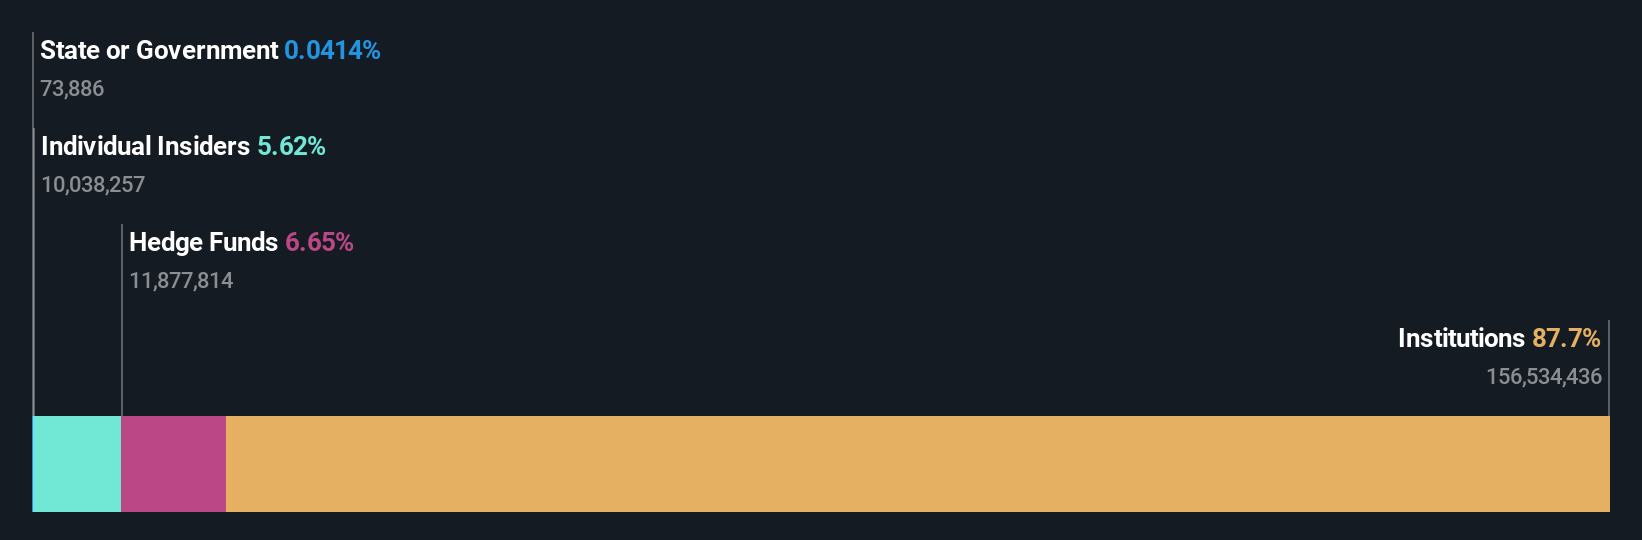
Where To Now?
- Navigate through the entire inventory of 65 Undervalued US Small Caps With Insider Buying here.
- Invested in any of these stocks? Simplify your portfolio management with Simply Wall St and stay ahead with our alerts for any critical updates on your stocks.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com