


3 Stocks That May Be Trading At A Discount Of Up To 42.9%
In the last week, the United States market has stayed flat, but over the past 12 months it has risen by 14%, with earnings forecasted to grow by 17% annually. In this environment, identifying stocks that may be trading below their intrinsic value can present opportunities for investors seeking to capitalize on potential growth.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $63.01 | $123.56 | 49% |
| Sociedad Química y Minera de Chile (SQM) | $60.47 | $118.82 | 49.1% |
| Pegasystems (PEGA) | $35.95 | $71.50 | 49.7% |
| KeyCorp (KEY) | $19.94 | $39.51 | 49.5% |
| Insteel Industries (IIIN) | $29.67 | $57.55 | 48.4% |
| EOG Resources (EOG) | $152.62 | $296.04 | 48.4% |
| Civista Bancshares (CIVB) | $26.85 | $53.30 | 49.6% |
| Best Buy (BBY) | $94.17 | $186.82 | 49.6% |
| Artisan Partners Asset Management (APAM) | $32.76 | $65.13 | 49.7% |
| Addus HomeCare (ADUS) | $116.49 | $226.18 | 48.5% |
Here we highlight a subset of our preferred stocks from the screener.
Autodesk (ADSK)
Overview: Autodesk, Inc. provides 3D design, engineering, and entertainment technology solutions globally and has a market cap of approximately $48.31 billion.
Operations: The company's revenue primarily comes from its CAD / CAM Software segment, which generated $7.79 billion.
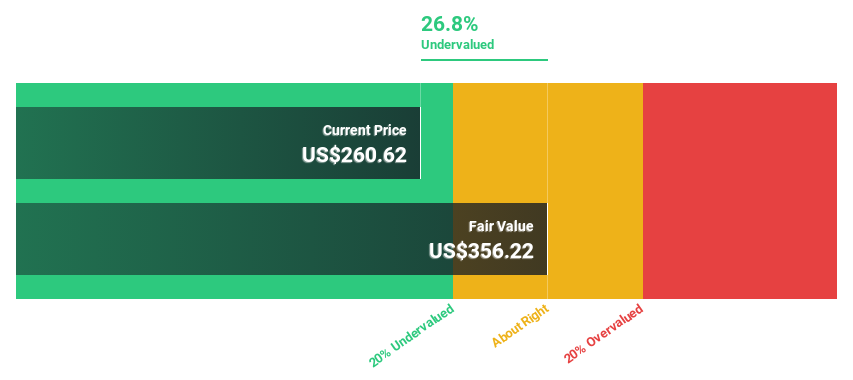
Estimated Discount To Fair Value: 28.8%
Autodesk is trading at US$245.16, significantly below its estimated future cash flow value of US$344.36, suggesting it may be undervalued based on cash flows. Recent earnings showed strong growth with a net income increase to US$492 million from US$313 million year-over-year, while revenue rose to US$2.05 billion from US$1.76 billion. Despite slower forecasted revenue and earnings growth compared to the market, Autodesk's return on equity is projected to remain very high at 58.4%.
- Upon reviewing our latest growth report, Autodesk's projected financial performance appears quite optimistic.
- Unlock comprehensive insights into our analysis of Autodesk stock in this financial health report.
Lear (LEA)
Overview: Lear Corporation designs, develops, engineers, manufactures, assembles, and supplies automotive seating and electrical distribution systems for original equipment manufacturers across multiple continents with a market cap of approximately $5.89 billion.
Operations: The company's revenue segments consist of $17.69 billion from Seating and $6.29 billion from e-Systems.
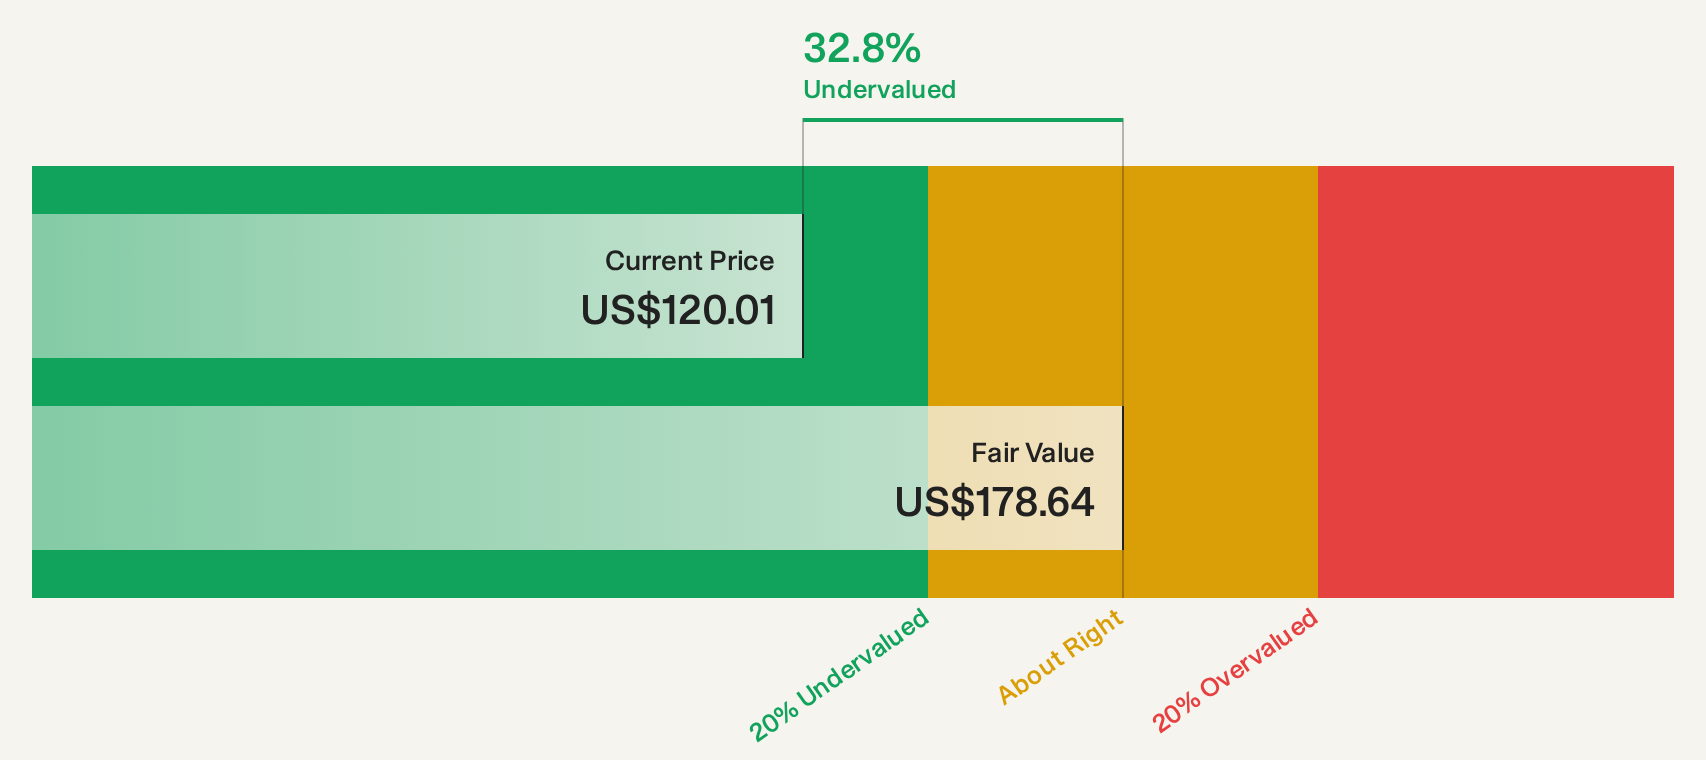
Estimated Discount To Fair Value: 32.1%
Lear is trading at US$121.49, below its estimated future cash flow value of US$178.85, indicating it may be undervalued based on cash flows. The company recently increased its equity buyback plan to US$1.5 billion and extended it through 2029, which could enhance shareholder value. While earnings are forecast to grow at 11.35% annually, slower than the market average, Lear's trading price remains attractive relative to peers and industry standards.
- The analysis detailed in our Lear growth report hints at robust future financial performance.
- Dive into the specifics of Lear here with our thorough financial health report.
UiPath (PATH)
Overview: UiPath, Inc. is a company that offers a comprehensive automation platform with various robotic process automation (RPA) solutions across multiple countries, and it has a market capitalization of approximately $6.81 billion.
Operations: The company's revenue is primarily derived from its Software & Programming segment, which totals $1.72 billion.
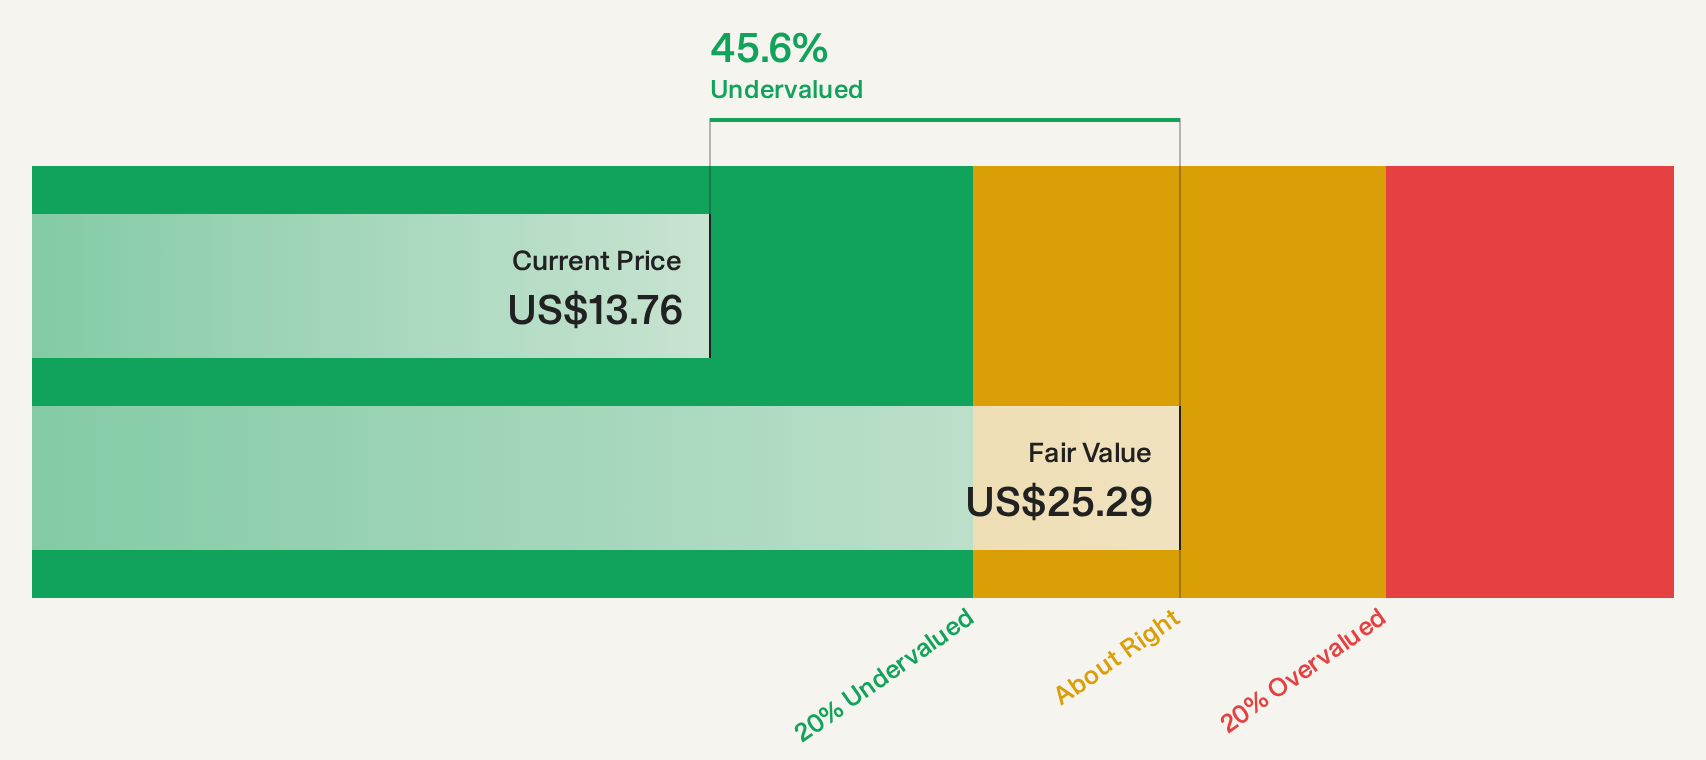
Estimated Discount To Fair Value: 42.9%
UiPath is trading at US$13.71, significantly below its estimated future cash flow value of US$24.02, highlighting potential undervaluation. Recent strategic partnerships with Oracle and Snowflake enhance its automation capabilities, potentially bolstering operational efficiency and client reach. Despite a slower forecasted revenue growth of 7.9% annually compared to the market average, the company's current valuation offers a compelling opportunity relative to industry peers based on discounted cash flow analysis.
- Our growth report here indicates UiPath may be poised for an improving outlook.
- Click to explore a detailed breakdown of our findings in UiPath's balance sheet health report.
Taking Advantage
- Unlock more gems! Our Undervalued US Stocks Based On Cash Flows screener has unearthed 97 more companies for you to explore.Click here to unveil our expertly curated list of 100 Undervalued US Stocks Based On Cash Flows.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com