


What You Need To Know Ahead of Henry Schein's Earnings Release
Melville, New York-based Henry Schein, Inc. (HSIC) provides health care products and services to office-based dental and medical practitioners and alternate sites of care worldwide. The company has a market capitalization of $9.5 billion and operates through Global Distribution and Value-Added Services, Global Specialty Products, and Global Technology segments. HSIC is expected to release its Q3 2026 earnings soon.
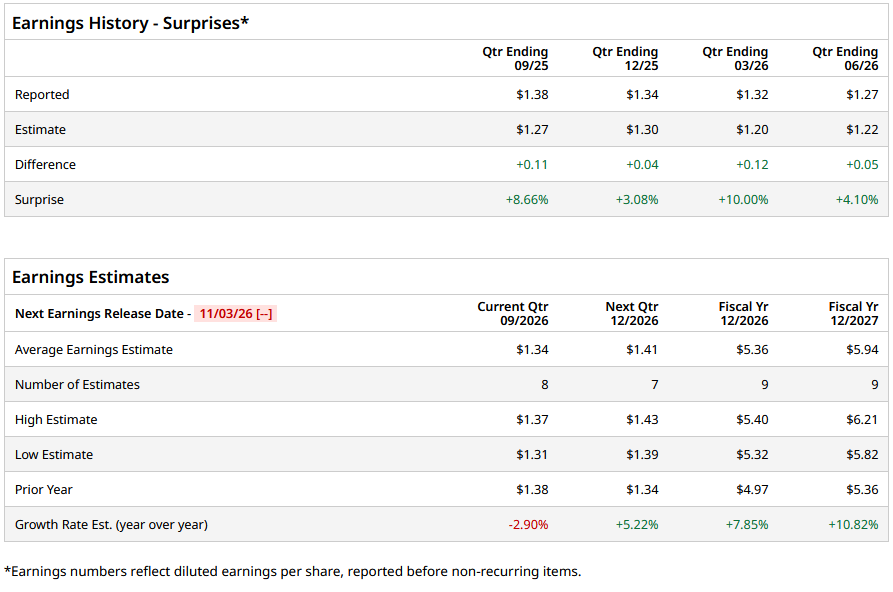
Ahead of the event, analysts expect the company’s EPS to be $1.34 on a diluted basis, down 2.9% from $1.38 in the year-ago quarter. The company has exceeded Wall Street’s EPS estimates in each of its last four quarters, which is impressive.
For fiscal 2026, analysts project the company’s EPS to be $5.36, up 7.9% from $4.97 in fiscal 2025. Moreover, its EPS is expected to rise by roughly 10.8% year over year (YoY) to $5.94 in fiscal 2027.
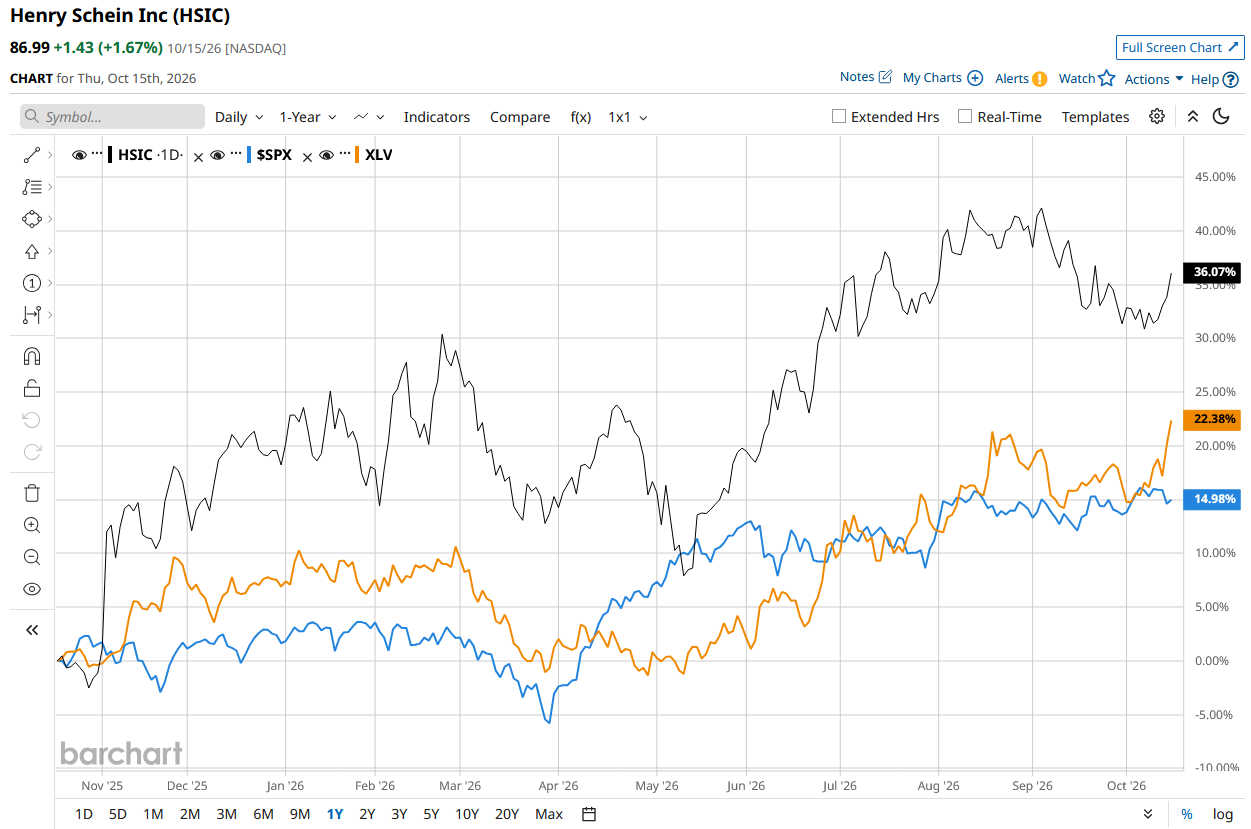
HSIC stock has surged 37.5% over the past 52 weeks, outperforming the S&P 500 Index’s ($SPX) 16.1% rise and the State Street Healthcare Select Sector SPDR ETF’s (XLV) 24.3% rise during the same time frame.
On Aug. 4, HSIC stock rose 3% following the release of its better-than-expected Q2 2026 earnings. The company’s revenue for the quarter amounted to $3.5 billion, surpassing the Street’s estimates. Moreover, its adjusted EPS came in at $1.27, also topping the consensus estimates. The company’s top-line growth was supported by a 4.6% increase in organic revenue, also indicating internal sales growth. HSIC also lifted its 2026 outlook for adjusted earnings per share to a midpoint of $5.34, reinforcing confidence in the company's operational performance.
Analysts are somewhat optimistic about HSIC, with the stock having a “Moderate Buy” rating overall. Among the 17 analysts covering the stock, eight are recommending a “Strong Buy,” eight suggest a “Hold,” and one suggests a “Strong Sell.” HSIC’s average analyst price target is $96.31, indicating an upside of 10.7% from the current level.
On the date of publication, Aritra Gangopadhyay did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.