


Turning Point Brands (TPB) Jumped, So What Is Driving Attention Now?
Turning Point Brands (TPB) has drawn investor interest after a recent share price move, with the stock closing at US$60.31. The shift comes against a backdrop of contrasting short and longer term returns.
Recent trading tells a mixed story. Turning Point Brands has seen a 1-day share price return of 4.52% and a 7-day share price return of 5.73%. However, the 30-day share price return is down 13.87% and the year-to-date share price return is down 45.29%, while the 3-year total shareholder return of 174.36% still reflects a much stronger longer-term journey than the last few months suggest.
Compare Turning Point Brands' swing in returns with handpicked value ideas by scanning the 33 high quality undervalued stocks that share strong cash flows and balance sheets.
Turning Point Brands now trades at US$60.31 while analyst targets sit at US$118.50, and an intrinsic value estimate signals a smaller gap. Does fair value lean closer to the market quote or the higher range of estimates?
Most Popular Narrative: 49.1% Undervalued
The most followed narrative on Turning Point Brands sets a fair value of $118.50 against the last close at $60.31. This frames a large valuation gap that depends on how Modern Oral pouches and margins develop.
Strong growth in the Modern Oral nicotine pouch segment, with FRE and ALP net sales reaching $68 million and representing 48% of total revenue in Q2 2026 after very large year-over-year growth, keeps Turning Point Brands leveraged to a rising share of nicotine consumption and can continue to reweight the business mix toward higher revenue and gross margin.
See why 7 investors see Turning Point Brands as 49% undervalued.
Result: Fair Value of $118.50 (UNDERVALUED)
Still, Turning Point Brands leans heavily on Modern Oral spending, and delays or extra costs in bringing Louisville pouch production onshore could unsettle that bullish fair value story.
Find out about the key risks to this Turning Point Brands narrative.
Another View: What The P/E Says About Turning Point Brands
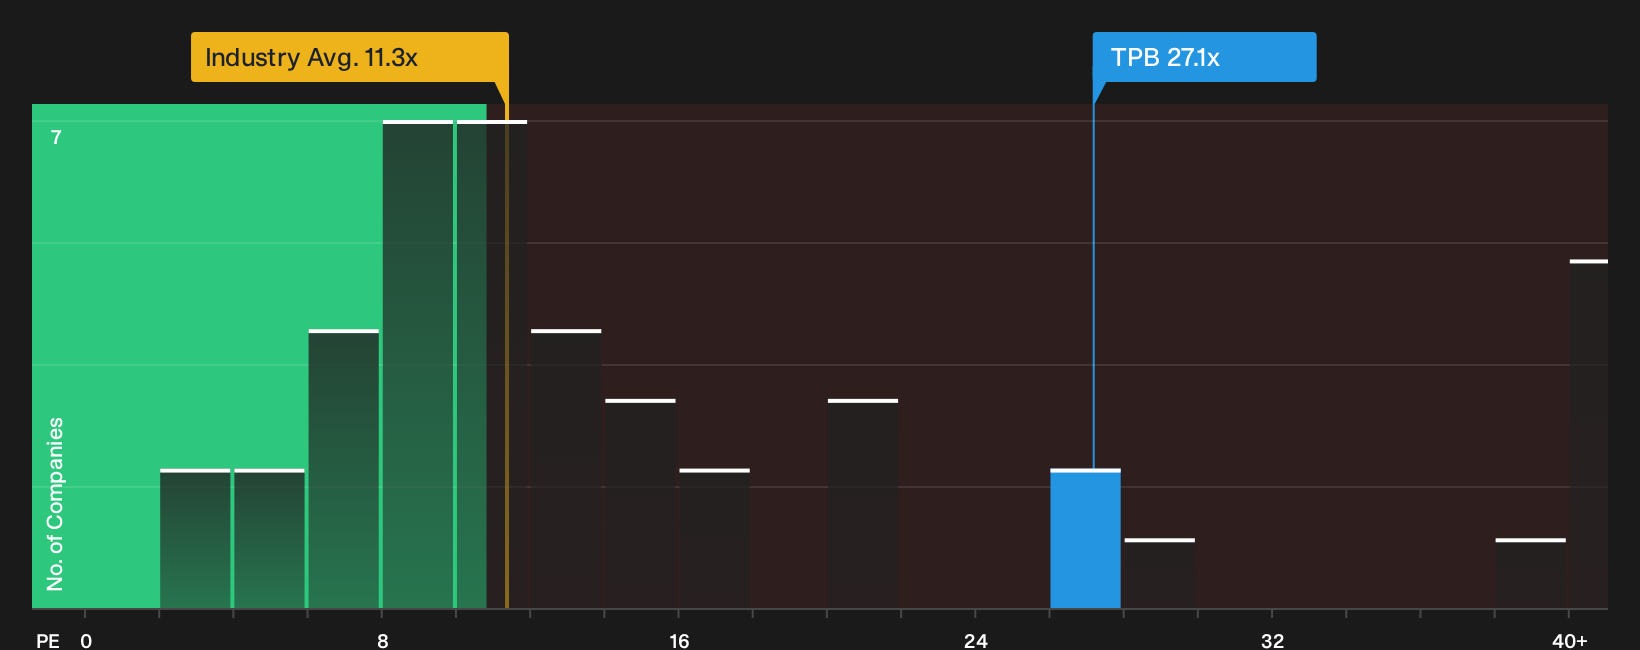
There is a very different signal when you look at Turning Point Brands through its P/E ratio rather than analyst fair value. The stock trades on 27.1x earnings, which is higher than the global Tobacco industry at 11.3x and below its peer group at 33.3x, while the fair ratio sits even higher at 34.4x. That combination points to a share that already prices in more optimism than the broader sector, yet could still rerate if the market eventually leans toward the fair ratio. The question is how comfortable you are with paying that kind of multiple for this earnings profile.
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Turning Point Brands is split, with clear concerns and some optimism pulling in opposite directions. Move quickly and test the evidence yourself against your own expectations. To see both sides laid out in one place, review the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Turning Point Brands?
If Turning Point Brands has your attention, do not stop there. Broaden your watchlist with fresh ideas that match your risk tolerance and return goals.
- Spot potential value candidates early by scanning the 33 high quality undervalued stocks that combine solid cash flows with disciplined balance sheets.
- Strengthen your income stream by reviewing the 8 dividend fortresses that focus on higher yields backed by financial resilience.
- Stack the odds toward resilience by filtering for the 32 resilient stocks with low risk scores that screen for lower risk scores and steadier profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com