


Missed Herbalife's Run? What Holders Had To Believe
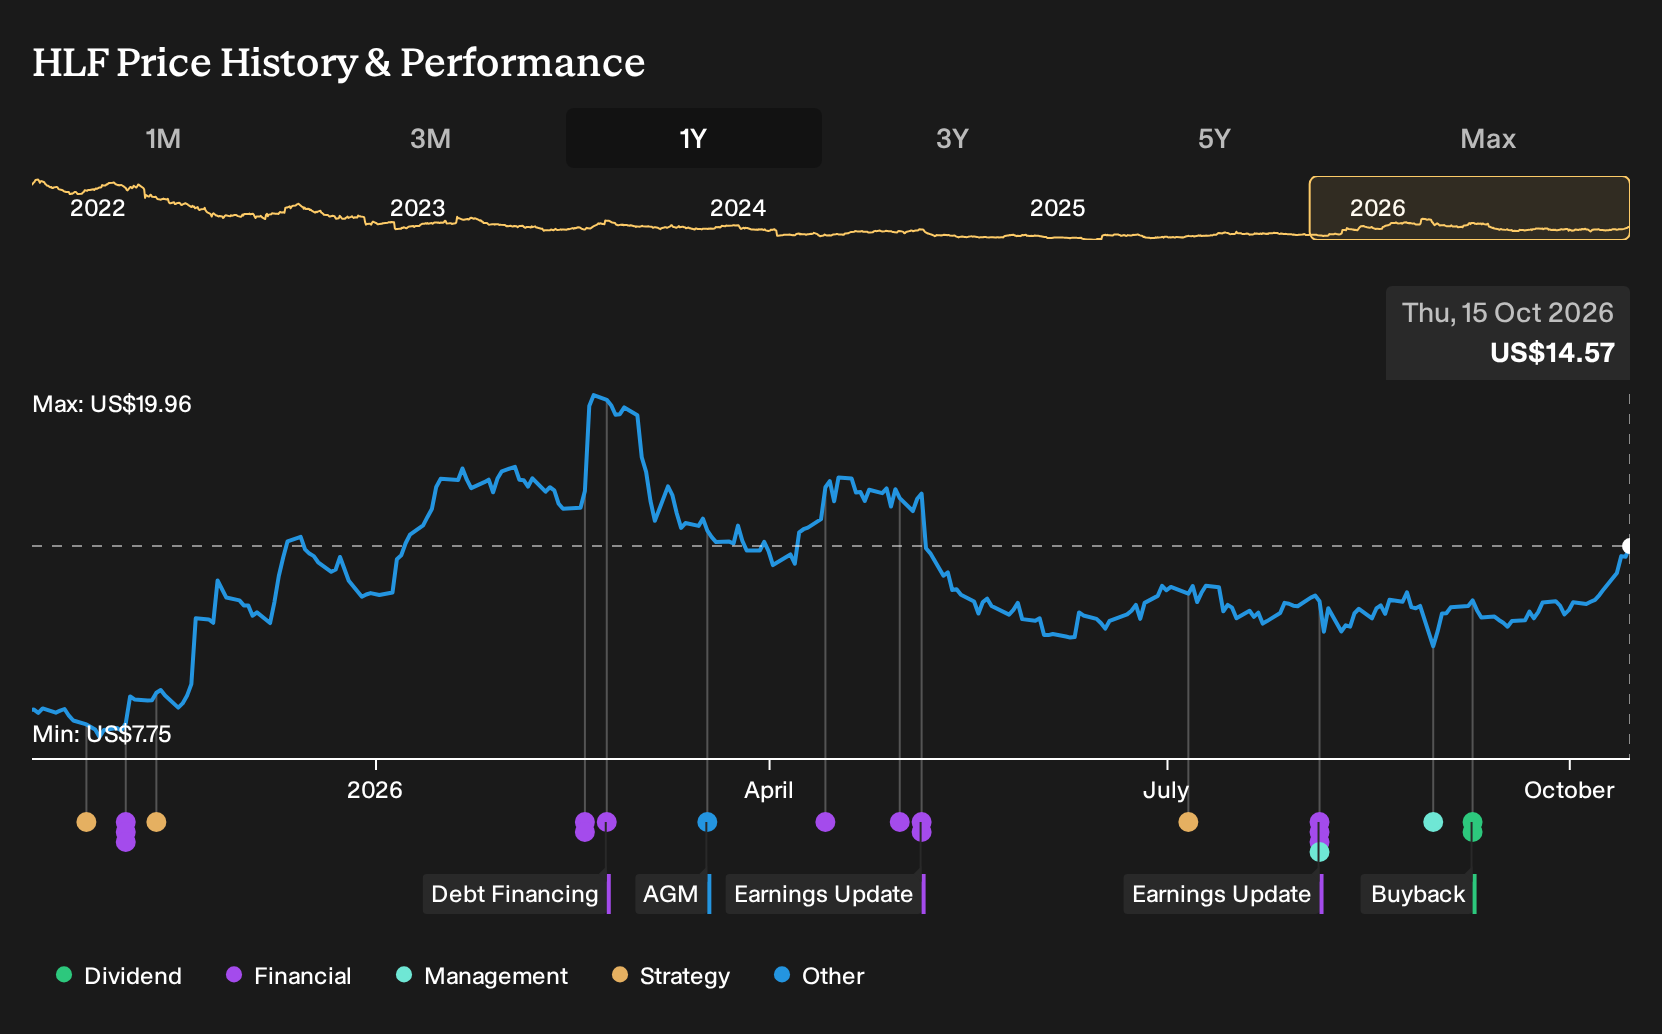
Herbalife’s recent $1.45b refinancing package, which stretches debt maturities and trims annual cash interest, gave the balance sheet a different profile by late 2026. Investors who held Herbalife over the past year are up 69.2%, including dividends. If you were deciding back on 15 October 2025 whether to buy, you had to weigh bullish talk of digital nutrition against worries over regulation and leverage. Which of those threads looked stronger before any of this later news arrived?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Herbalife has already moved. See which of 33 high quality undervalued stocks still trade below our estimates.
The Two Herbalife Stories Investors Had To Balance
The shares cost US$8.73 at the start of the period, so you were deciding whether Herbalife’s future looked underpriced or fairly cautious already.
The bullish narrative put fair value at US$11, framed around digital platforms and personalized nutrition. It leaned on data driven distributor tools and AI supported products that were expected to help revitalise the global salesforce.
The bearish view pointed to a fair value of US$7 and focused on regulatory strain and debt. It highlighted growing investigations into multi level marketing and health claims as a key threat to revenue and profitability.
What The Herbalife Results Actually Tested
The clearest new fact was Herbalife’s Q2 2026 report, where revenue of US$1.33b stood above US$1.26b a year earlier, which helped the bullish demand story. In the same quarter, the company reported a net loss of US$26.3 million compared with a US$49.3 million profit a year before, and net margin went from a positive 3.9% to negative 2.0%. That profitability hit meant the evidence cut both ways.
The key lesson is simple. When a growth pitch leans on digital nutrition and higher engagement, it is important to check whether rising sales come with stable or improving net margin, not just top line momentum.
What Herbalife's Run Now Asks You To Believe
Herbalife trades at US$14.57 today, well above where this Narrative’s Fair Value sits according to its own model. That gap reflects concern that the share price already bakes in smooth execution on personalized nutrition, margin rebuild and balance sheet repair.
The Narrative highlights execution risk around India mix, tax drag, technology spend and leadership change. Anyone paying today’s price is effectively assuming those pressures do not derail cash generation or compress margins in a way that undercuts the current optimism.
"The primary requirement for success is that Herbalife executes its personalized, data-enabled nutrition and technology programs while managing emerging market mix shifts, India GST headwinds, and leadership transitions without eroding margins or cash generation."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Herbalife And A Different Beauty Angle
Herbalife puts nutrition, coaching and wellness communities in front of customers. Your attention is on shakes and supplements.
Step sideways and you find another business chasing a related habit. It wants those same consumers when they reach for premium creams and fragrance.
Its plan leans on reshaping costs, lifting cash generation and using AI tools to sharpen digital marketing and product feedback.
The aim is simple. Turn more high end skincare and scent demand into durable profit, without dulling the brands that make people trade up.
That argument has a Narrative and a number behind it. → See the company one Narrative values 18% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com