


Is Dollar General (DG) Fully Priced As Its Breakout Tests Valuation?
Dollar General (DG) shares recently moved through a technical resistance level, drawing fresh attention from traders who track chart patterns and short-term price momentum in large consumer retailers.
Recent moves have come after a run of short-term gains, with a 7.74% 7 day share price return and a 7.37% 30 day share price return. However, Dollar General still shows a modest year to date share price decline of 2.14%, while the 1 year total shareholder return of 31.37% points to momentum that has been building over a longer stretch.
Scan how Dollar General’s breakout-style move compares with other retailers showing strong momentum and fundamentals by running the curated 33 high quality undervalued stocks screen next to this chart action.
Dollar General now trades around US$133.89 after this breakout, so the real tension for you is simple: Does that recent strength still leave enough upside to justify the risk, once the valuation work starts to speak?
Most Popular Narrative: 25% Overvalued
On the most followed narrative, Dollar General’s fair value sits at about $107.04, which is well below the recent $133.89 close. The current breakout is running ahead of that intrinsic estimate and puts more weight on how the next few years of execution play out.
The numbers imply that Dollar General’s share price already prices in sustained same store sales growth, continued margin expansion, and successful execution of remodel, digital, and media initiatives that may leave limited room for disappointment.
See why 3 investors see Dollar General as 25% overvalued.
Result: Fair Value of $107.04 (OVERVALUED)
Still, a few things could upset this overvalued story, including Dollar General sustaining current traffic trends and margin gains, or media and efficiency projects lifting earnings further.
Find out about the key risks to this Dollar General narrative.
Another View: Dollar General on Earnings Multiples
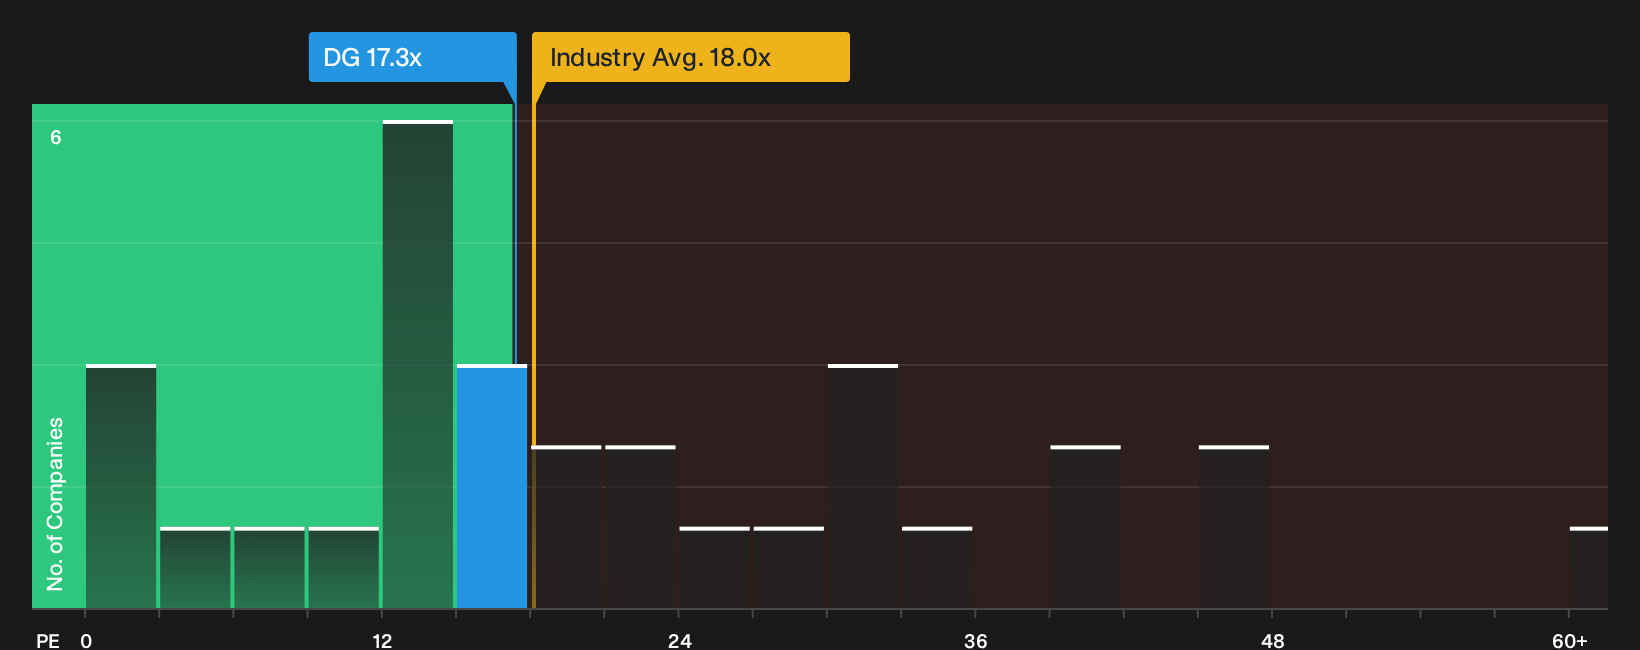
The bearish fair value of US$107.04 leans on cautious long term forecasts. A different lens comes from today’s P/E of 17.3x, which is lower than both the peer average of 21.3x and the broader US Consumer Retailing industry at 18x, and below an estimated fair ratio of 22.8x.
That gap suggests the market prices Dollar General at a discount to what similar retailers and the fair ratio imply, which could either reflect lingering concern about execution or leave room for sentiment to shift. Which story do you think that discount is really telling?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment across these valuation angles on Dollar General is mixed. Act while the data is fresh and pressure test the narrative against your own expectations. To see the specific positives supporting the optimistic case, review the 5 key rewards.
Looking for more Dollar General style ideas?
Do not stop with Dollar General. Use this breakout as a trigger to refresh your watchlist with new companies that match your risk, income, and quality preferences.
- Target fresh upside potential by scanning a curated pool of quality candidates on the 20 high quality undiscovered gems.
- Protect your downside first by filtering for resilient businesses through the 32 resilient stocks with low risk scores.
- Build a core income stream by focusing on companies in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com