


How Strong Half Year Earnings Will Impact Bytes Technology Group Stock (LSE:BYIT)
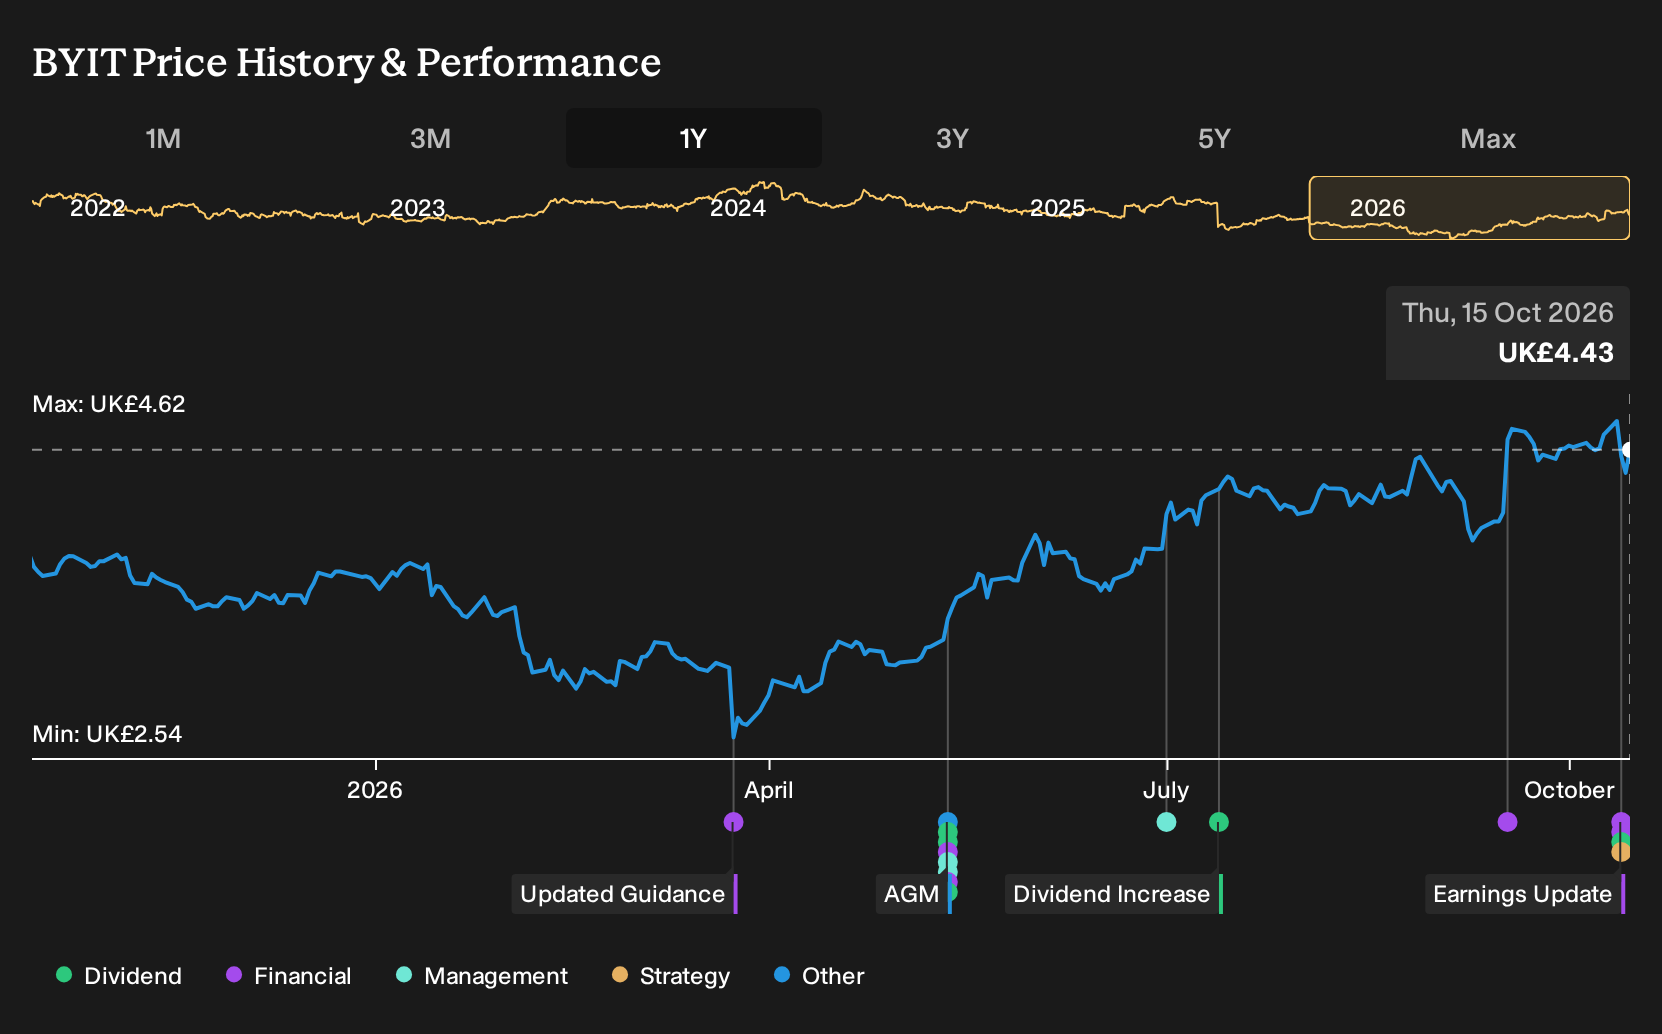
- Bytes Technology Group reported half year sales of £128.27 million and net income of £29.88 million, confirmed upgraded FY27 guidance, raised its interim dividend to 3.3 pence per share, and completed a £25 million buyback of 6,466,525 shares that represented 2.74% of its share capital.
- The combination of higher earnings per share, a larger cash payout and a reduced share count highlights management’s focus on returning capital while keeping growth guidance intact.
- The next area of focus is how Bytes Technology Group's reiterated upgraded guidance shapes the existing investment narrative around AI, cloud and cybersecurity.
Bytes Technology Group Investment Narrative Recap
To stay on board with Bytes Technology Group, you need to believe the business can keep turning its software, cloud, AI and security focus into resilient gross profit, even as customers reassess budgets after the U.K. election. The recent half year figures show revenue and earnings per share progression, so the upgraded FY27 guidance remains the key near term reference point.
The short term swing factor is whether public and corporate clients keep committing to cloud and cybersecurity projects at the pace implied by that guidance. The biggest risk still looks operational. Heavy hiring, new systems and regional expansion need to convert into profitable work or margin pressure can persist.
The most relevant fresh datapoint is the reiterated upgraded FY27 outlook. Management still guides to low to mid teens gross profit growth and low to mid single digit operating profit growth, anchored by demand for AI aligned, cloud and security offerings. For investors, that guidance frames what “good execution” looks like over the next few reporting periods.
If Bytes Technology Group keeps renewing and upselling large public sector contracts while bedding in its new marketplace portal and internal platforms, the earnings profile implied by that outlook stays in play. Any slowdown in renewals, misstep on Microsoft rebate alignment or shift toward lower margin public work would quickly test that guidance and the current investment thesis.
Bytes Technology Group's current analyst narrative points to forecast revenue of £294.7 million and projected earnings of £61.0 million by 2029. That profile is based on an assumption of revenue growth of about 10.1% a year and requires an earnings increase of roughly £9.7 million from current earnings of £51.3 million.
Discover how Bytes Technology Group's fair value aligns with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts frame Bytes Technology Group as a cash machine, with the key catalyst being share count shrinking over time. Before this update, they were pencilling in about £338.1 million of revenue and £67.2 million of earnings by 2029, far above consensus. You can treat today’s buyback completion and dividend increase as fresh evidence that might reshape those projections, then compare that view with more cautious forecasts to see which story you find more convincing.
Explore 3 other Bytes Technology Group fair value estimates, including one that suggests there could be as much as 24% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bytes Technology Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bytes Technology Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bytes Technology Group's overall financial health at a glance.
Looking for more investment ideas beyond Bytes Technology Group?
If the Bytes Technology Group story has sharpened your focus on quality and capital returns, you can broaden the search by using the Simply Wall St Screener to line up other stocks that match the kind of traits you want in a portfolio.
- For potential mispriced opportunities with solid fundamentals, scan our curated set of 9 high quality undervalued stocks that already clear quality and balance sheet checks.
- If capital preservation matters to you, filter for 4 resilient stocks with low risk scores that pair steadier risk scores with fundamentally sound profiles.
- When you want future growth without paying up for widely followed tickers, work through the 5 high quality undiscovered gems that still fly under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com