


What Interroll Investors Missed Before The Fall
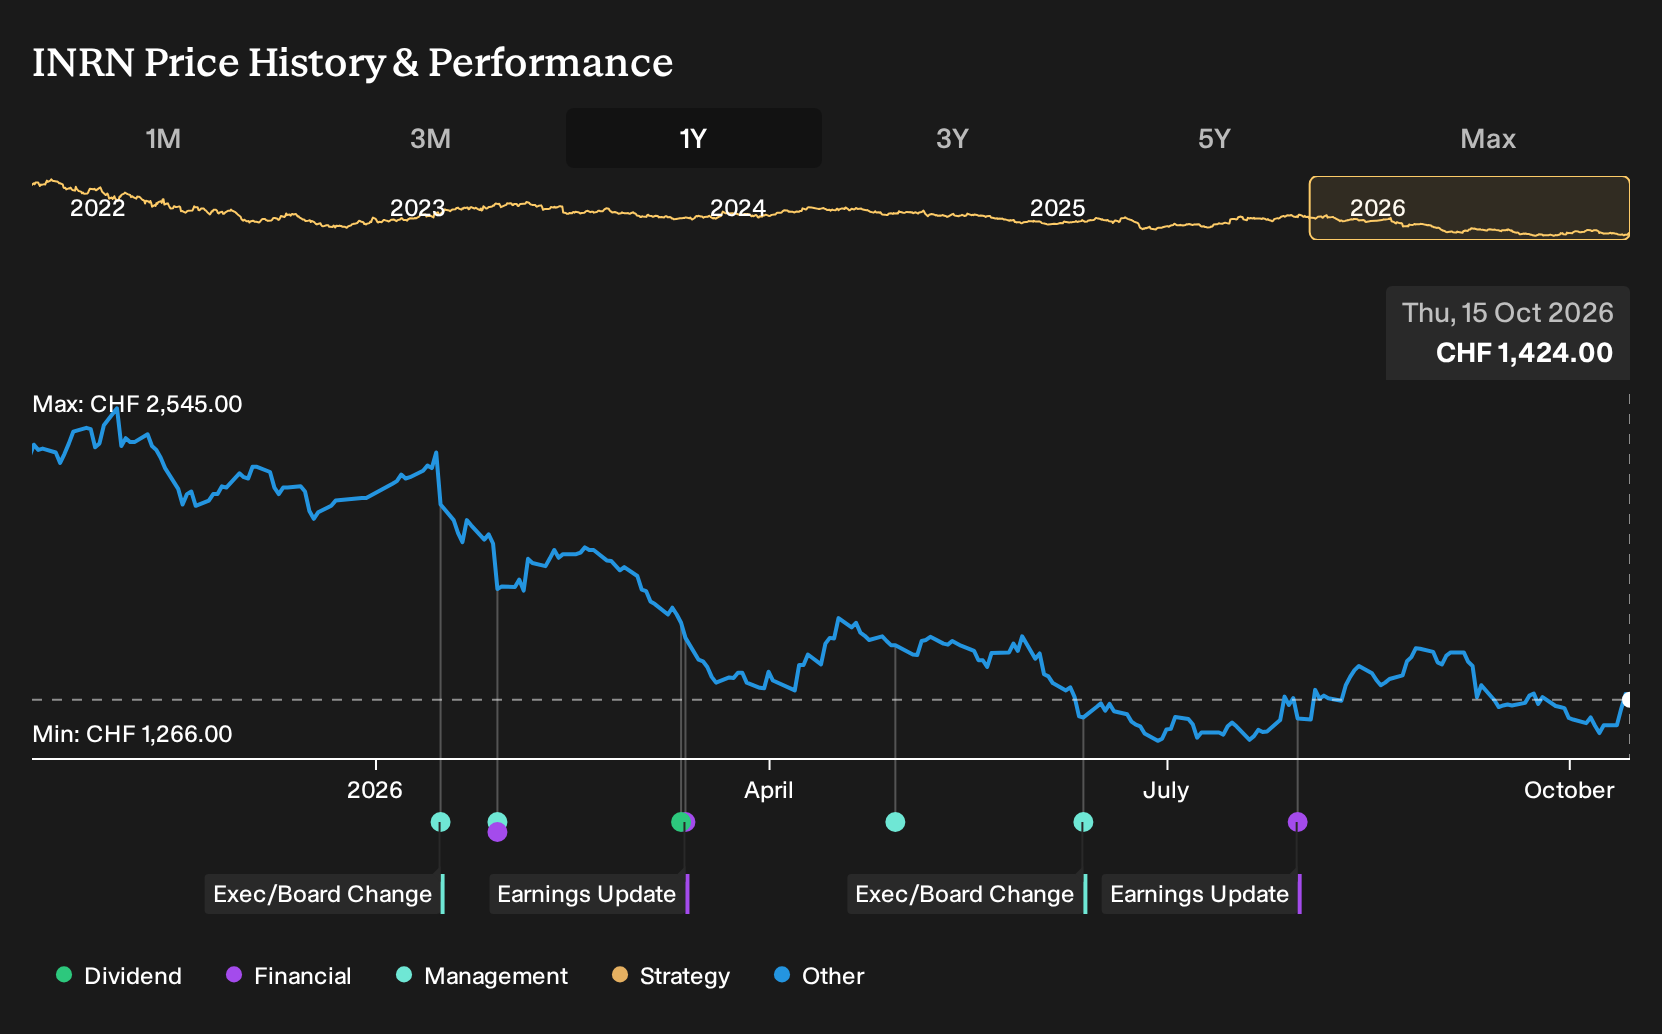
If you had looked at Interroll in October 2025 and decided automation and e-commerce exposure made it a straightforward hold, the outcome would have been painful. Holding Interroll over the past year would have meant a 38.9% loss, including dividends. With that result in hand today, the real question is which assumption from the bullish or bearish cases on record then most clearly challenged the story investors were buying into.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Interroll is not the only name tied to this theme. Zero in on 91 robotics and automation stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On Interroll
The shares cost CHF2,405 at the start of the period, and Interroll sat between two competing stories about where its automation exposure might lead.
The bullish view put Fair Value at CHF2,682. It leaned on revenue growth assumptions of 10.3% and a profit margin of 14.0%, tied to e-commerce demand, new modular platforms and expansion in Asia-Pacific and North America.
The bearish side framed Fair Value at CHF2,042, with concern that aggressive Chinese competitors could pressure pricing, particularly in commoditised rollers, and that heavier regulation and protectionism would squeeze profitability.
What The Evidence Did To The Interroll Argument
Interroll’s headline move was acquisition. Buying Royal Apollo Group and its Nordic distributor expanded vertical conveying, services, and regional reach, which supported the bullish focus on a broader automation portfolio and larger addressable market. The numbers told a different story. Revenue reached CHF269.928m in H1 2026 while net income slipped to CHF19.751m and net margin declined to 7.3%. The period therefore cut both ways.
The lesson is simple. When a thesis leans on margin recovery, you track net margin first. For any automation stock, test every growth story against whether reported profitability per franc is actually moving toward the assumption on paper.
What Interroll’s Lower Price Now Asks You To Believe
Interroll trades at CHF1,424 today after a 38.9% loss over the past year, and the selected Narrative’s Fair Value sits above that market price. The argument focuses less on generic automation demand and more on whether underused manufacturing capacity and recent deals can eventually support higher quality project throughput.
The core judgment now is simple. A buyer has to believe that shifting from components to modular platforms, combined with Asia Pacific build out and service heavy acquisitions, will fill that capacity fast enough for margins to reflect it.
"The main requirement is that Interroll successfully executes its shift from components to modular platforms while deepening regional presence, so that recent order momentum and service expansion translate into sustainably higher throughput of projects."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 44% below our estimate - uses higher end mall exposure and faster inventory turns to improve unit economics.
- Company 2 - 50% below our estimate - builds a payments, shopping and banking app around strong local marketplace share.
- Company 3 - 41% below our estimate - collects fees from buying, improving and selling essential infrastructure assets for institutions.
That is three of the list. See all 194 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com