


VinFast Stock Has The Bull Case Changed After Delivery Growth
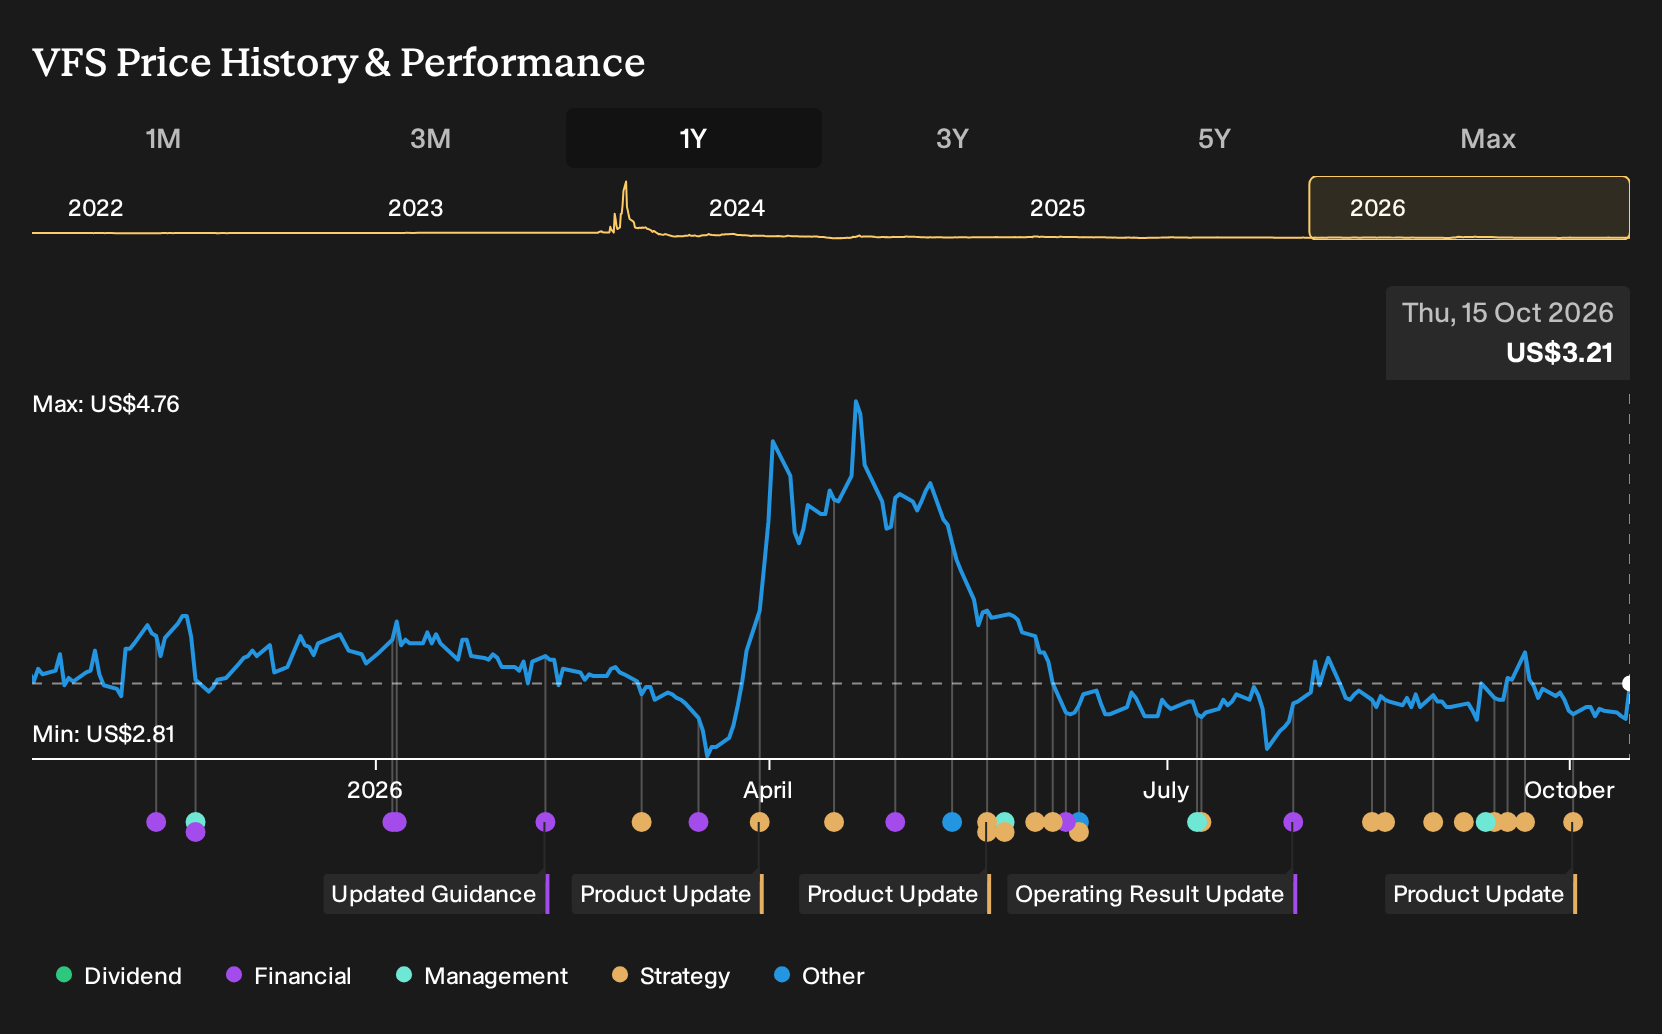
- VinFast Auto reported preliminary Vietnam deliveries of 23,624 EVs in September 2026, with year to date domestic deliveries of 177,697 vehicles, reinforcing its reported leadership in the local automotive market.
- Green SM’s launch of an all electric VinFast powered taxi fleet in Los Angeles highlights how VinFast vehicles are being used in real world, high utilization transport services outside Vietnam.
- We will look at how VinFast Auto's investment narrative is shaped by strong Vietnam deliveries and fleet deployment in Los Angeles.
Scan beyond VinFast Auto and identify other EV and clean transport players that align with this momentum shift using the 32 resilient stocks with low risk scores.
VinFast Auto Investment Narrative Recap
For a shareholder in VinFast Auto, the core belief is that high volume EV adoption in Vietnam and selected overseas markets can eventually support a path toward better unit economics. The latest Vietnam delivery update points to scale building at home. This matters because breakeven targets rely on domestic volumes moving closer to management’s earlier 200,000 vehicle threshold.
The key near term catalyst remains evidence that this volume can convert into improved gross margins and a slower cash burn. The main risk still sits on the balance sheet. Short cash runway, negative equity and ongoing losses mean fresh capital or tighter spending discipline are likely to stay in focus.
The most relevant update here is the September 2026 delivery disclosure, including 23,624 EVs for the month and 177,697 year to date in Vietnam. That data point gives you a cleaner read on underlying demand and fleet uptake at home, including any contribution from intragroup customers such as Green SM.
For catalysts, that delivery scale has to eventually intersect with cost work already under way, such as next generation platforms and vertical integration. This would help ease reliance on external funding. If volumes plateau or mix shifts away from higher quality B2C buyers, the pressure on gross margins, cash burn and potential dilution risk stays elevated.
What The VinFast Auto Analyst Case Is Really Asking You To Believe
VinFast Auto's consensus story hinges on a sharp turn in the income statement over the next few years. Analysts are working off revenue growth assumptions of 33.7% a year and a shift from a very deep loss today to positive earnings by 2029.
On their numbers, the business would be generating ₫231,973.7b in revenue and ₫5,304.7b in earnings in 2029. That compares with current losses of ₫109,772.8b. The swing implied in that bridge is very large in absolute terms, moving from heavy red ink to a modest profit pool.
To make the maths work, the model assumes profit margins lift from about a loss of 113.2% today to 2.3%, roughly in line with the average US auto peer set. In practical terms, that means you are being asked to underwrite a mix of higher volumes, better pricing discipline, and lower costs across the product range, all at the same time.
The valuation overlay is even more demanding. The consensus framework uses a future P/E of 120.7x on those 2029 earnings, compared with the current US auto industry at 14.9x. That is a premium multiple on top of already ambitious profitability assumptions, which leaves little room for disappointment on either margins or growth.
VinFast Auto's narrative projects ₫231,973.7b revenue and ₫5,304.7b earnings by 2029. This requires 33.7% yearly revenue growth and a move from a loss of ₫109,772.8b today to earnings of ₫5,304.7b.
Uncover why VinFast Auto's fair value indicates an 88% potential upside to its current price before the discount to VinFast Auto closes.
Exploring Other Perspectives
One alternate angle focuses on concentration risk. Bullish analysts were already assuming faster 36.5% yearly revenue growth and earnings of ₫5,691.3b by 2029, yet still expected 70% to 80% of volumes to rely on Vietnam. With the new delivery update and the Los Angeles fleet launch, that home market dependence may now be reassessed in very different ways.
Explore 3 other VinFast Auto fair value estimates, including one that suggests as much as 140% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your VinFast Auto research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for VinFast Auto. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VinFast Auto's overall financial health at a glance.
Looking For More Investment Ideas Beyond VinFast Auto?
Once you have formed a view on VinFast Auto, broaden your watchlist by scanning for other companies whose balance sheets, income profiles, and risk scores better match your own comfort level. The Simply Wall St Screener can help you filter the market quickly so you spend time assessing a focused shortlist rather than a crowded field.
- If capital preservation is front of mind, start with companies that pair resilient financial positions with measured risk profiles using the 32 resilient stocks with low risk scores.
- If solid fundamentals matter more than market attention, hunt for under followed businesses with strong balance sheets and cash generation via the 20 high quality undiscovered gems.
- If you want potential income alongside analysis of underlying quality, focus on payout opportunities with yield support using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com