


Should Earnings Upgrade Require Action From Kuehne Nagel Investors?
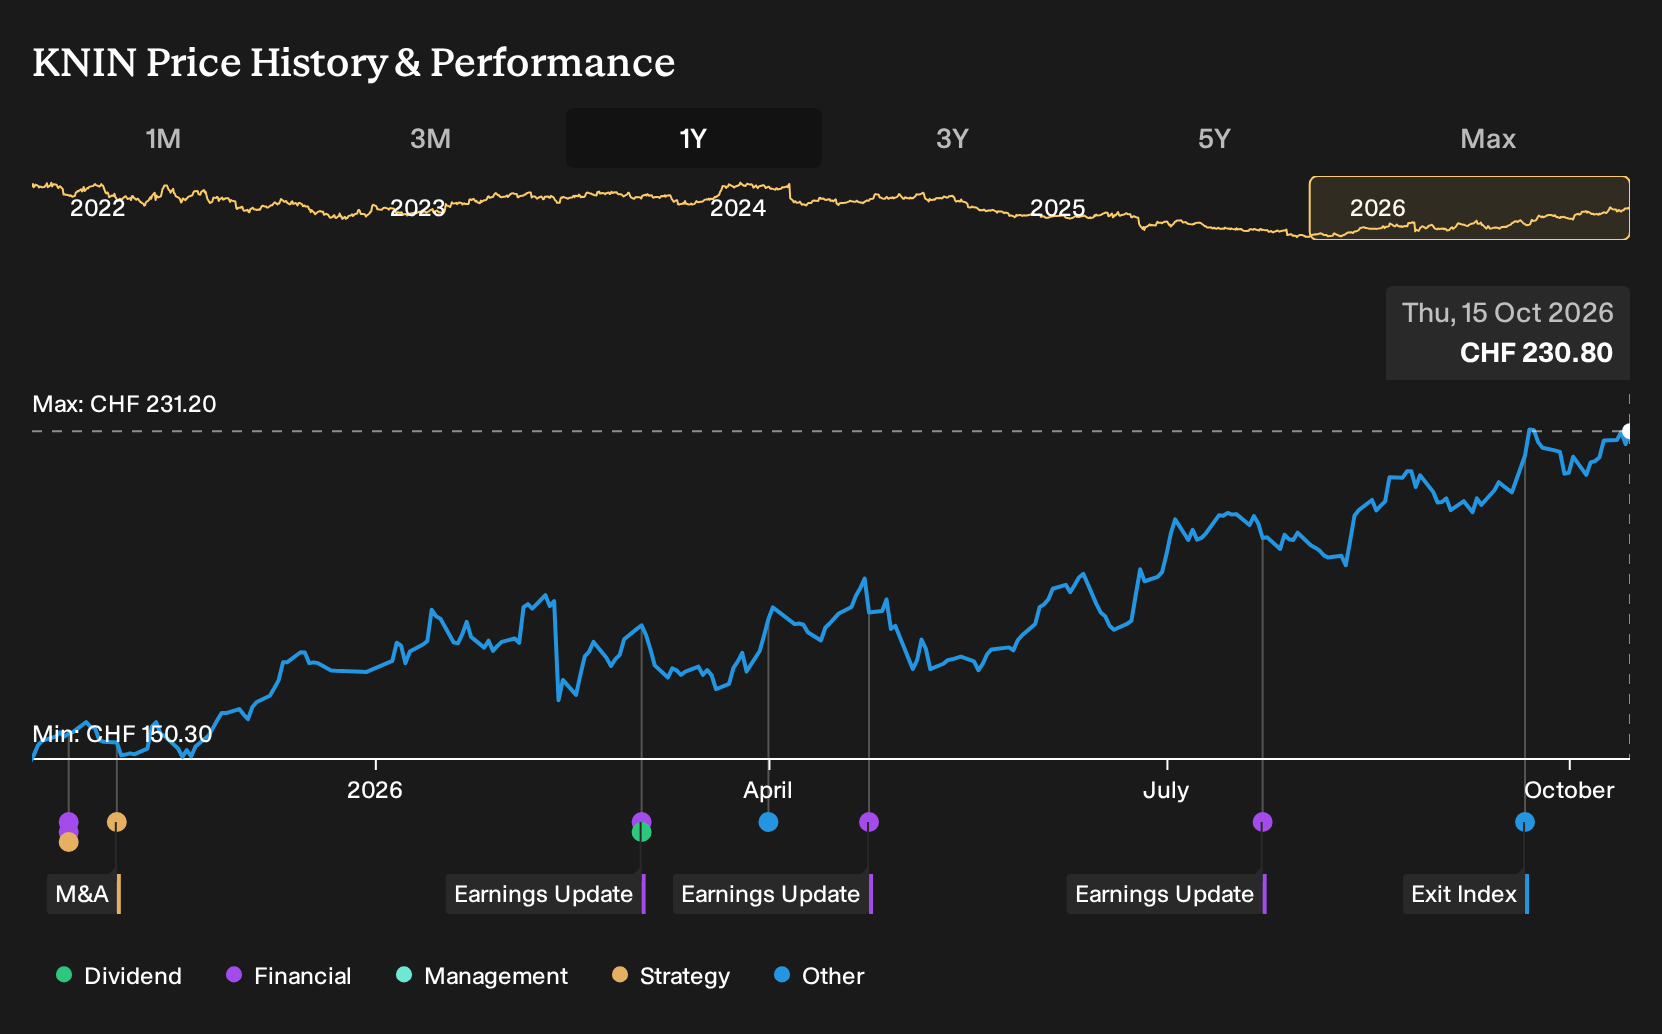
- Kuehne + Nagel International recently attracted attention after full year earnings estimates were revised 1.2% higher over the past 90 days, alongside a Zacks Rank of #2 and year to date total return of about 24.9% versus 6.2% for the wider transportation sector.
- The key development is a firmer earnings outlook that points to stronger operating performance relative to sector peers, with analyst optimism acting more as a reflection of this shift in fundamentals rather than the main story.
- We will now look at how Kuehne + Nagel International's investment narrative is influenced by this firmer full year earnings outlook.
Scan other transport and logistics stocks showing firm earnings sentiment and year to date strength by reviewing our curated 196 high quality undervalued stocks alongside Kuehne + Nagel International's latest move.
Kuehne + Nagel International Investment Narrative Recap
To own Kuehne + Nagel International, you need to be comfortable with a freight forwarder that leans heavily on efficiency gains, higher value sectors like healthcare and semiconductors, and digital processes to support earnings. The recent upgrade to full year earnings expectations points to firmer operations in the near term. It does not remove the key short term swing factor, which is how quickly Sea Logistics and Air Logistics yields settle.
The biggest immediate risk still sits in weaker sea freight pricing and margin dilution in Contract Logistics, where start up costs and lower recurring EBIT are already visible. If those pressures persist, earnings quality could feel soft even with better productivity. The updated outlook hints that AI led cost savings and mix shift are doing some work, but investors should treat that as a partial counterweight rather than a solved problem.
With no fresh corporate announcements flagged around this move in expectations, the most relevant context remains Kuehne + Nagel International's quantified AI productivity program. Management is targeting at least 5% efficiency gains on more than 25,000 white collar roles, with an EBIT contribution of CHF 100m to CHF 150m by the end of 2027. That is material compared with recent EBIT pressure in Sea Logistics and Contract Logistics.
For you as a shareholder, this matters because the same freight cycles that hit yields can be offset by recurring cost savings if execution holds. The stronger earnings outlook over the past 90 days suggests analysts now see that program, alongside exposure to higher margin verticals, helping to support profitability. The risk is timing. If freight markets stay soft longer than expected, the company needs those efficiency gains to come through without delay.
What The Current Forecasts Assume For Kuehne + Nagel International
Kuehne + Nagel International's consensus narrative points to revenues of CHF 27.1b and earnings of CHF 1.3b by 2029, based on analysts assuming 3.8% yearly top line growth and a move in profit margins from 3.6% today to 4.8% in 3 years. That path implies an earnings increase of about CHF 436m from current earnings of CHF 864m to the 2029 forecast of CHF 1.3b.
Uncover why Kuehne + Nagel International's fair value indicates an 11% potential downside to its current price, suggesting that this premium may not hold.
Exploring Other Perspectives
One bullish perspective on Kuehne + Nagel International emphasizes the AI and cost program as a much stronger catalyst than freight cycles. The most optimistic analysts were already pencilling in CHF 28.5b of revenue and CHF 1.5b of earnings by 2029 before this latest earnings upgrade. You can treat that as a stretch case and compare it with the more cautious forecasts to see how views might shift as the new estimate revisions filter through the models.
Explore 3 other Kuehne + Nagel International fair value estimates, including one that suggests as much as 40% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kuehne + Nagel International research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kuehne + Nagel International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kuehne + Nagel International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kuehne + Nagel International?
If you want to pressure test your view on Kuehne + Nagel International, it can help to line it up against other stocks with different income profiles, risk levels, and balance sheet strength using the Simply Wall St Screener.
- If you are focused on resilience first and returns second, start with a group of 227 resilient stocks with low risk scores that may better align with a capital preservation mindset.
- Income driven investors can scan for consistent cash payouts by reviewing a curated set of 218 dividend fortresses that may help anchor a yield focused portfolio.
- For those hunting for quality businesses that the market may be overlooking, compare Kuehne + Nagel International with a hand picked pool of 615 high quality undiscovered gems that show strong fundamentals yet limited attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com