


Byline Bancorp (BY) Could Be 15% Undervalued On Leadership Succession Plan
Byline Bancorp (BY) just mapped out a major leadership handover, with long serving commercial banking and credit chiefs set to retire as new executives step into expanded roles.
Recent trading tells a mixed story for Byline Bancorp. The share price is around $36.90, with a year to date share price return of 27.07% and a 1 year total shareholder return of 45.59%, pointing to solid longer term momentum. This comes despite a softer 30 day share price return of 3.35% and a 90 day share price return of 3.05%, which suggests enthusiasm has cooled a little as investors weigh succession plans and earlier gains.
Spot 32 resilient stocks with low risk scores that, like Byline Bancorp, pair leadership stability with balance sheets designed for resilience through management transitions.After a sharp run over one year and a softer patch in recent weeks, Byline Bancorp now sets up a cleaner leadership picture and a tougher call. Does the current valuation still offer a clear upside skew for new money?
Most Popular Narrative: 14.6% Undervalued
Byline Bancorp's most followed narrative pegs fair value at $43.20, comfortably above the recent $36.90 close. This puts the leadership reshuffle against a backdrop of a company framed as undervalued on long term earnings power and efficiency.
The combination of a strong capital position, regular dividend increases and active share repurchases, together with an open stance toward selective bank acquisitions, is characterized as giving Byline Bancorp multiple levers to deploy excess capital in ways that can support earnings per share.
See why 0 investors see Byline Bancorp as 15% undervalued.
Result: Fair Value of $43.20 (UNDERVALUED)
Still, the Byline Bancorp story can be knocked off course if crossing the US$10b asset mark drives higher regulatory costs, or if future acquisitions dilute efficiency gains.
Find out about the key risks to this Byline Bancorp narrative.
Another View: What P/E Says About Byline Bancorp
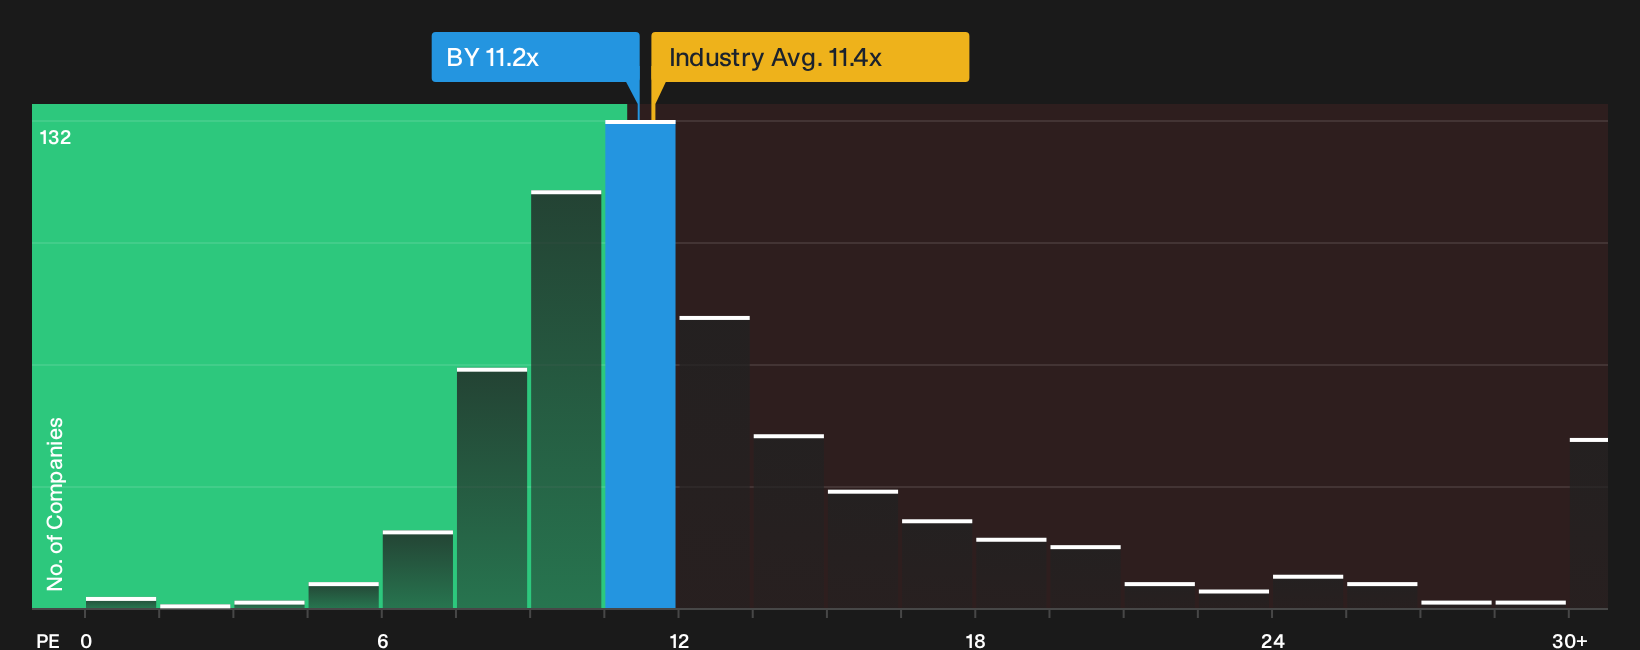
The SWS fair value work presents Byline Bancorp as attractively priced, while the simple P/E check appears more cautious. BY trades on an 11.2x P/E, slightly above its 10.9x fair ratio, even though it is below peer averages at 15.2x and close to the US Banks industry at 11.3x.
For investors, that gap may indicate that potential downside if sentiment cools could be smaller than for higher-valued peers. It also suggests less obvious upside than a straightforward discount story. Which version of value seems more informative, the detailed model or the quick multiple snapshot?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Torn between enthusiasm and caution around Byline Bancorp's story right now? Act quickly, review the underlying numbers, and pressure test both sides of the debate through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Byline Bancorp?
If you stop with Byline Bancorp, you risk missing other opportunities that match your style. Cast the net wider and let the numbers do the sorting.
- Target resilient balance sheets and strong fundamentals by running your filters through the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality trading at a discount by scanning companies that show up in the 20 high quality undiscovered gems.
- Prioritise income and stability by zeroing in on reliable payers using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com