


3 Cash Management Stocks Built For Higher Rates
Fed Chair Warsh just reminded markets that price stability comes first, even if that means rates stay higher for longer and borrowing stays painful. Cash is no longer just a parking bay. It is a yield decision that can help or hurt your overall returns depending on where you place it. This article examines how that backdrop affects short-duration yield and cash management stocks, and highlights 3 ideas exposed to this backdrop that merit a closer look.
The stocks covered below are just a sample, and the full screen surfaced 37 more U.S. short-duration yield and cash management companies with equally compelling stories around liquidity, fees, and interest income that are not included here.
If you want to identify which tickers best fit your own risk profile and income goals, head straight to the U.S. Short-Duration Yield and Cash Management Stocks screener to filter, analyze, and focus on the highest conviction ideas.
Horizon Bancorp (HBNC)
Horizon Bancorp is a classic community banking platform for this short duration and cash management theme, with everyday deposits and short term loans representing the point where Fed policy turns into real interest income for customers and shareholders alike.
Horizon Bancorp runs a full service commercial and retail bank in Indiana and Michigan, earning revenue from lending, deposit and fee based services in the United States, with reported commercial banking revenue of about US$12 million in decline and a market cap near US$975 million.
"Horizon Bancorp is still reallocating its balance sheet toward higher yielding commercial and industrial lending, with commercial balances rising and C&I loans reaching about 31% of the commercial portfolio in Q2 2026."
What happens to margins if a single pressure on funding costs moves faster than the short duration assets investors are focusing on here?
If that funding squeeze is what you are weighing, read the full narrative for Horizon Bancorp to see how Horizon Bancorp’s deposit mix, fees and capital plans intersect.

National Bank Holdings (NBHC)
National Bank Holdings leans directly into the short duration and cash management theme, turning everyday deposits and near cash balances across its regional footprint into interest income while trying to keep funding costs in check as Fed policy keeps short term yields elevated.
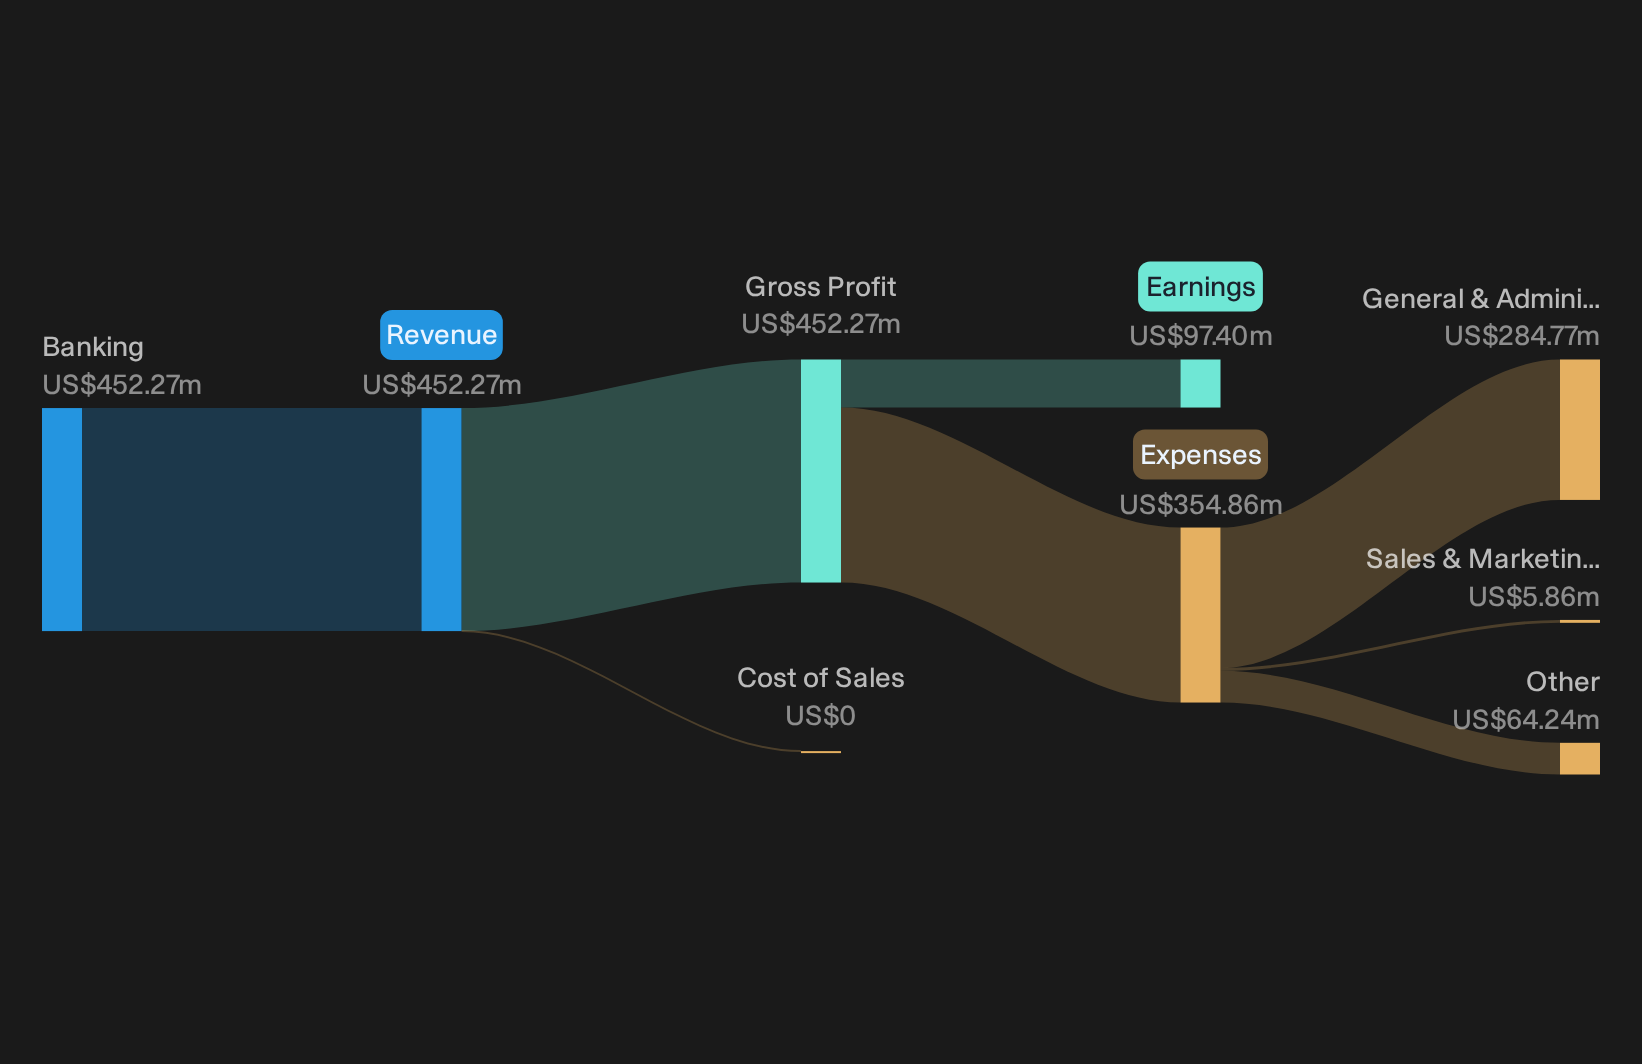
National Bank Holdings generates about US$452 million of banking revenue from its U.S. operations, built on a mix of deposits, loans and treasury services, and the stock carries a market value of roughly US$1.7b.
For investors tracking how banks are using higher short term rates, the more interesting story is how National Bank Holdings is choosing to spend on its next leg of fee income.
"The 2UniFi small business platform is still in the investment phase, with expenses of about US$20 million to US$22 million in 2026 and guided revenue of US$2 million to US$4 million. Any improvement in credit conversion or monetisation could lift National Bank Holdings noninterest income and narrow the drag on earnings."
What happens to the appeal of this short duration cash engine if a single moving part in that broader earnings mix does not behave as planned?
That single moving part is exactly where the story of National Bank Holdings can accelerate or stall. The full narrative for National Bank Holdings explains how funding costs, fee ambitions and credit risks interact.
Glacier Bancorp (GBCI)
Glacier Bancorp sits right in the sweet spot of this short duration and cash management theme, turning a broad base of mostly low friction deposits into interest income on loans and securities that reset relatively quickly when short term rates move.
Glacier Bancorp generates about US$1.1b in Banking Services revenue entirely in the United States, with a market value near US$5.6b.
"Continued repricing of Glacier Bancorp’s loan and securities books, combined with the removal of $440 million of higher cost Federal Home Loan Bank advances and lower total funding costs that moved from 1.52% in Q4 2025 to 1.33% in Q2 2026, is expected to keep widening net interest margin and support future earnings."
The real swing factor is what happens to this short rate advantage if a single unseen pressure on funding costs forces deposit pricing higher faster than assets reprice.
If that pressure point is what you are trying to size, read the full narrative for Glacier Bancorp to see how Glacier Bancorp’s funding costs, margins, and earnings potential could be decoupling.

Seeking Alternatives Before The Crowd?
Fresh ideas move first when momentum builds and weaker stories start dropping. Scan under the radar for now, catch potential breakouts before the crowd, and consider acting promptly.
- Target durable income streams while short term yields stay elevated by scanning a curated 8 dividend fortresses that focuses on payout strength and balance sheet resilience.
- Explore structural demand for secure transaction rails and new payment models by checking a hand picked 19 cryptocurrency and blockchain stocks before momentum potentially accelerates.
- Track the build out behind AI data centers and electrification by reviewing a refined 41 power grid technology and infrastructure stocks while valuations still reflect early stage expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com