


What Investors Got Wrong About Vistry Group Before A 63% Slide
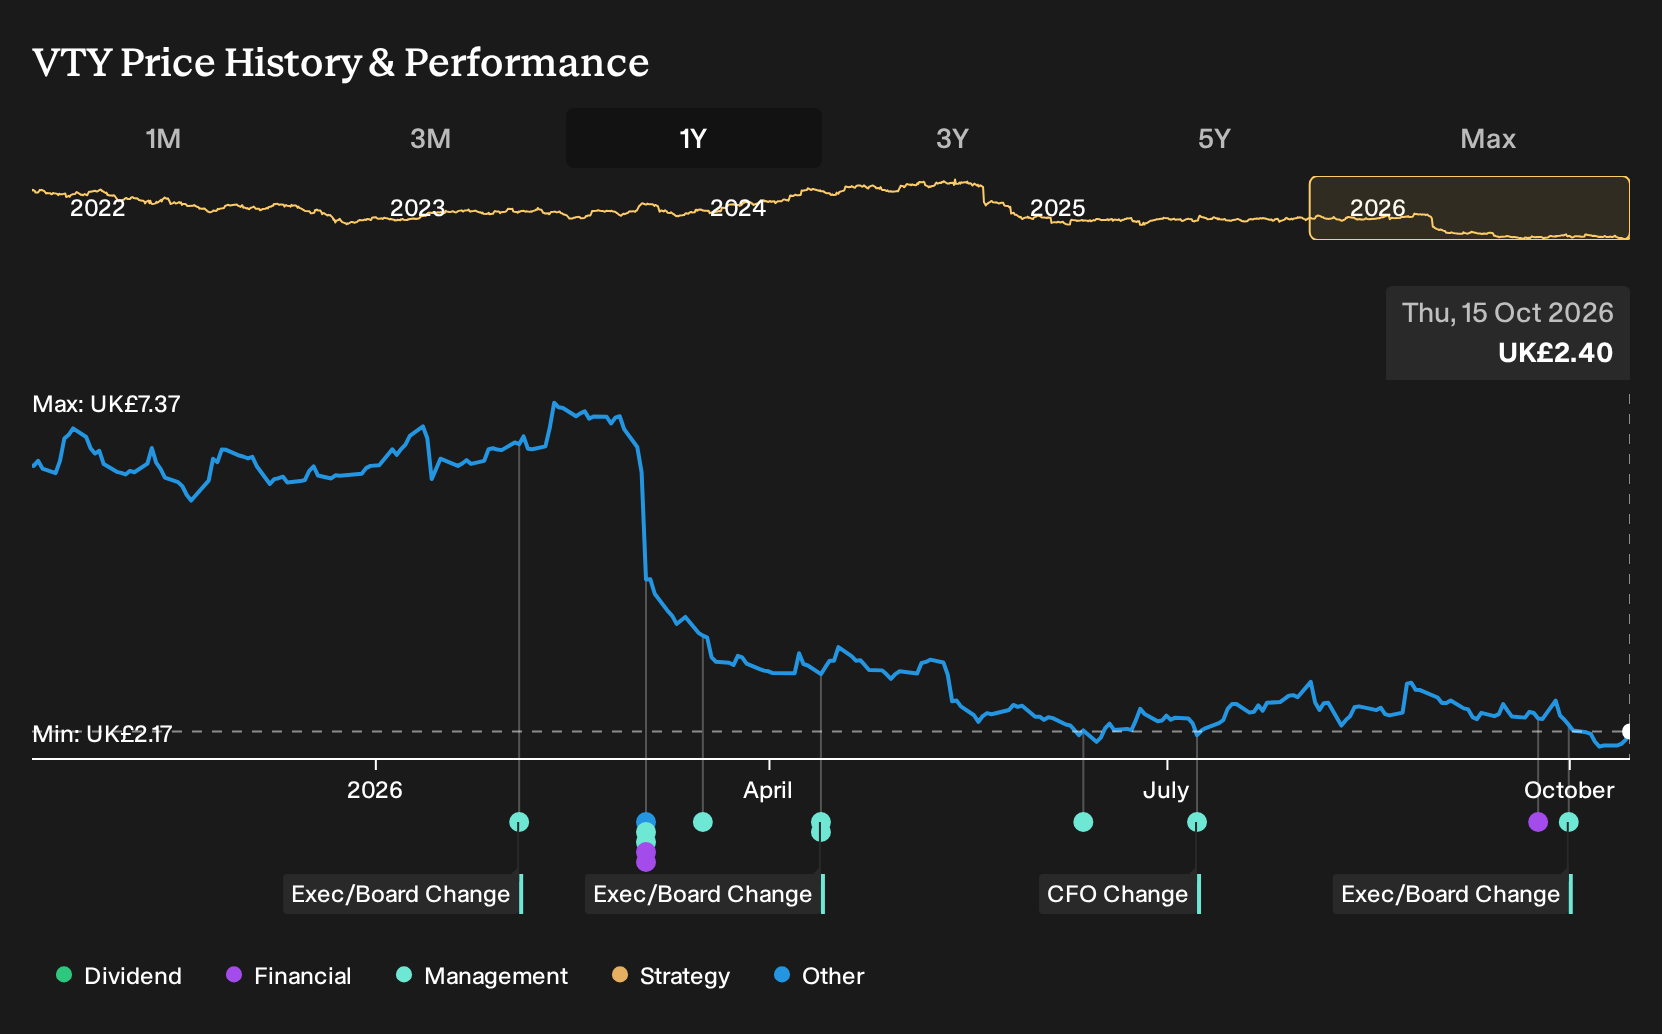
A sharp rally in UK housebuilders followed recent Bank of England comments that questioned the need for multiple rate hikes, and Vistry Group moved with the pack as bond yields eased and property stocks perked up. Investors who held Vistry Group over the past year are down 63.0%, including dividends. If you had put money in on 15 October 2025, how should that outcome reshape expectations about its affordable housing model now?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Vistry Group harder to judge, start where the gap is still open and scan 9 high quality undervalued stocks.
The Two Stories Investors Had To Hold In Their Heads
The shares cost £6.41 at the start of the period, so anyone looking at Vistry Group then had to decide which of two very different stories sounded more convincing.
On the bullish side, the Narrative put Fair Value at £7.73 and leaned on affordable housing demand plus offsite manufacturing. Supporters focused on assumptions like revenue growing 11.9% a year and profit margins moving from 2.0% to 6.1% by 2028.
The bearish view saw Fair Value at £4.5 and treated Vistry Group's reliance on UK affordable housing policy as a key vulnerability. That story rested on assumptions such as revenue declining 0.4% a year while margins rose from 2.0% to 6.6% by 2028.
What The Results Put To The Test For Vistry Group
The clearest test for Vistry Group came from its H1 2026 numbers. Revenue declined from £1,635.6m to £1,418.2m and a £31.3m profit turned into a £607m loss, pulling net margin from 1.9% to a loss of 42.8%. That scale of setback challenged the bullish profitability path and gave more weight to the cautious case.
The key assumption here was margin resilience in an affordable housing heavy model. When you look at another builder, check whether promised efficiency gains show up in net margin, rather than only in revenue or order-book headlines.
What You Would Be Paying For In Vistry Group Today
Vistry Group now trades at £2.4, with the Narrative's Fair Value sitting above that level based on its own assumptions about the business. The current argument leans on more of the portfolio reaching higher returning sites and the restructured regions squeezing more profit from each plot.
For the fall to look like an opportunity rather than a warning, a buyer today would need to believe that consistent execution on the 12 region setup, the Linden range and lower net debt can translate the affordable housing model into the higher margins this Narrative describes.
"Some analysts expect Vistry Group to turn its mixed tenure partnerships model and modern construction methods into higher margin, higher return volumes as more sites reach the performance already seen on the best 59% of the portfolio. The main thing that would need to go well is consistent execution of the simplified 12 region structure and Linden product range, so that more of the 12,000 unit medium term target delivers the 12% operating margin and greater than 30% ROCE that management is aiming for."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 28% below our estimate - processes rising investment inflows on a unified tech platform spreading fixed costs.
- Company 2 - 24% below our estimate - attracts senior lawyers shifting from partnerships into a tech enabled, lower overhead model.
- Company 3 - 17% below our estimate - scales supplement production after automation lifts capacity while distributors enter new regions.
That is three of the list. See all 9 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com