


JDC (TSE:1887) Q1 Earnings Highlight Margin Gains On A Low P E
JDC just reported Q1 2027 earnings and the headline is simple. Profitability looks stronger on a twelve month view while the stock is priced as if that improvement barely counts. Coming into the release, the shares had drifted over the past month and now sit at ¥518, with the market still tagging the business with a trailing P/E of 7.2x.
Some short term traders appear to be reacting to noise, but a larger development is a substantial increase in trailing earnings and a net margin that has moved to 4.3%. The price action suggests doubt, whereas the income statement indicates improvement.
Like the earnings trend at JDC but uneasy about a market that prices that shift on a single digit P/E? Compare this setup with our 14 high quality undervalued stocks
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs Q1 2026): ¥32,056m vs. ¥34,515m (down about 7%, indicating a softer top line even as profit metrics improve)
- Net Income (Excl. Extra Items, Q1 2027 vs Q1 2026): ¥1,587m vs. ¥1,302m (up roughly 22%, reflecting stronger profitability on a smaller revenue base)
- Basic EPS (Q1 2027 vs Q1 2026): ¥19.89 vs. ¥16.34 (around 22% higher, which is consistent with the increase in net earnings per share)
- Net Margin (Trailing 12 Months vs Prior Year): 4.3% vs. 0.7% (a material improvement in profitability, with earnings quality described as high over the last year)
Skip the rosy margin jump. Ask Charlie what makes JDC’s cheap earnings look risky.
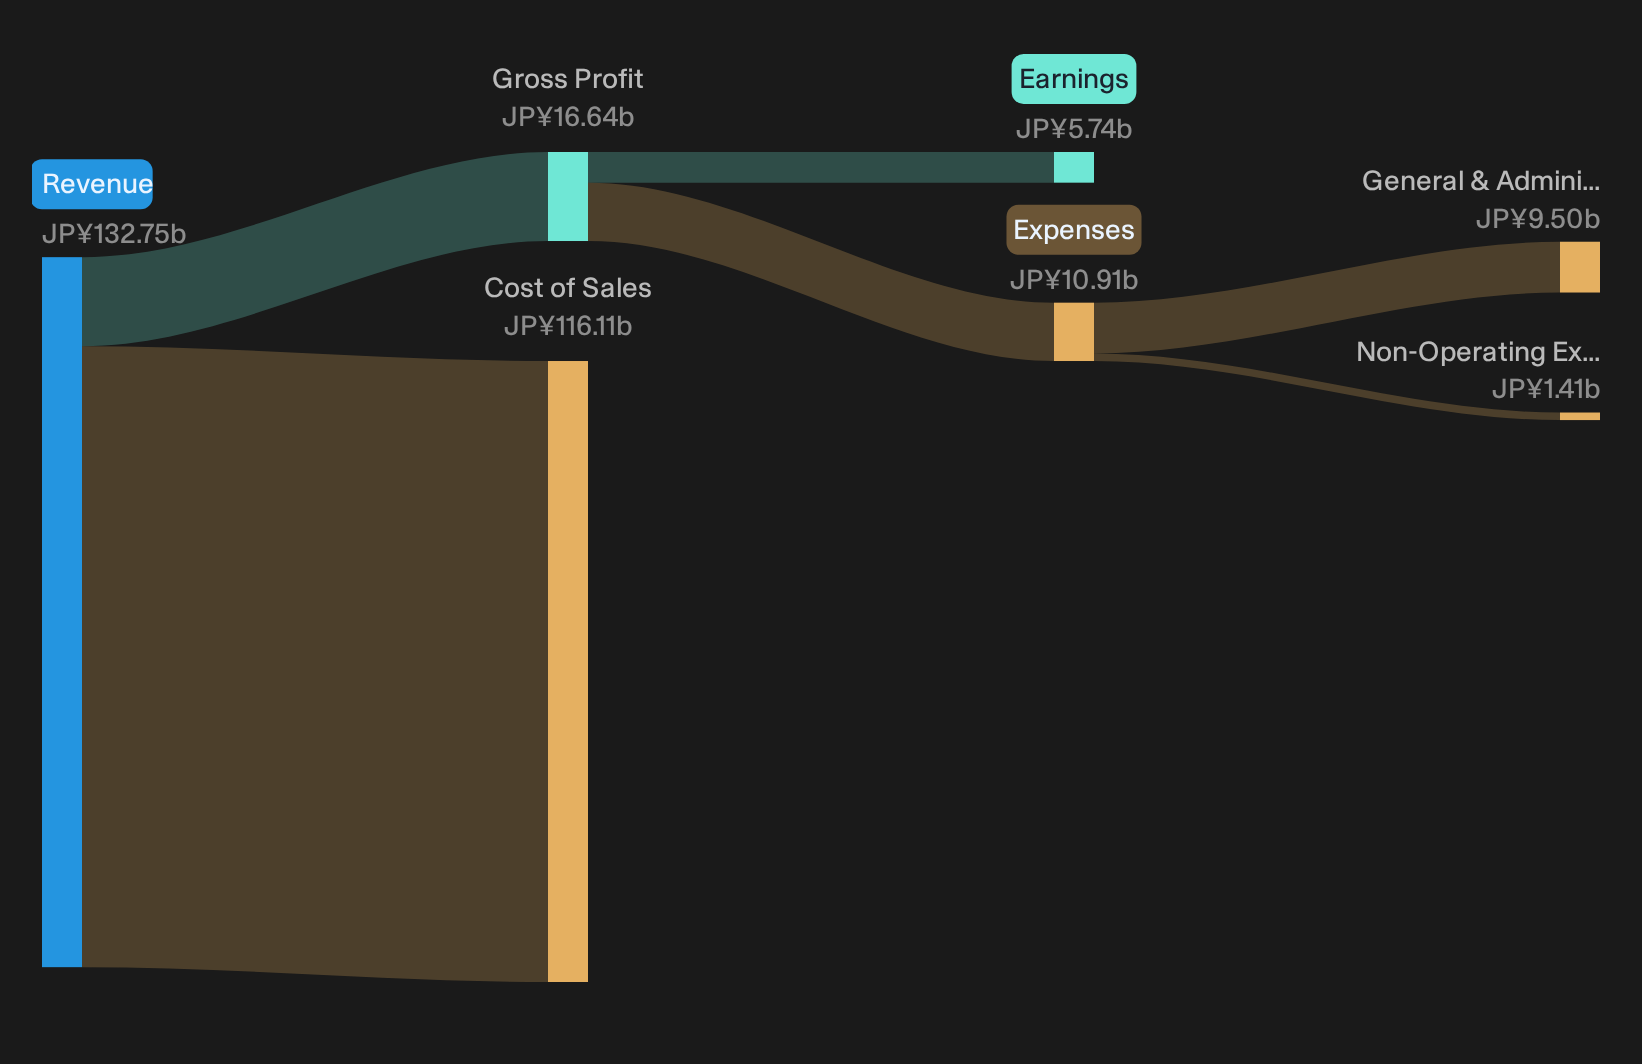
Profit Trend Lends Support To JDC Optimists
For anyone leaning positive on JDC, the latest figures give the story some backbone. Earnings rose on a softer top line, with net income and EPS both moving higher even as revenue slipped from ¥34,515m to ¥32,056m. That combination is hard to achieve in construction. A trailing net margin of 4.3% versus 0.7% points to a business that is converting work into profit more efficiently. Short term share performance has been mixed over 30 days; however, the income statement points to better underlying economics than a year ago.
Revenue Softness Keeps The Cautious View Alive
The Bears are not out of arguments. JDC posted weaker sales year on year, which fits a cautious view for a contractor exposed to project timing and budget cycles. A 7% fall in revenue while profits climb can raise questions about how repeatable current earnings really are if volumes stay under pressure. Recent share returns also show a pullback over the past month despite the result. This suggests investors continue to worry that higher margins may prove fragile if bidding turns more competitive or public works pipelines slow.
After a 7% revenue drop and a dividend that is not well covered by free cash flow, it is fair to ask whether JDC’s higher margin profile is masking deeper structural issues around project mix, capital discipline, or earnings resilience. Review our risk analysis for JDC which shows 2 important warning signsHunt For Mispriced Earnings Power
JDC just showed how headline questions on revenue can sit beside firmer profit metrics. The real opportunity could lie in stocks that appear misaligned before valuations catch up.
- Company 1 - 36% below our estimate - helps match car buyers with inspected used inventory while bundling maintenance and financing services.
- Company 2 - 44% below our estimate - sells subscription cloud tools that automate expense, billing and sales workflows for smaller firms.
- Company 3 - 46% below our estimate - supplies molding systems that let beverage and consumer brands shift plastic packaging designs with limited downtime.
Those are three of them. See the full list of 14 companies trading below our fair value estimates →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com