


0% Above Fair Value DCC Energy (LSE:DCC) On Fresh Rule 8.3 Interest
Institutional interest in DCC Energy (LSE:DCC) has moved into sharper focus after a series of Irish Takeover Panel Rule 8.3 disclosures highlighted positions above the 1% threshold across several global asset managers.
At a latest share price of £64.30, DCC Energy has barely moved over the past week. However, a 30-day share price return of 1.5% and a 90-day gain of 2.3% sit alongside a strong year-to-date share price return of 41.5% and a 1-year total shareholder return of 43.3%, hinting that the fresh wave of Rule 8.3 disclosures is arriving after a long period of building momentum rather than driving it.
Scan how other institutions are positioning by comparing DCC Energy to a hand picked list of solid balance sheet and fundamentals (9 results) that may appeal to investors watching this latest Rule 8.3 activity.
Bulls point to DCC Energy’s strong recent returns and reported profit growth. Bears flag takeover noise and energy transition risks. The valuation work that follows helps indicate which side current pricing appears closer to.
Most Popular Narrative: 0% Overvalued
DCC Energy’s most followed valuation narrative places fair value at £64.20, almost identical to the last close at £64.30. This frames the recent institutional positioning against a market that already prices in a balanced set of expectations.
The current valuation suggests DCC Energy is fairly valued and that the market already reflects a continued combination of disciplined capital returns, such as the £800m shareholder payout, together with the balance sheet capacity created by net debt at 0.9x EBITDA to fund further energy acquisitions.
See why 29 investors see DCC Energy as 0% overvalued.
Result: Fair Value of £64.20 (ABOUT RIGHT)
Still, the fair value story for DCC Energy depends on Energy Services returning to profit and Energy Products avoiding extended volume softness and margin pressure.
Find out about the key risks to this DCC Energy narrative.
Another View: What DCC Energy’s P/E Is Really Saying
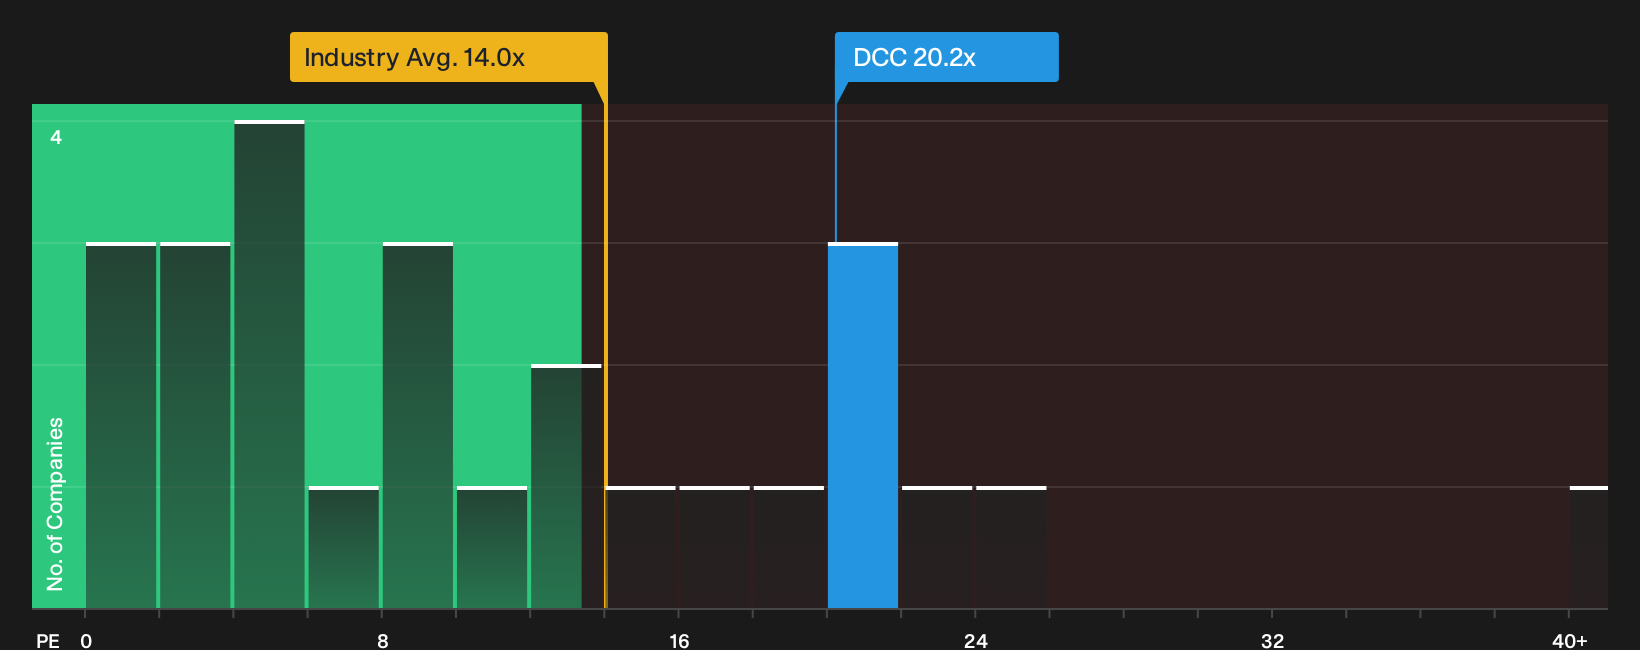
The SWS DCF work points to fair value near the current £64.30 share price, yet the P/E picture tells a different story. DCC Energy trades on 20.2x earnings, which matches its peer group average of 20.2x but sits well above the European Oil and Gas sector on 14x. The SWS fair ratio of 23.3x suggests the market could shift toward paying a richer multiple over time, although today’s premium to the wider industry means less margin for error if earnings disappoint. Which signal do you treat as more important when weighing upside against valuation risk?
For a closer look at how this earnings multiple stacks up against sector peers, you can review the full valuation breakdown here, including the fair ratio and underlying assumptions, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around DCC Energy is finely balanced. It helps to see the full picture and move quickly to form your own judgment based on the 3 key rewards.
Looking for more investment ideas beyond DCC Energy?
If the DCC Energy story has sharpened your thinking, use that momentum and line up a few more candidates before the next catalyst hits.
- Target steadier potential by scanning a 4 resilient stocks with low risk scores that filters for resilience when headlines turn noisy.
- Chase mispriced quality through a 5 high quality undiscovered gems that surfaces strong fundamentals the wider market may not be focused on yet.
- Strengthen your short list with a 4 dividend fortresses that highlights income ideas offering yields many investors overlook.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com