


Does NatWest Group (LSE:NWG) Look Fully Valued After Barclays Upgrade?
NatWest Group has ridden a powerful share price recovery over the past few years, and recent upgrades from the sell side have kept the stock in the spotlight. The question for you now is whether that higher price is still backed up by the bank's earnings power.
- Over the past 5 years the share price return of about 290.8% means any view on NatWest today is really a view on how durable its profit engine is.
- Barclays' recent upgrade, framed around a stronger earnings outlook and a higher price target, signals that expectations for future profitability and capital generation have shifted upward. This can reshape how investors think about what counts as a reasonable earnings multiple.
- The analysts covering NatWest Group have run their own numbers. See what analysts think NatWest Group's shares could be worth.
The stock's next move may depend on whether the current price can be squared with the earnings NatWest is generating today and is expected to generate over time.
If you are considering whether NatWest Group's 290.8% five year return is justified by its earnings, it can help to compare that question across 9 high quality undervalued stocks.
Does NatWest Group Look Fairly Valued on Earnings?
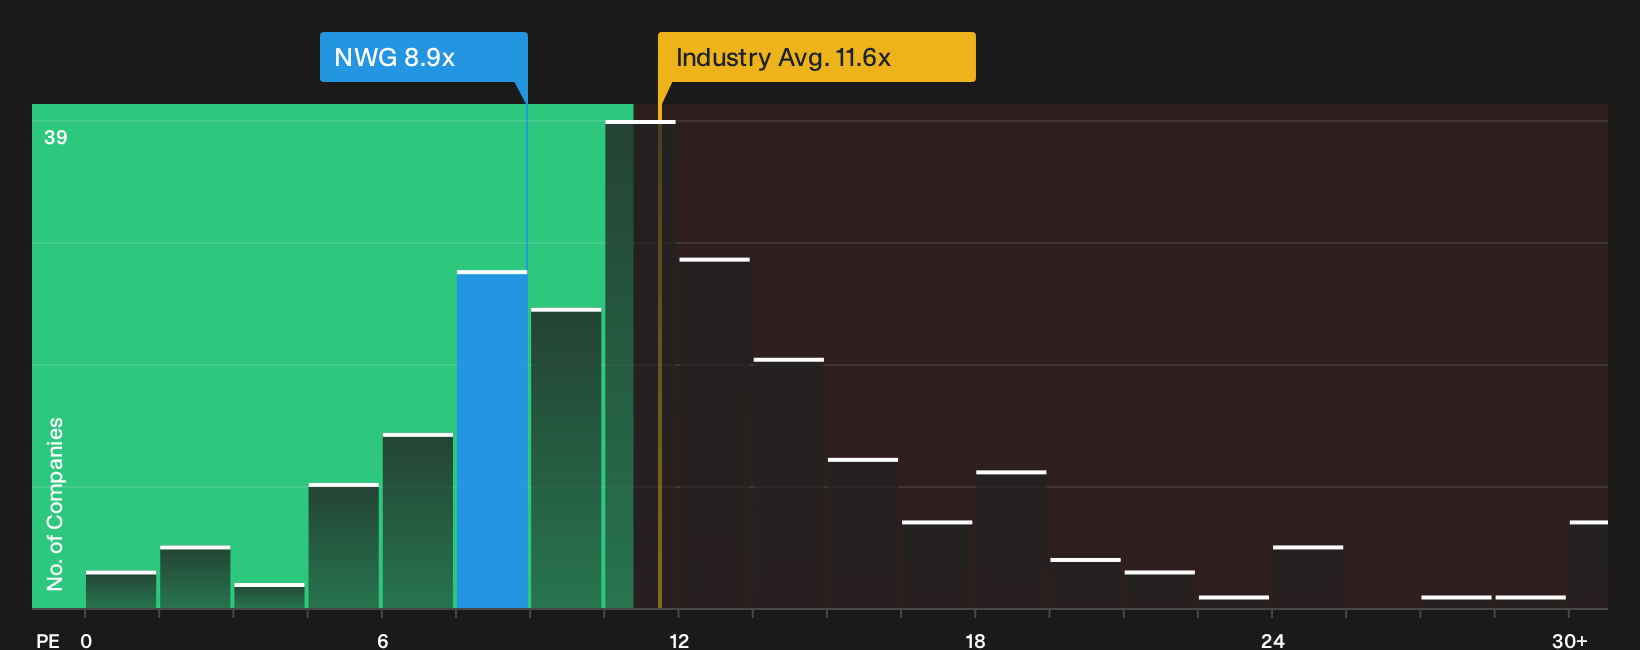
The P/E ratio suits NatWest Group because earnings are still the core yardstick investors use for large banks. On this measure, NatWest trades on about 8.9x earnings, compared with roughly 11.1x for the wider Banks industry and around 12.3x for its peer group. That places the stock on a lower multiple than many comparable lenders, even after the strong share price recovery already seen in NatWest.
The Fair Ratio model, which blends the firm’s own growth outlook, margins, risk profile and size, points to a P/E close to where NatWest is currently priced, so the market is not giving away the shares nor stretching them aggressively. Because Barclays’ recent upgrade has already pushed sentiment in a more positive direction, the fact that the P/E still hovers near this tailored fair range suggests investors are recognising better earnings potential without moving the stock into an obviously expensive bracket. Explore the numbers behind NatWest Group's P/E valuation.
The NatWest Group Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Community page pick up where this valuation puzzle leaves off by spelling out what kind of growth, margins and earnings profile NatWest Group would need for the share price to look meaningfully higher or lower than today. Each scenario ties a fair worth estimate to a clear storyline about NatWest Group's potential catalysts and key risks so you can track over time which version of events is actually unfolding.
One of the top community narratives on NatWest Group: 16% undervalued
"The key requirement is that NatWest Group successfully absorbs Evelyn Partners and continues to grow fee based wealth and private banking…"
Discover why this Narrative puts NatWest Group at 16% undervalued.
One more piece of the NatWest Group puzzle before you decide
Valuation only shows what the market is willing to pay today, while professional projections hint at where they think NatWest Group could be a few years from now. Explore where analysts expect NatWest Group to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com