


How Investors Are Reacting To Summit Therapeutics Stock Phase III Cancer Trial Collaboration
- Summit Therapeutics announced that AstraZeneca and Daiichi Sankyo entered into a clinical collaboration to test Datroway with ivonescimab across several tumour types. The collaboration will start with a Phase III trial in first line triple negative breast cancer, with each partner supplying its own drug and sharing trial costs while retaining product rights.
- The arrangement ties Summit Therapeutics directly into AstraZeneca and Daiichi Sankyo’s antibody drug conjugate pipeline. This could reshape how investors think about Summit’s role in combination cancer therapies and its ability to participate in larger partner led development programs.
- We will now look at how Summit Therapeutics’ investment narrative could be influenced by this Phase III combination trial collaboration.
See how Summit Therapeutics fits into the broader oncology opportunity set by comparing it with our hand picked 34 healthcare AI stocks that are also focusing on partnerships and complex pipelines.
What Is Summit Therapeutics' Investment Narrative?
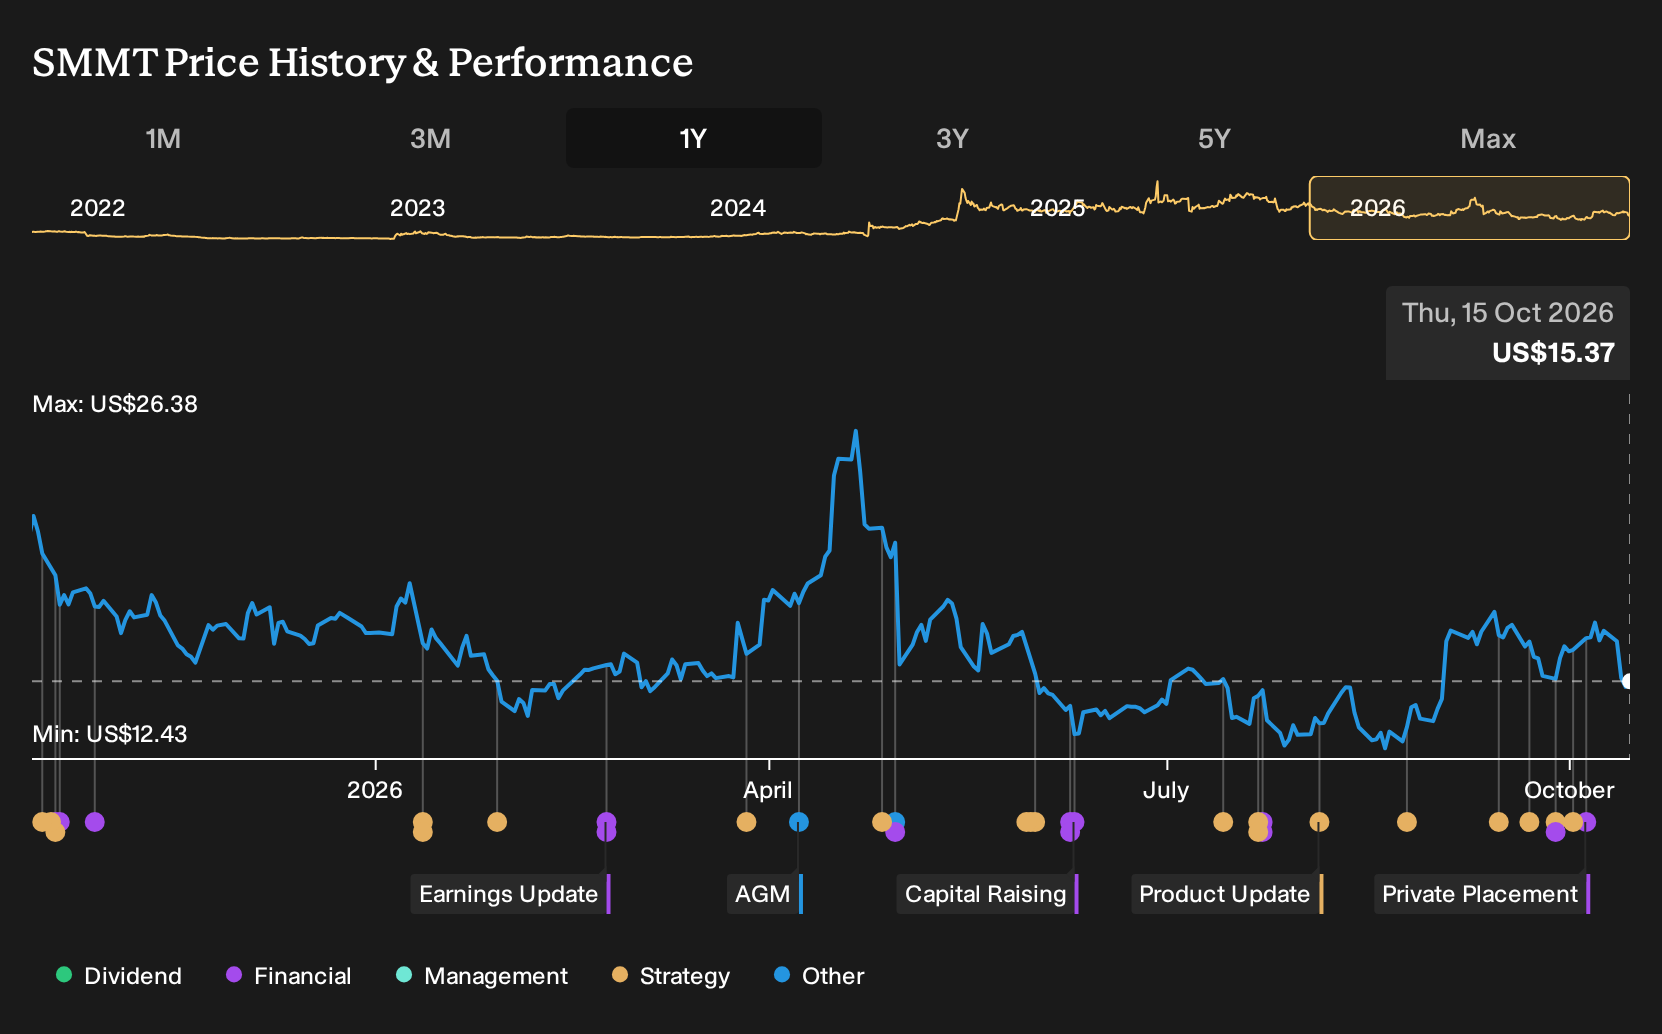
To own Summit Therapeutics, you have to buy into a high risk, high dependency story. The business currently reports no revenue and a loss of US$856.1 million, so everything hinges on execution in the clinic and on partnerships converting into future commercialization. The new Datroway and ivonescimab collaboration, along with AstraZeneca’s equity investment and the October 5 private placement, helps address funding needs for capital intensive late stage trials, but it does not change the fact that Summit is still forecast to remain unprofitable over the next 3 years.
In the short term, the big swing factors are clean progress in the multiple Phase III ivonescimab programs, the pace at which AstraZeneca and Daiichi Sankyo move combination studies forward, and how efficiently Summit deploys fresh capital. The stock has had a volatile year, with the share price down 30% over 12 months and still trading well below one external estimate of fair value, yet carrying a rich P/B of 19.5x versus 1.9x for US biotech peers. That mix of high clinical ambition, minimal current revenue and premium book valuation is where the real risk sits.
Even so, there is a specific pressure point in the Summit Therapeutics story that only becomes clear once you look at ...
There's only one way to know the right time to buy, sell or hold Summit Therapeutics. Head to Simply Wall St's company report for the latest analysis of Summit Therapeutics's Fair Value.
Exploring Other Perspectives
While the main story around Summit Therapeutics focuses on big combination trials, the most cautious analysts focus on execution risk. They were only projecting revenue of about US$16.8 million and earnings of roughly US$2.9 million by 2029, which is far more conservative. Use that gap to test how this new collaboration might reshape your own view.
Explore 4 other Summit Therapeutics fair value estimates, including one that suggests as much as 23% downside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Summit Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Summit Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Summit Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Summit Therapeutics?
Once you have formed a view on Summit Therapeutics, it can help to set that thesis alongside other opportunities that match your risk tolerance, income needs, and time horizon. The Simply Wall St Screener is built for exactly that kind of side by side comparison.
- If you want potential upside with smaller market values, scan for higher risk opportunities using our 13 elite penny stocks with strong financials that already show stronger balance sheets than many peers.
- For readers who prefer quality at a reasonable entry point, focus on businesses trading below their assessed value through the 33 high quality undervalued stocks that combine solid finances with attractive pricing.
- If steady income matters more than fast capital gains, narrow your search to resilient cash generators using the 8 dividend fortresses that aim to pair higher yields with durable fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com