


Arcus Biosciences (RCUS) And The Casdatifan Case As Fair Value Comes Into Focus
Arcus Biosciences (RCUS) has drawn fresh attention after recent trading left the stock at US$22.82. Short term moves have been mixed, and longer term returns have shown a wide range of outcomes for shareholders.
Recent trading action leaves Arcus Biosciences with a 1-day share price return of 1.29%, yet momentum has faded over the past quarter with a 90-day share price return down 16.62%. Even so, the 1-year total shareholder return of 37.47% points to a very different experience for longer term holders.
Spot potential follow throughs or reversals by lining Arcus Biosciences up against a hand picked set of 33 high quality undervalued stocks.After a sharp pullback from recent highs but a strong 1 year run, Arcus Biosciences now forces a choice. Step in at today’s US$22.82, or wait and hope the valuation gives more ground.
Most Popular Narrative: 43% Undervalued
Against the last close at US$22.82, the most widely followed narrative pegs Arcus Biosciences at a fair value of about US$39.91, which implies a large gap that rests on ambitious growth, margin and valuation assumptions playing out over time.
Arcus Biosciences is prioritizing the launch of its late-stage development program for the HIF-2 alpha inhibitor, casdatifan, which has shown significant efficacy differentiation relative to existing market competitors. This could enhance future revenue through competitive advantage in the RCC market.
See why 10 investors see Arcus Biosciences as 43% undervalued.
This storyline uses a 7.6% discount rate and assumes Arcus Biosciences eventually reaches US$290.3 million in revenue and US$50.1 million in earnings by around 2029, then trades on a P/E of 155x those earnings to justify the US$39.91 fair value. Those figures also build in analyst expectations that revenue could grow 35.4% annually over the next three years, that margins move from a current loss of US$460.0 million toward industry averages, and that the share count rises about 7% per year as the pipeline is funded.
Other parts of the same framework pull in risks around regulatory decisions for casdatifan and domvanalimab, possible side effect profiles relative to competing therapies, and pressure from rivals such as Merck in renal cell carcinoma. The fair value outcome sits well above today’s price, yet it also relies on successful data updates, regulatory approvals and commercial execution across several cancer settings where competition is already active.
Result: Fair Value of $39.91 (UNDERVALUED)
Still, the whole Arcus Biosciences story can be knocked off course if key casdatifan or domvanalimab trial readouts disappoint, or if regulators slow approvals.
Find out about the key risks to this Arcus Biosciences narrative.
Another View: Multiples Push Back On The Arcus Biosciences Story
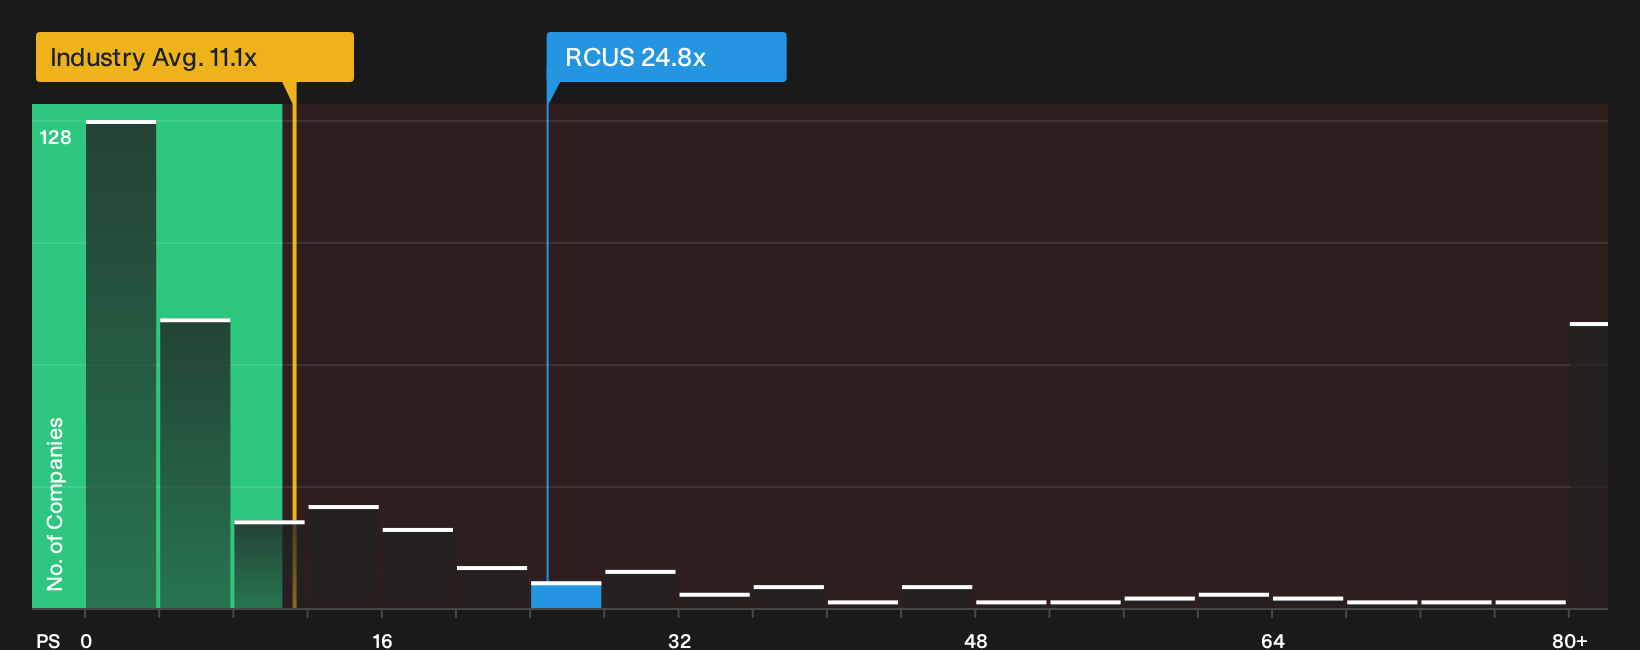
The analyst narrative and fair value work up frame Arcus Biosciences as materially undervalued at US$22.82. A simple revenue based lens tells a very different story. At a P/S of 24.8x, the stock trades well above the US Biotechs average of 10.9x, its peer group at 14.3x, and an estimated fair ratio of just 0.2x. That gap points to sizeable valuation risk if sentiment or growth expectations reset. This raises an important question: which signal should investors treat as their anchor?
For a closer look at how this revenue multiple compares with peers and where a fair ratio might pull the valuation over time, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Seeing both optimism and concern around Arcus Biosciences in this article, move quickly to pressure test the bullish and cautious angles against the underlying data. To weigh those trade offs for yourself, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Arcus Biosciences?
Do not stop your research with Arcus Biosciences. Use the Simply Wall Street Screener to compare other opportunities by quality, risk profile and income potential across the market.
- Spot potential mispricings early by scanning a curated set of 33 high quality undervalued stocks. These combine stronger fundamentals with more attractive entry points.
- Strengthen the defensive side of your portfolio by focusing on a list of solid balance sheet and fundamentals (25 results) so short term shocks hurt less when markets turn.
- Aim for steadier income by reviewing a hand picked group of 8 dividend fortresses. These concentrate on higher yields with robust underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com