


Wolfspeed (WOLF) Stock Looks Above Fair Value After Its 37% Rise
Wolfspeed has had a choppy run, with the share price up 36.9% year to date even as shorter term moves have been more volatile. This puts fresh attention on whether the current valuation lines up with the revenue the company is actually generating. With investors digesting big funding news and fresh supply agreements, the live question is how much of Wolfspeed's sales story is already reflected in the stock.
- The 36.9% gain year to date means a lot of optimism is now embedded in Wolfspeed's market value. The key issue is how well that enthusiasm matches the underlying level of sales.
- A conditional US$1.5b, 30 year loan commitment from the U.S. Department of Defense, along with an expanded silicon carbide wafer supply deal with Infineon, can influence how investors think about Wolfspeed's future revenue base and the timing of cash generation needed to support that capital.
- Your read on Wolfspeed is one view; the desks covering it have another. See what analysts think Wolfspeed's shares could be worth.
The issue now is whether the current Wolfspeed share price is justified by its sales when set against the Fair Ratio benchmark.
If you are weighing Wolfspeed against other ways to play this theme, it can help to see how it stacks up beside 94 AI infrastructure stocks.
Has Wolfspeed Run Too Far on Sales?
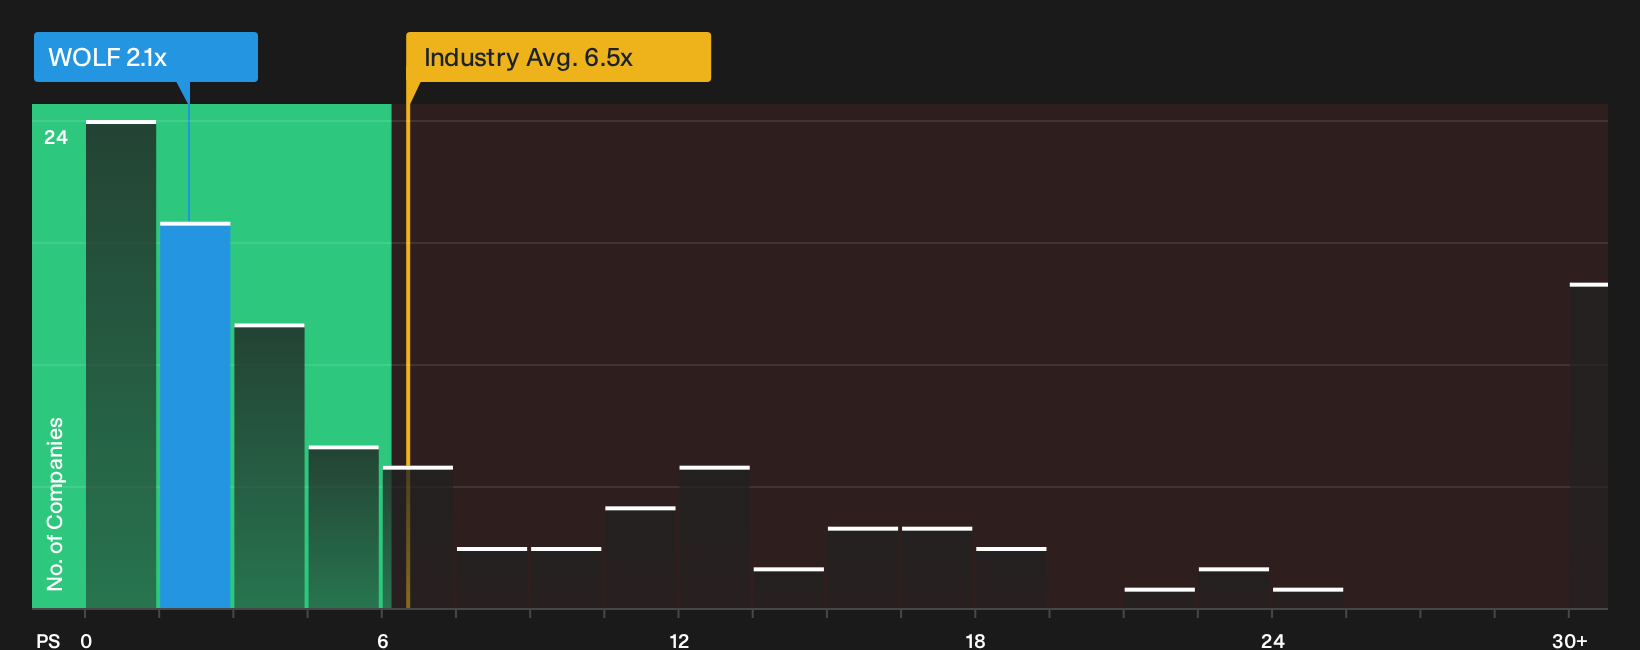
P/S is often a cleaner guide for Wolfspeed because the company is still reporting losses and the P/E ratio is less informative in that context. On this yardstick, the stock trades on a P/S of 2.1x, which is well below the semiconductor industry average of 6.5x and below peers around 7.0x.
Once the Fair Ratio is factored in, which adjusts for Wolfspeed's own growth profile, margins, size and risk, the current 2.1x P/S screens as overvalued on this framework despite looking cheap against raw sector multiples. Because the conditional US$1.5b Department of Defense loan and expanded Infineon wafer agreement have already sharpened the story around future sales capacity, the gap suggests the share price is already giving that revenue opportunity plenty of credit. Explore the numbers behind Wolfspeed's P/S valuation.
The Wolfspeed Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Wolfspeed valuation puzzle leaves off by spelling out which paths for growth, profitability and earnings would need to hold for the stock to be worth materially more or less than it is today on the market. Each narrative ties a fair value estimate to a specific version of Wolfspeed's potential catalysts and key risks so you can track over time which storyline seems closest to reality.
Community views on Wolfspeed split between those who see long-term silicon carbide upside being underappreciated and those who think execution risks keep enthusiasm in check.
Bull case: 6% undervalued
"Wolfspeed's vertically integrated 200 millimeter capability and early engineering sample shipments can support higher wafer output per tool, which can help gross margin and earnings..."
Discover why this Narrative puts Wolfspeed at 6% undervalued.
Bear case: roughly fairly valued
"Current gross margins remain negative and factory underutilization is still the main drag, so any delay in customers moving from evaluation to volume orders could limit improvement in net margins and EBITDA..."
Explore why this Narrative puts Wolfspeed at roughly fairly valued.
One more Wolfspeed check before you move on
Price multiples and storylines only go so far, because professional coverage also sketches out where this business could be a few years from now and how that stacks up to today's tag. Explore where analysts expect Wolfspeed to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com