


Toho (TSE:9602) Stock Price Reflects Q2 Results And Margin Pressure
Toho stock closed today at ¥1,527.5, capping a choppy few weeks that left the share price down about 4% over the past month, even as the latest Q2 2027 report hit the tape. The headline number was clean. Basic earnings per share landed at ¥14.20 on revenue of ¥96,420m, solid figures for a content and cinema group under close scrutiny on profitability.
Short term traders are reacting to price swings. Long term holders are weighing those earnings against a trailing net margin of 10.8% and a market value that already sits above one prominent DCF estimate.
Like the earnings profile at Toho but uneasy about paying up when the market value already leans ahead of at least one DCF view? Check out the 14 high quality undervalued stocks for a list of stocks that pair established profitability with valuation support that looks tighter on the numbers.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥96,420m vs. ¥106,799m (down about 10%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥11,823m vs. ¥21,885m (down about 46%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥14.20 vs. ¥25.81 (down about 45%)
- Trailing Net Profit Margin (Latest vs. 12 Months Ago): 10.8% vs. 14.8% (margin has compressed)
Prefer clear visuals instead of another wall of earnings tables and margin figures? View Toho's complete picture, including how its valuation compares with the latest results, in an interactive company report for Toho.
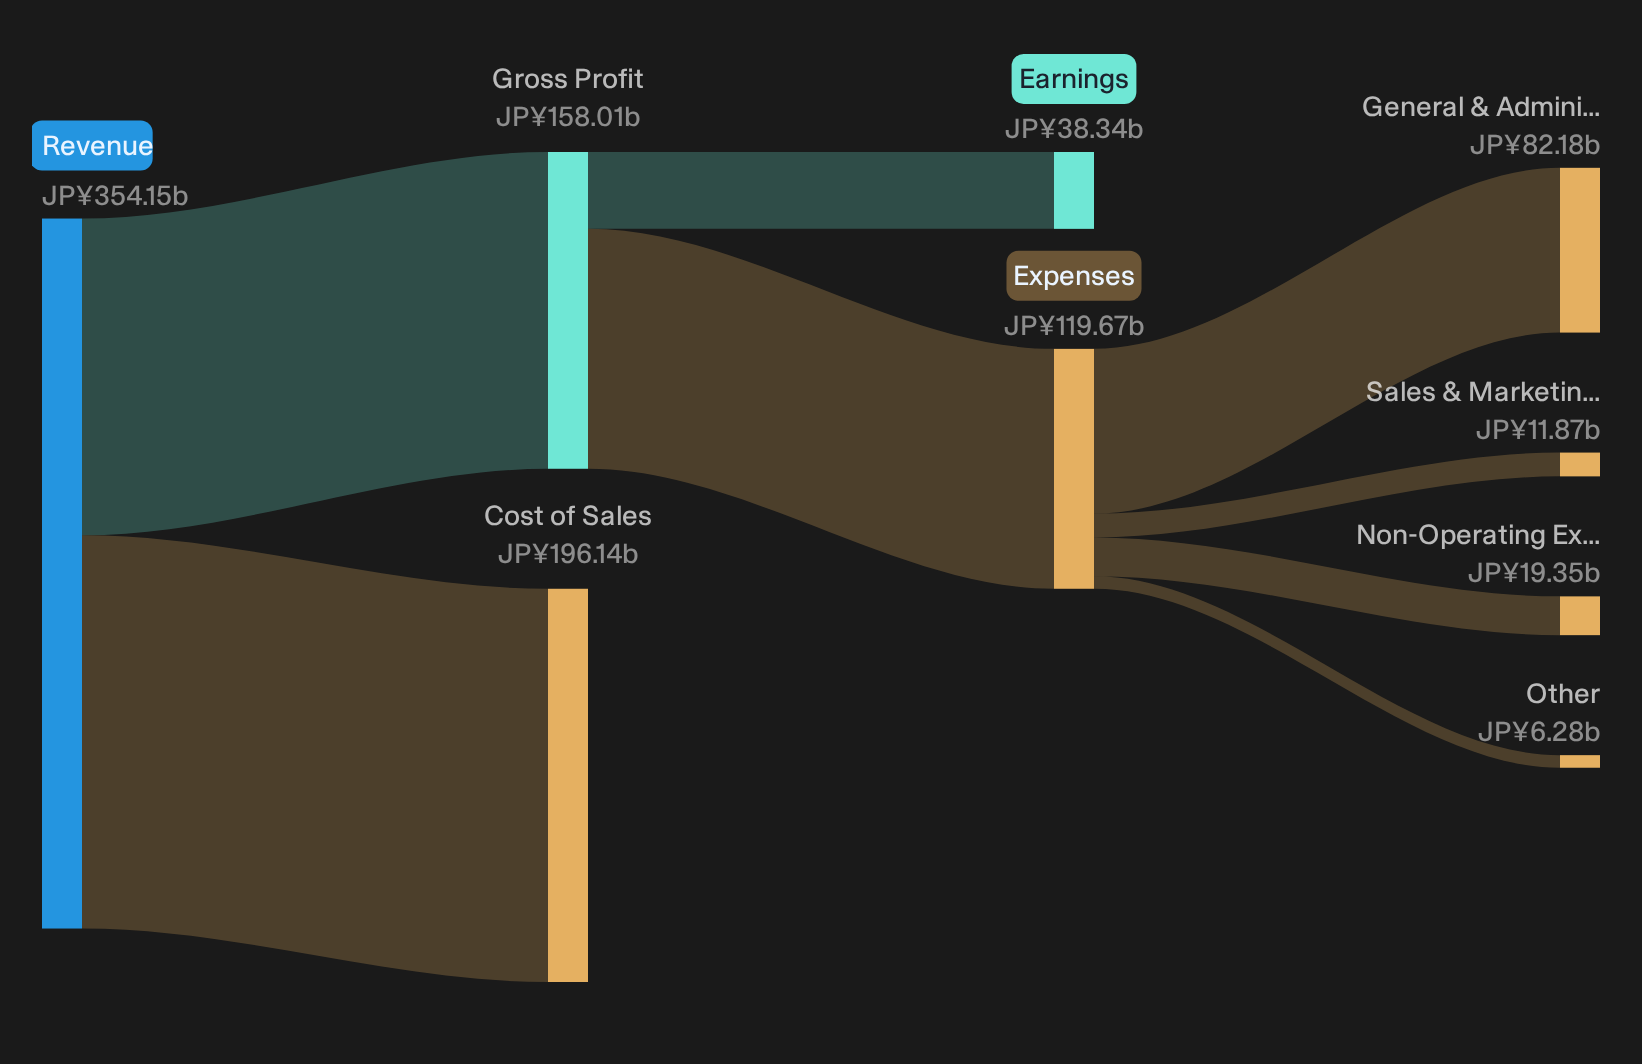
Toho bull story meets softer earnings base
Toho is pitched as a content and IP platform that can feed multiple revenue streams. The latest quarter shows that machine running less smoothly. Revenue fell about 10% and basic EPS declined about 45%, which sits awkwardly against a story built on strong monetisation of franchises and cinema recovery. The upgraded full year guidance is tied to gains on investment securities rather than operating strength. That supports the idea of financial flexibility, but it does not clearly back a near term growth narrative in the underlying entertainment engine.
Weaker margins give bears more ammunition
Bears who worry about cyclicality in film and cinema get some backing here. Net income excluding extra items dropped about 46% year on year and the trailing net margin moved from 14.8% to 10.8%. That squeeze suggests content and theatre results have hit a softer patch despite prior momentum around titles like the Chiikawa film. On the other hand, guidance was raised on investment gains, which hints at a solid balance sheet position. The near term risk looks more about earnings quality and volatility than about financial strain.
With earnings growth expectations pulling against a thinner 10.8% margin and a share price above DCF value, it is useful to verify the balance sheet story. Check the real liquidity and debt picture in our financial health analysis of Toho stock.Hunt For Mispriced Earnings Power
Toho just showed how a clean headline can still leave investors debating what they are really paying for. The real opportunity is spotting stocks that could be undervalued before the market closes the gap.
- Company 1 - 36% below our estimate - designs and maintains air and water systems that critical facilities upgrade long before comfort issues show up.
- Company 2 - 41% below our estimate - expands lending and deposit services as smaller business clients consolidate relationships into a single primary bank partner.
- Company 3 - 34% below our estimate - sells low code workflow tools that teams adopt once shared spreadsheets start breaking their daily processes.
Three companies from the same screener. Open every one of the 14 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com