


Will International Banking Expansion Change Huntington Shares Ahead Of Earnings?
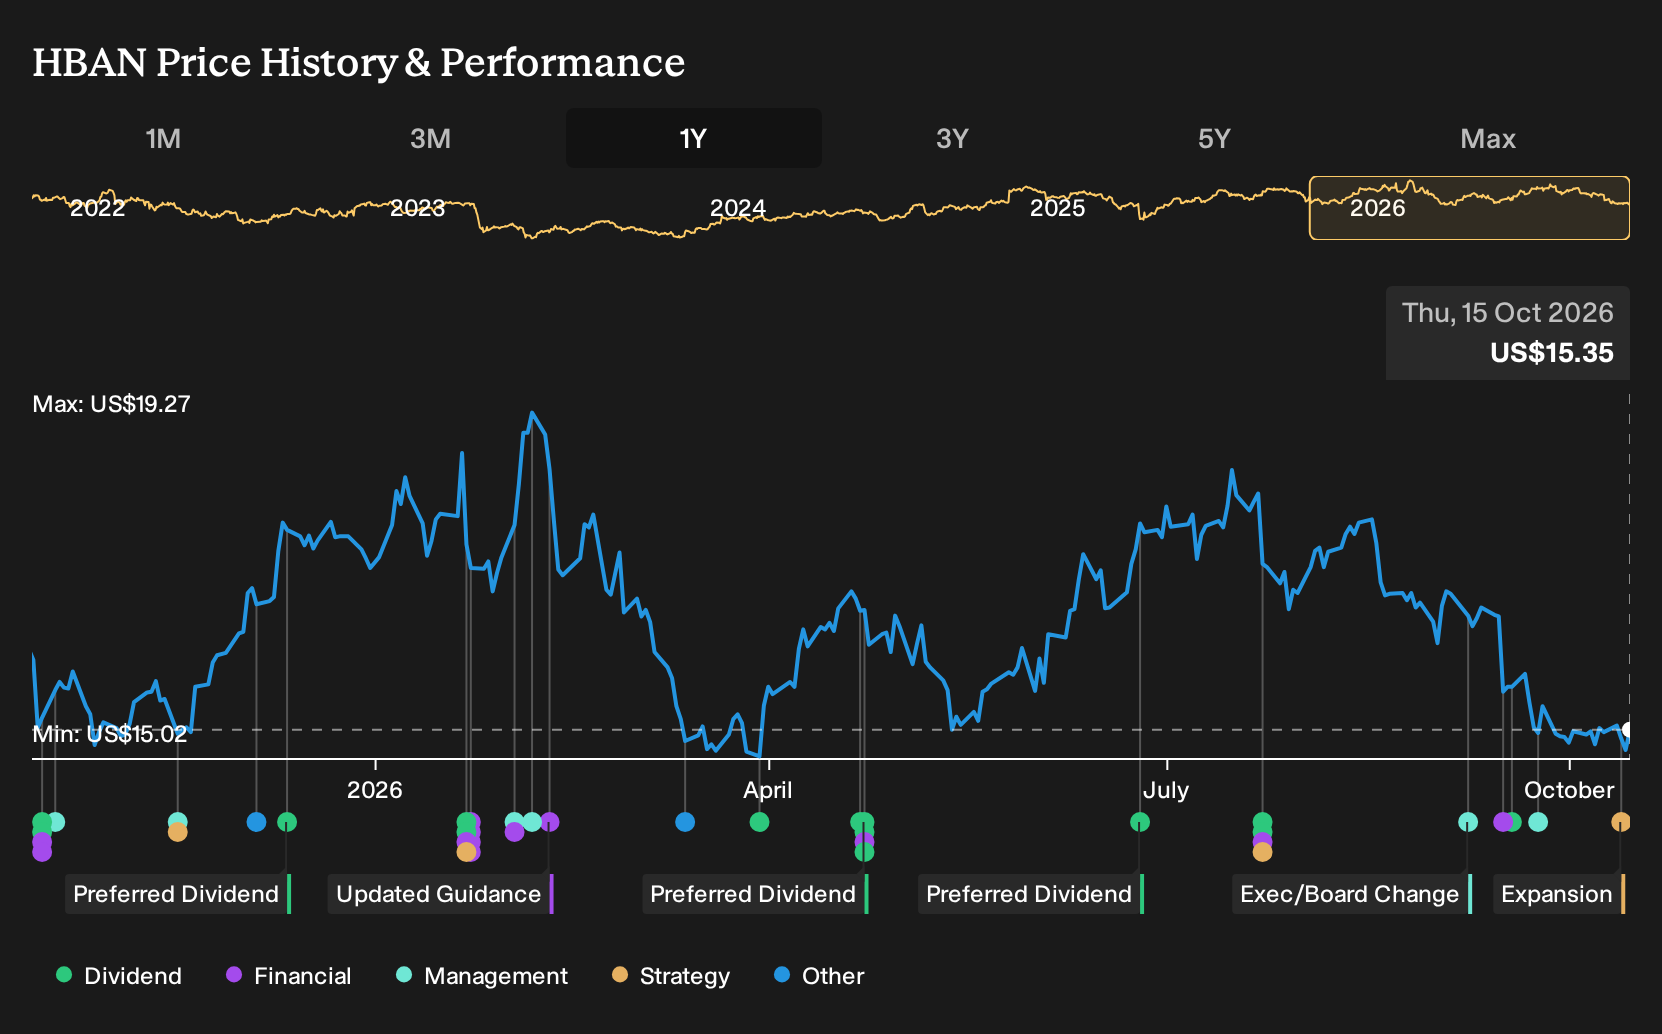
- Huntington Bancshares has already expanded its corporate, specialty and government banking division by creating an international corporate banking group focused on U.S. subsidiaries of foreign multinationals, offering lending, global trade, FX, cross border payments and treasury services, with a representative office in London planned to support business development.
- The build out of international corporate banking adds another fee oriented, cross border service layer on top of Huntington Bancshares’ existing commercial and capital markets offerings, which can influence how investors think about its mix between spread based lending and transaction driven income.
- We will now look at how Huntington Bancshares’ new international corporate banking focus could shape its investment narrative and earnings setup.
Scan other banks aiming to build fee income and cross border capabilities alongside Huntington Bancshares by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
Huntington Bancshares Investment Narrative Recap
To own Huntington Bancshares, you need to be comfortable with a regional bank leaning hard into fee income and partnerships while managing pressure on net interest income and return targets that were already reset lower into 2027. The new international corporate banking push fits that story, but it does not change the near term swing factor. The key remains execution on earnings and efficiency.
The key near term risk still sits with funding costs, deposit pricing and whether fee revenue and cost saves offset margin pressure. Earnings for the September 2026 quarter are expected to show lower profits on higher revenue, so any surprise around credit costs or expense control could matter more for the stock reaction than this expansion announcement.
The most relevant recent update for this story is the planned London representative office and the broader international corporate banking buildout. For Huntington Bancshares, that is an operational bet on cross border payments, FX and trade services that line up with its stated goal of growing noninterest income faster than the balance sheet.
This move also intersects with existing catalysts from Veritex and Cadence, where management is targeting US$600 million of cumulative revenue synergies through 2028 and has fee engines in payments and capital markets already running. The risk is that layering on international capabilities adds complexity and cost just as net interest income guidance sits near the lower end of prior expectations. This increases the execution bar for management.
Huntington Bancshares’ analyst narrative points to revenues of US$13.8b and earnings of US$4.4b by 2029, based on assumed yearly revenue growth of 14.5% and an earnings increase of about US$2.2b from earnings today of roughly US$2.2b.
Uncover why Huntington Bancshares' fair value indicates a 26% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly US$19.38 to US$31.30, which leaves a wide gap in how retail contributors frame Huntington Bancshares today. Before the London buildout and international push are reflected in these views, there are still funding cost pressures and earnings guidance risks shaping how the stock trades. That mix means opinions can differ sharply, so explore several Community viewpoints before deciding how this setup fits your portfolio.
Explore another Huntington Bancshares fair value estimate, including one that suggests it could be worth just $19.38!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Huntington Bancshares research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Huntington Bancshares. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Huntington Bancshares' overall financial health at a glance.
Looking for more investment ideas beyond Huntington Bancshares?
Once the Huntington Bancshares story is on your radar, it can help to line it up against a wider set of opportunities. The Simply Wall St Screener is built for that kind of side by side comparison so you can see which other companies match the income, quality or balance sheet profile you want.
- If you want potential value candidates with quality fundamentals already in place, start with 33 high quality undervalued stocks that share solid cash generation and balance sheets.
- For investors who care most about resilience and capital preservation, filter for 32 resilient stocks with low risk scores that score well on financial strength and volatility measures.
- If the aim is to uncover less crowded opportunities, scan through 20 high quality undiscovered gems that might not yet be widely followed but still show healthy fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com