


Top 3 Drone Defense Stocks To Watch In October 2026
G7 finance leaders just agreed to run joint exercises against AI driven cyber attacks, and that shines a spotlight on one quiet corner of defense. Governments want reliable partners that can secure skies and networks without worrying about stretched balance sheets or fragile cash piles. That is where financially resilient drone defense specialists come in. This article walks through three such stocks drawn from our high quality security screener.
The three examples in this piece are only a starter set from the idea, and the full screen surfaced 11 more drone defense stocks with equally compelling financial stories that are not covered below. If you want to quickly identify stronger balance sheets and lower funding risk across the sector, head straight to the Financially Strong Drone Defense Stocks screener.
Red Cat Holdings (RCAT)
Red Cat Holdings is building a suite of military grade drones and uncrewed surface vessels that fit directly into the Financially Strong Drone Defense Stocks theme, putting its battlefield focused hardware and software in front of U.S. and allied defense buyers.
Red Cat designs and builds tactical unmanned aircraft systems such as BLACK WIDOW, TEAL 2, FANG FPV and THE EDGE 130, plus its BLUE OPS uncrewed surface vessel and Havoc powered autonomous maritime defense platform. All reported revenue of about $71 million comes from recreational products in the United States, and the company has a market value of roughly $722 million.
"Growing defense interest in autonomous systems, reflected in the U.S. Army focus on millions of drones and the President's budget reference to 2,250 SRR systems, supports volume visibility for Black Widow and FANG, which directly affects revenue durability and potential operating leverage."
How that expected demand filters through fixed factory costs and future contract mix is the unresolved pressure point that could reshape outcomes.
That contract mix question is exactly what the full narrative for Red Cat Holdings unpacks, including how Red Cat Holdings could see that operating leverage accelerate or stall under different funding paths.

Intuitive Machines (LUNR)
Intuitive Machines plugs into the Financially Strong Drone Defense Stocks theme through its Nova-C lander and Micro Nova Hopper. The company’s autonomous guidance, sensors, and AI-driven control systems for space missions echo the tech stack needed for counter drone and electronic warfare applications.
Intuitive Machines is a Houston based space infrastructure and services business that provides lunar transport, data transmission, and AI enabled command and control solutions. It generates about $490 million from aerospace and defense customers, with a market value near $2.5b.
"A key catalyst for the company in 2026 is IM-3 which is part of NASA’s Commercial Lunar Payload Services (CLPS) initiative; successfully landing IM-3 and its payload contents will hopefully be somewhat more straightforward than that of IM-2 and would hopefully give Intuitive Machines’ share price a substantial boost."
What really matters next is how one quiet shift in its funding mix and contract timing shapes the durability of that growth story.
That funding shift is exactly what the full narrative for Intuitive Machines unpacks. It reveals where contract timing, cash needs, and mission risk could be accelerating or masking Intuitive Machines’ trajectory.

Kratos Defense & Security Solutions (KTOS)
Kratos Defense & Security Solutions gives this screener a large cap anchor that actually builds and fields the unmanned jets and counter drone systems policymakers are talking about, which makes its balance sheet strength matter in a very practical way.
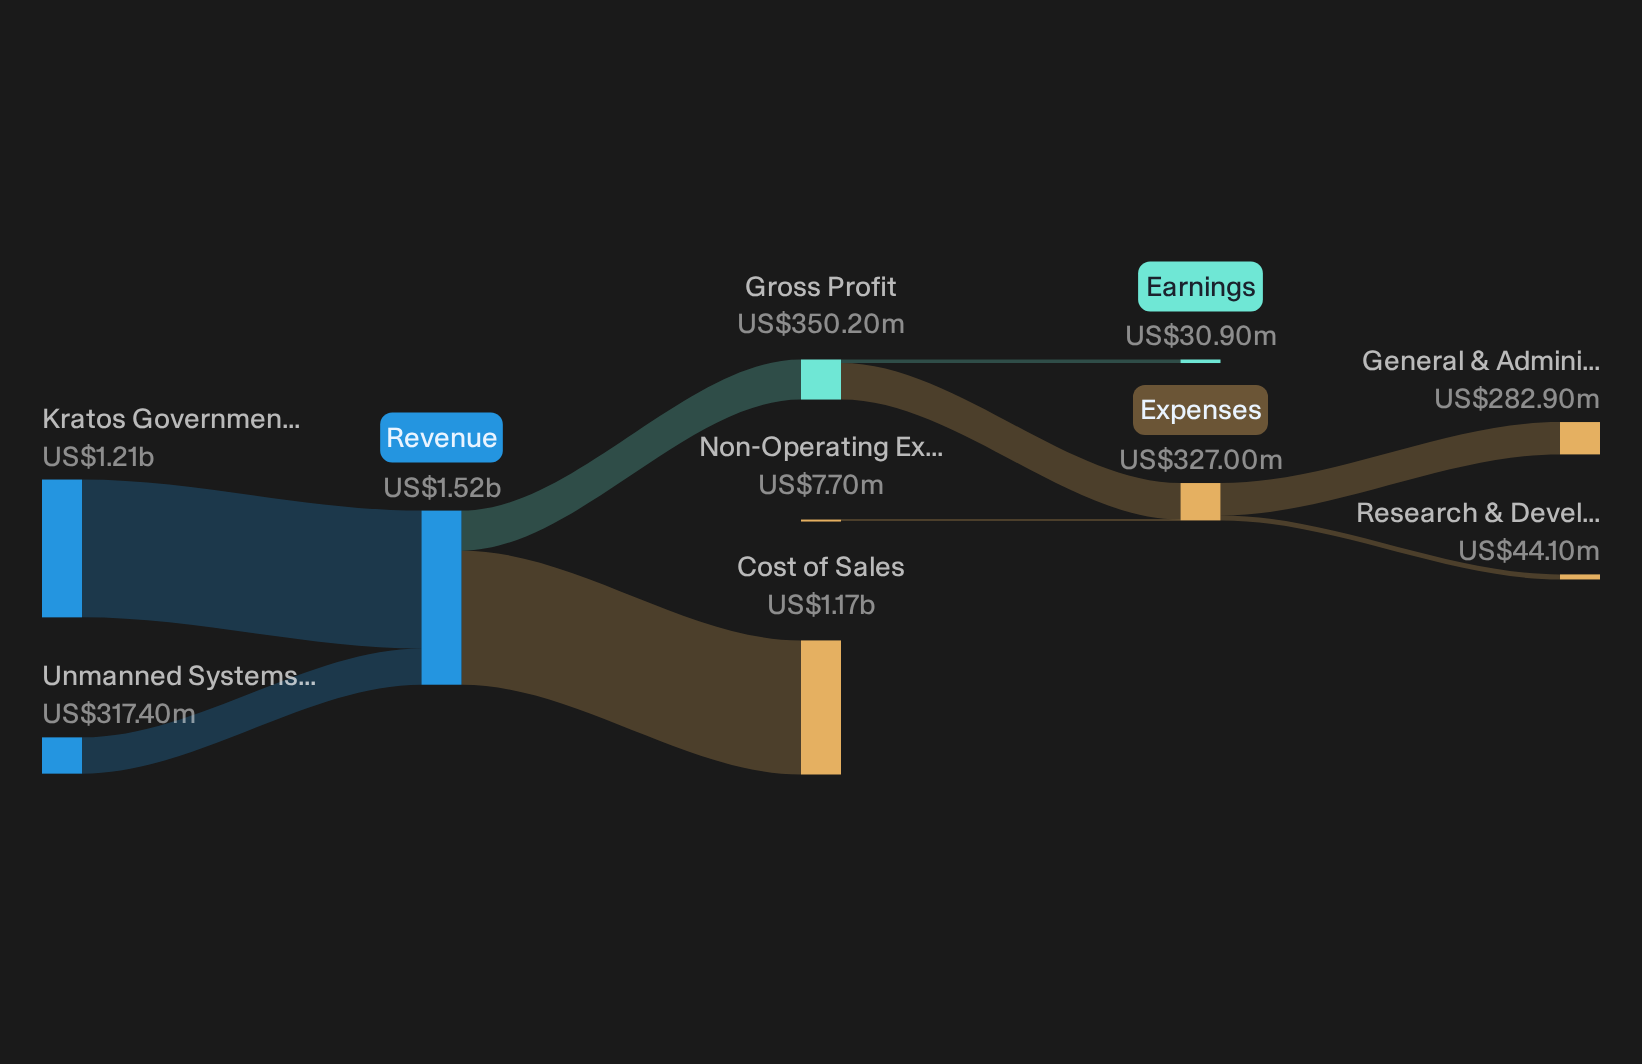
Kratos is a defense technology group whose Unmanned Systems arm, generating about US$317 million, develops jet powered drones and C UAS that directly fit the drone defense theme. Its Kratos Government Solutions division produces around US$1.2b from broader defense and space programs, giving the US$7.38b stock a diversified footing.
"While Kratos is positioning affordable unmanned systems and loitering munitions as high volume production businesses, large upfront engine and airframe component orders for thousands of units risk locking in inventory and fixed costs ahead of firm orders. This may keep working capital consumption elevated and delay any improvement in operating cash flow."
What happens to margins and cash generation if a single timing assumption on those high volume defense programs breaks will be crucial for investors.
That margin puzzle is exactly what the full narrative for Kratos Defense & Security Solutions pulls apart so you can see where Kratos Defense & Security Solutions’ cash profile risks are stalling or accelerating.
Seeking Fresh Alternatives Beyond Drones
Fresh ideas move first. Breakout trends, early momentum and under the radar quality often get caught late once headlines catch up. Scan these curated lists before the crowd and act now.
- Spot cash rich operators that can keep investing while weaker rivals stall by running the list of solid balance sheet and fundamentals (25 results) and focusing only on businesses with real financial resilience.
- Ride long term demand for automation and efficiency by checking the 91 robotics and automation stocks where carefully filtered companies are already building momentum behind the scenes.
- Position ahead of infrastructure spending cycles by reviewing the 41 power grid technology and infrastructure stocks and zeroing in on players tied directly to modern grid upgrades.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com