


AI Drug Candidate Might Change The Case For Investing In Sanofi (ENXTPA:SAN)
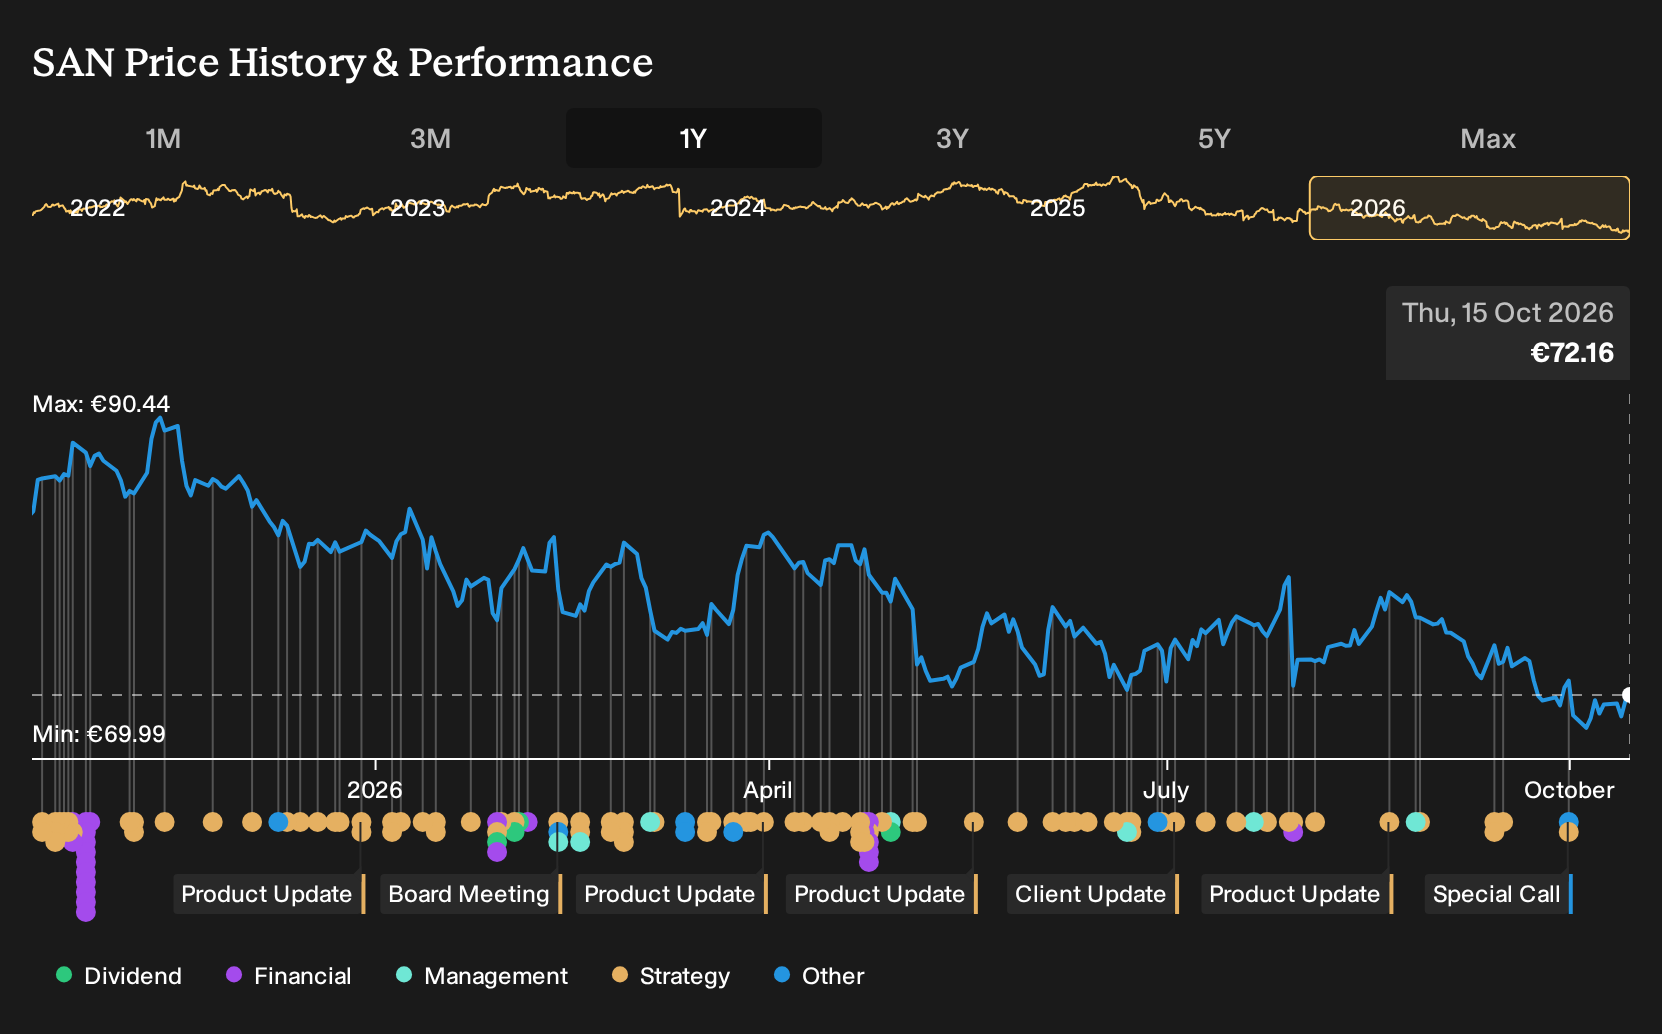
- On 15 October 2026, Recursion Pharmaceuticals announced that Sanofi had optioned the first development candidate from their AI-driven immunology collaboration. This triggered a $10 million milestone payment and added a potential first in class oral small molecule to Sanofi’s pipeline.
- Sanofi also signed a Letter of Intent with the pan Canadian Pharmaceutical Alliance for Dupixent across four additional indications. This underscores how the drug’s expanding reach in dermatology and respiratory care could influence the group’s mix of future immunology revenue.
- Next, the focus will be on how Sanofi's new AI discovered oral candidate might reshape the investment narrative built around disciplined R&D execution.
Compare Sanofi’s AI driven immunology push with other potential breakouts by scanning our hand picked 125 healthcare AI stocks, which are also building pipelines around data driven drug discovery.
Sanofi Investment Narrative Recap
To own Sanofi, you need to believe disciplined R&D and business development can refill the pipeline after several late stage terminations, while the rare disease, specialty medicines and Type 2 immunology portfolio keep doing the heavy lifting. The near term focus stays on execution, because earnings and profit margins have recently come under pressure.
The biggest short term swing factor is how effectively Sanofi converts its immunology and specialty pipeline into later stage assets that can offset weaker vaccines ambition and mixed past earnings. Key risk sits in pipeline execution and regulatory scrutiny in vaccines, and this week’s AI and Dupixent updates do not materially change that.
The Letter of Intent with the pan Canadian Pharmaceutical Alliance for Dupixent across four extra indications looks most relevant for near term catalysts. It ties directly to the existing €25b 2030 ambition around Dupixent and related Type 2 programs, because broader public plan access in a new set of uses can influence how durable that franchise proves.
For you as an investor, this agreement mainly speaks to execution and reimbursement risk. Wider potential coverage for pediatric atopic dermatitis, prurigo nodularis, severe chronic rhinosinusitis with nasal polyposis and COPD may support Dupixent’s role as Sanofi’s anchor therapy. At the same time, pressure in flu vaccines, dividend coverage and regulatory commitments remain key issues to watch around cash generation and capital allocation.
What The Sanofi Earnings Setup Implies
Sanofi's narrative projects €54.6b revenue and €10.9b earnings by 2029, based on analyst estimates. This assumes 3.7% yearly revenue growth and an earnings increase of about €7.0b from €3.9b today.
Uncover why Sanofi's fair value indicates a 30% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame Dupixent concentration as a catalyst rather than a risk for Sanofi, with their pre news views assuming revenue could reach about €56.4b and earnings about €13.2b by 2029. You can see how far that stretches the upbeat story and why opinions may shift after these updates.
Explore 7 other Sanofi fair value estimates, including one that suggests potential upside of up to 237% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sanofi research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sanofi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sanofi's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sanofi?
Once you have a view on Sanofi, it can help to compare that thesis with other opportunities filtered by the traits you care about most. The Simply Wall St Screener lets you scan the market quickly so you can focus on a tighter set of candidates instead of a huge watchlist.
- If you care about quality at a reasonable price, start with companies that currently screen as 198 high quality undervalued stocks and see which businesses line up with your return and risk preferences.
- If capital preservation comes first for you, focus on resilience by checking out a 225 resilient stocks with low risk scores that may better match a defensive playbook.
- If you want growth potential without ignoring fundamentals, broaden your research with a 613 high quality undiscovered gems that could sit alongside a core holding like Sanofi.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com