


How Stake Sale At BXP (BXP) Has Changed Its Investment Story
- BXP sold a 10.6% equity interest in its US$2b 343 Madison Avenue office development to AVRS Partners. BXP retains control and ongoing responsibility for development and leasing of the largely preleased Midtown Manhattan tower.
- The minority stake sale gives BXP added financial flexibility on a long-dated New York pipeline asset and deepens its relationship with a repeat capital partner in AVRS Partners.
- The next focus is how BXP's capital recycling narrative aligns with the 343 Madison Avenue stake sale to AVRS Partners.
Scan how BXP’s capital recycling move compares with other high quality real estate plays by running through our hand picked 33 high quality undervalued stocks.
BXP Investment Narrative Recap
BXP may appeal most to investors who think premier offices in key US cities can maintain tenant demand and support a long, gradual grind in occupancy and rents. The 343 Madison Avenue stake sale supports that view by sharing project risk and preserving control of a high end asset. In the near term, the bigger swing factor still appears to be leasing progress and rent terms across the broader portfolio.
The main operational risk continues to center on funding. Interest costs are already a pressure point, with earnings not fully covering payments, and future refinancings could tighten cash flow if rental income does not keep pace. This transaction supports liquidity but by itself is unlikely to change that core risk in a material way.
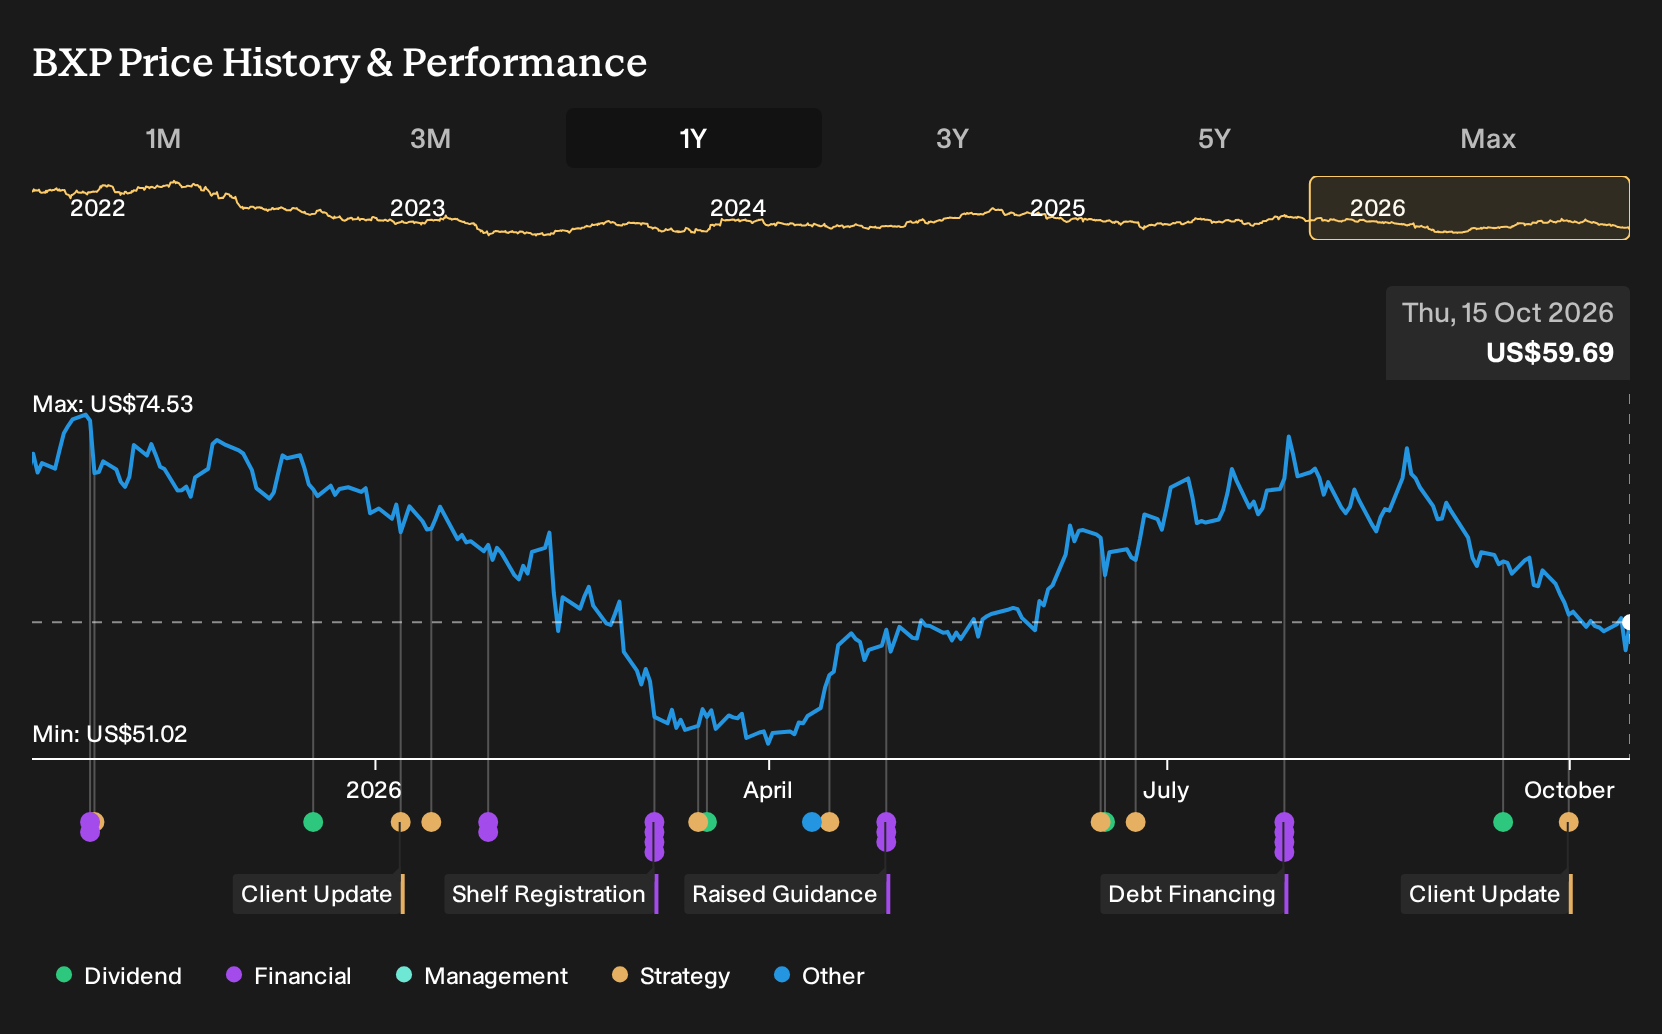
The latest 343 Madison Avenue update is one of the clearest recent markers for how BXP is managing its development pipeline. The tower is 56% preleased and planned to complete in 2029, so the operational focus is on execution over a long period rather than a rapid uplift. Investors are watching whether preleasing continues to build and whether the project remains on its current budget track.
This joint venture structure also connects directly to the existing catalyst narrative around capital recycling. BXP has already raised over US$1.2b toward a US$1.9b asset sale and recycling goal, and using minority interests at projects such as 343 Madison Avenue extends that playbook. For investors, the key question is whether this combination of asset sales and shared developments helps offset higher funding costs without weakening long term earnings power.
BXP's narrative projects US$3.8b revenue and US$345.9m earnings by 2029. Analysts are assuming 6.2% yearly revenue growth and an earnings increase of about US$49m from US$296.8m today.
Discover why BXP's fair value points to a 24% potential upside from its current price, a gap that could close quickly.
Exploring Other Perspectives
Some of the most optimistic analysts on BXP lean heavily on the development pipeline as a catalyst, expecting revenue to reach about US$3.8b and earnings of roughly US$427.9m by 2029. The 343 Madison Avenue stake sale could eventually reshape those views. Analyst opinions already vary widely, so treat this as a cue to compare multiple narratives.
Explore 3 other BXP fair value estimates, including one that suggests up to 52% potential upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your BXP research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for BXP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BXP's overall financial health at a glance.
Looking for more BXP-sized investment ideas?
Once you have a view on BXP, it helps to compare that thesis with a wider watchlist so you can see how other businesses stack up on quality, value, and risk.
- If you want potential mispriced leaders with solid fundamentals, run a sweep through our hand picked 33 high quality undervalued stocks.
- For investors who care most about balance sheet strength and durability, filter for companies in the list of solid balance sheet and fundamentals (25 results).
- If you prefer businesses with lower overall risk profiles and steadier characteristics, build a shortlist using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com