


Could New Steel Capacity Alter The Investment Case For SSAB (OM:SSAB A)?
- SSAB has started construction of a new SEK 3.3b quenching line in Oxelösund, adding about 100,000 tonnes of annual capacity for advanced wear and protection steels such as Hardox and Armox, with production targeted for 2030.
- The expansion deepens SSAB's focus on higher value specialty steels for industrial, safety, and defense uses. This can reshape its product mix and operational profile toward more technically demanding, less commoditised volumes.
- We will now look at how SSAB's investment narrative could be influenced by the new Oxelösund quenching line capacity expansion.
Scan other premium steel and industrial materials stocks that are positioned for similar shifts in high-specification demand with our curated list of 613 high quality undiscovered gems
SSAB Investment Narrative Recap
To own SSAB, you need to believe the business can keep shifting toward higher value special steels while managing a still tough global steel market. The Oxelösund quenching project backs that tilt to premium Hardox and Armox volumes, but with production aimed for 2030 it does little for near term demand, pricing or Q3 2026 results.
In the short term, the main swing factor remains European steel pricing and volumes, especially in construction and automotive. The biggest risk is that weak demand and ongoing import pressure hit margins just as SSAB carries high transformation capex and a relatively fixed cost base, which would squeeze cash flow and limit optionality.
The most relevant announcement alongside this investment is the upcoming Q3 2026 results presentation on 28 October. That update gives you a way to assess how SSAB is handling softer standard steel conditions while leaning harder into special steels and fossil free initiatives such as HYBRIT and SSAB Zero.
Watch for commentary on capex phasing, returns expectations for Oxelösund and other premium projects, and any adjustment to demand views in Europe and the US. Execution risk matters here, because large long dated projects can strain cash generation if pricing remains weak or if the shift toward higher margin products in segments such as SSAB Special Steels proves slower than planned.
SSAB's current analyst script points to SEK 115.9b in revenues and SEK 9.5b in earnings by 2029, built on 5.8% yearly top line growth and an earnings increase of SEK 3.9b from SEK 5.6b today.
Uncover why SSAB's fair value indicates an 11% potential upside to its current price before that discount to SSAB closes.
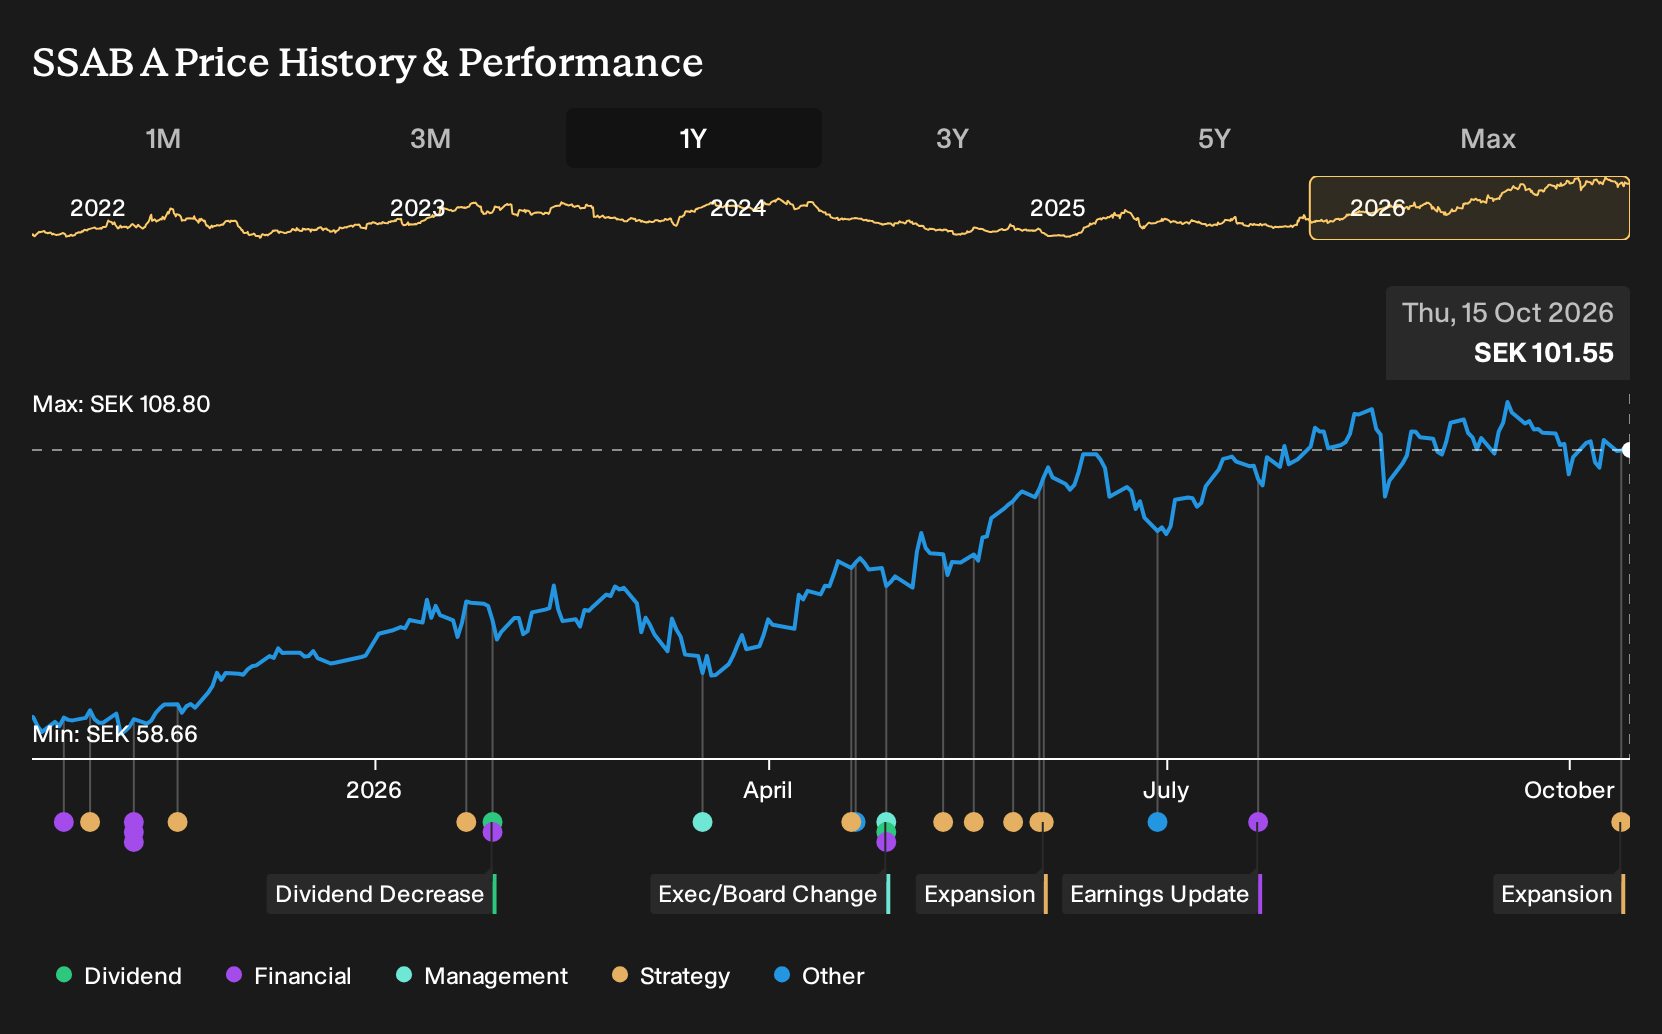
Exploring Other Perspectives
Some of the most optimistic analysts already expected SSAB to reach about SEK 143.8b in revenue and SEK 13.9b in earnings by 2029, largely on the back of premium steel capacity like Oxelösund. You now have fresh information that they did not. Use that gap to test how your own view might shift as forecasts get updated.
Explore 4 other SSAB fair value estimates, including one that indicates up to 13% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgement.
- A great starting point for your SSAB research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SSAB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SSAB's overall financial health at a glance.
Looking For More SSAB Investment Ideas?
If this SSAB story has you thinking about where else pricing power, balance sheet strength, or income resilience might matter, the Simply Wall St Screener is a useful place to start lining up other candidates that fit your checklist.
- For investors who want financial resilience to be front and center, focus on companies with robust balance sheets and solid fundamentals using our curated list of solid balance sheet and fundamentals (202 results).
- If downside protection matters most for you, narrow your universe to businesses with relatively low risk profiles through the tailored 225 resilient stocks with low risk scores.
- Those hunting for under-the-radar opportunities can concentrate on lesser known but fundamentally strong stocks with the focused 613 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com