


How Manufacturing Expansion Will Impact XPEL (XPEL) Investors
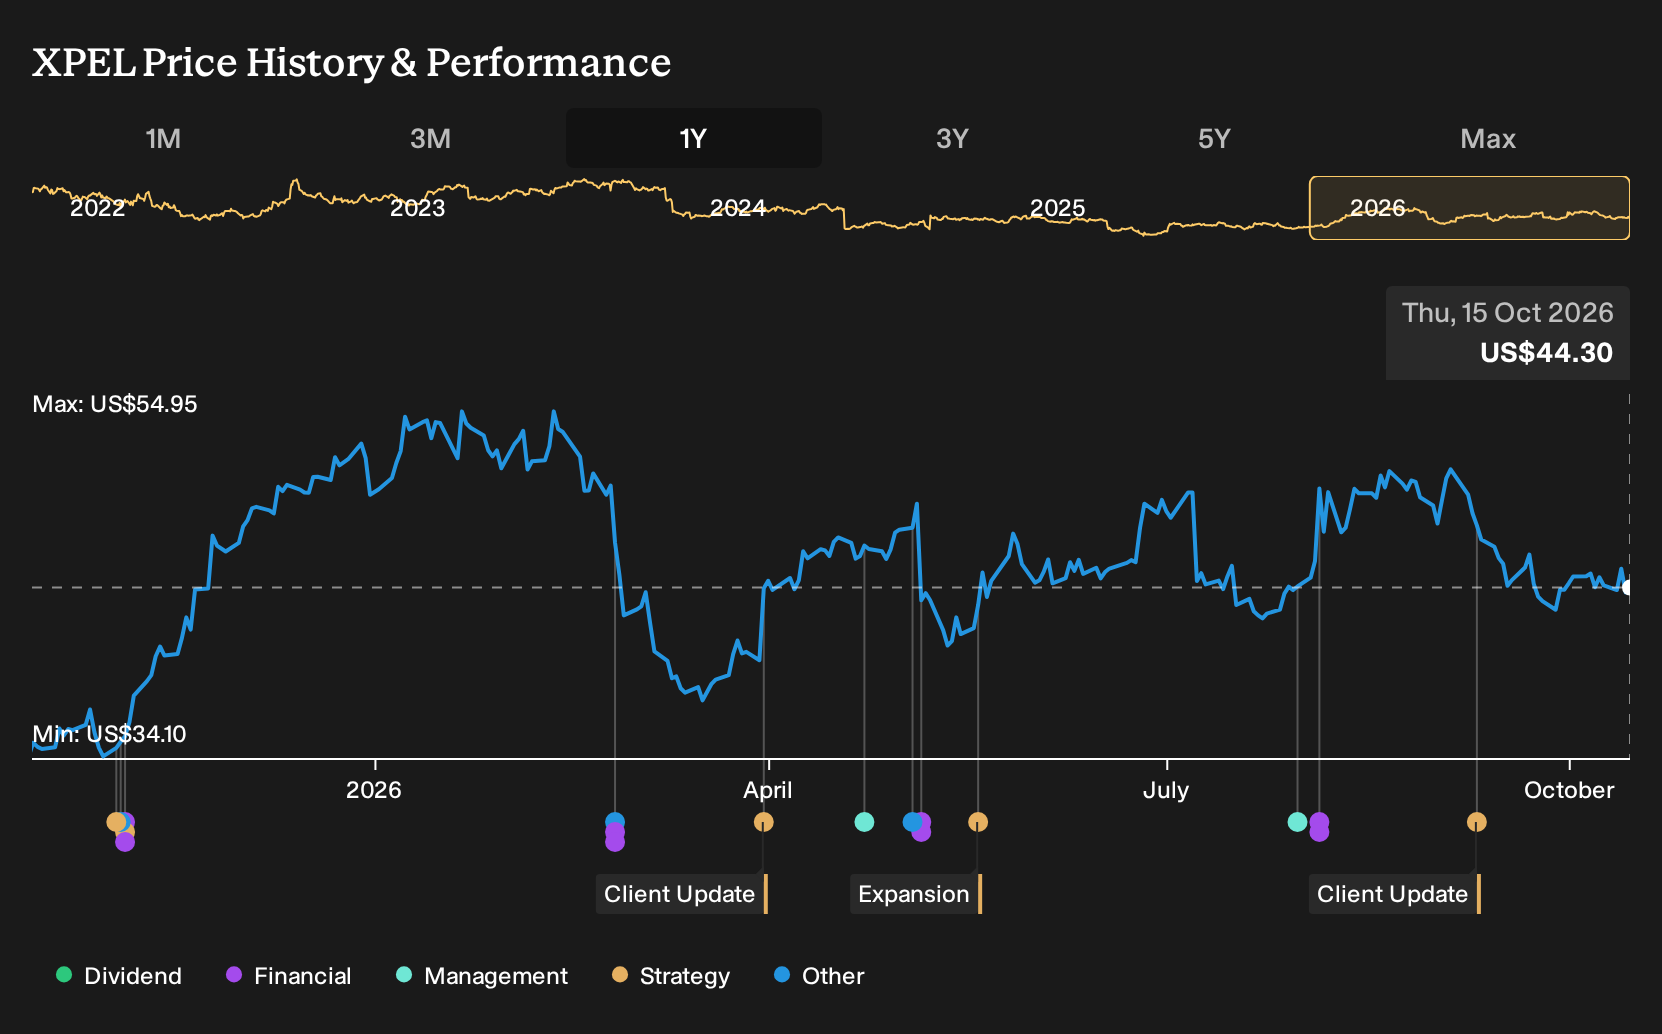
- XPEL has committed US$110 million to expand manufacturing in San Antonio and acquire a plant in China, reinforcing its focus on self healing paint protection film and related automotive films and services.
- The move shifts XPEL further toward vertical integration and higher margin product lines. This could reshape cost structure, pricing power, and how installation and OEM channels are supplied worldwide.
- This article examines how XPEL's investment narrative is influenced by this US$110 million manufacturing expansion and China plant acquisition.
Compare XPEL's renewed focus on higher margin auto films with a curated list of peers by scanning 20 high quality undiscovered gems that could also be quietly building durable, under-the-radar advantages.
XPEL Investment Narrative Recap
To own XPEL, you need to believe the business can keep building on a niche in protective films while shifting more of its mix toward higher margin window film and installation services. The manufacturing build out in San Antonio and China sits alongside that thesis, but the near term story still hinges on execution in core channels such as installers, dealers, and OEMs.
The most important short term swing factor is whether new capacity ramps cleanly without cost overruns or slow utilization, given the US$44.8 million term loan and US$110 million project pipeline. The biggest risk remains pressure on pricing and margins from lower cost Asian competitors if XPEL cannot defend product differentiation and service quality.
The US$110 million commitment to expand manufacturing and acquire a plant in China is the operational announcement that matters most here. It directly affects XPEL’s cost base, supply security, and ability to control product quality across self healing paint protection film, window film, and related offerings. It also transitions the business away from a lighter sourcing model toward deeper in house production.
For catalysts, that same project is central because a successful ramp could support higher margin contribution from window film and installation services, while better serving OEM and dealership programs across regions. The flip side is clear execution risk. Any material delay, weaker utilization, or operational hiccup would leave shareholders with higher interest expense and depreciation without the offsetting earnings benefit.
XPEL Consensus Forecasts In Context
XPEL's current analyst framework points to revenues of US$701.0 million and earnings of US$123.4 million by 2029. These figures are built on an assumed 11.3% yearly revenue growth rate and an earnings increase of about US$68.7 million from current earnings of US$54.7 million.
Uncover why XPEL's fair value indicates a 39% potential upside to its current price, which could narrow quickly if XPEL executes on this expansion plan.
Exploring Other Perspectives
One alternate view puts XPEL’s operating margin ambitions front and center. Bullish analysts were already modeling revenue of about US$767.8 million and earnings near US$139.3 million by 2029, compared with the consensus US$701.0 million and US$123.4 million. You can treat this US$110 million manufacturing push as a fresh test of which story proves closer to reality and explore how those forecasts might shift as new information lands.
Explore 2 other XPEL fair value estimates, including one that suggests up to 66% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your XPEL research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for XPEL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate XPEL's overall financial health at a glance.
Looking for more investment ideas beyond XPEL?
Once you have a view on XPEL, it may help to broaden your watchlist and see how similar or contrasting opportunities stack up using the Simply Wall St Screener.
- If you care most about resilient balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on financially sturdy businesses.
- If value is your priority, sort through a 33 high quality undervalued stocks that filters for quality companies trading below their estimated fair worth.
- If income is your anchor, zero in on a 8 dividend fortresses that highlights higher yielding payers with a focus on consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com