


Learn Why The Bull Case For CACI International Stock Could Change Following ARKA Acquisition
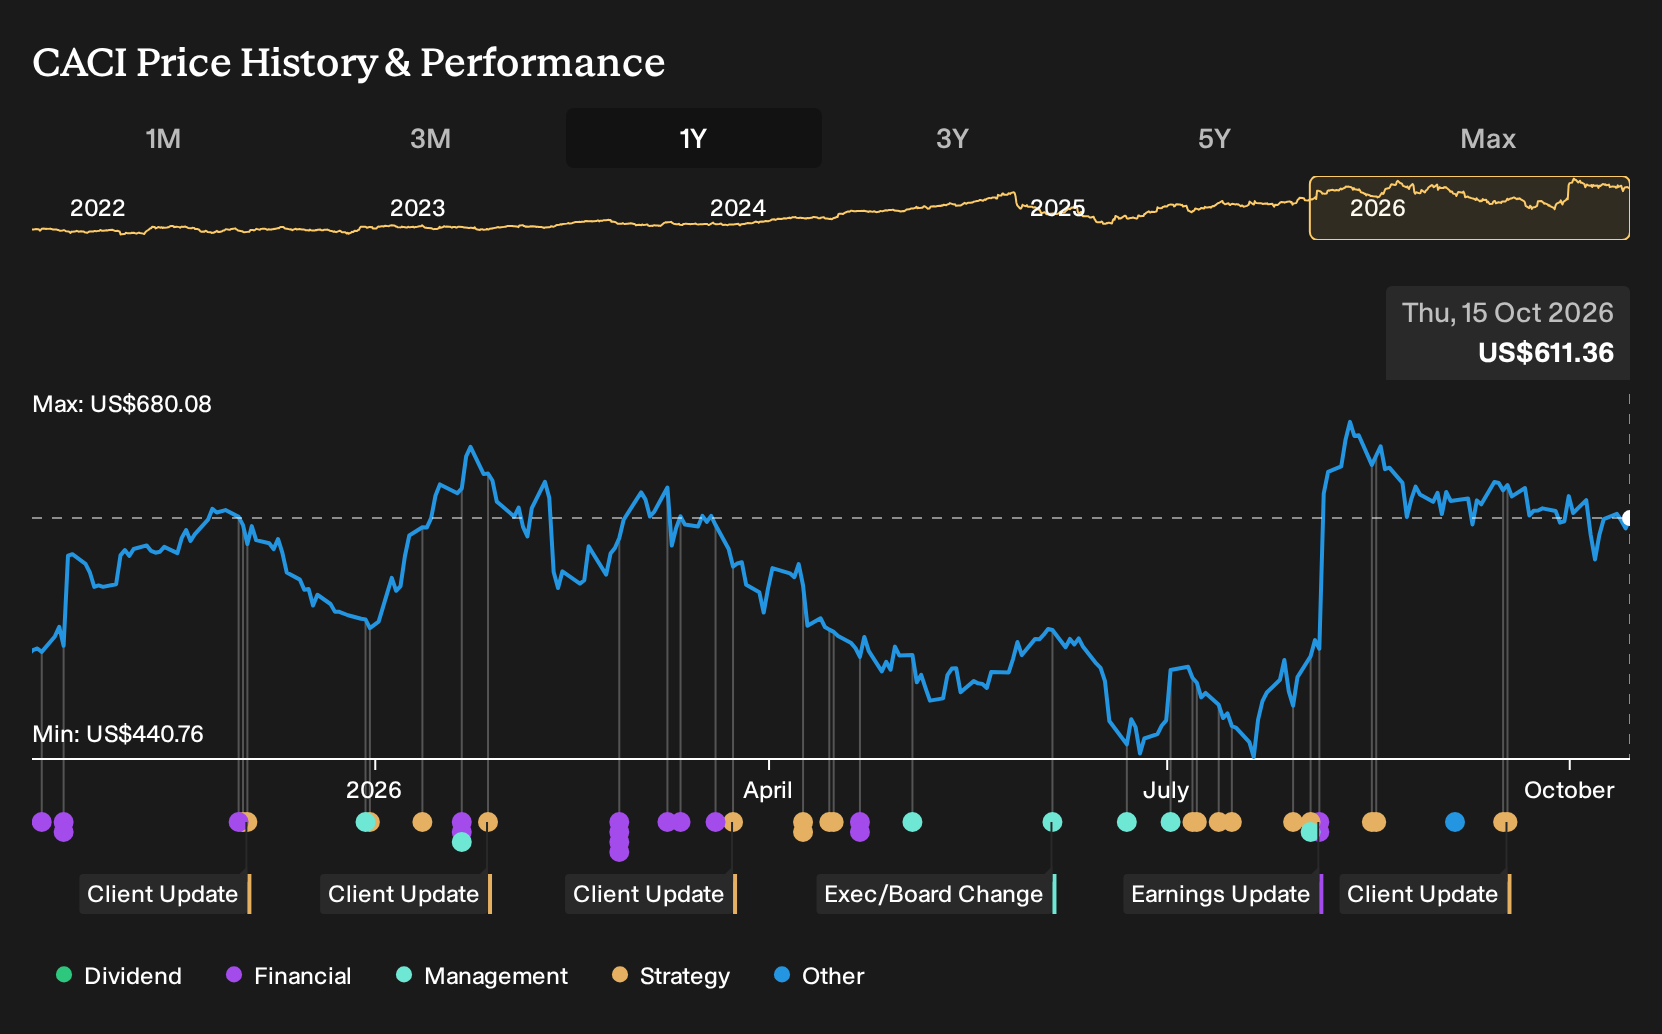
- CACI International recently reported fiscal 2026 results with 11% revenue growth and a US$32b backlog, and closed the ARKA acquisition to add space based sensors and agentic AI to its national security technology portfolio.
- The ARKA deal pushes CACI International further toward higher value defense tech style work, which could reshape its mix of contracts, capital needs, and long term margin profile compared with more traditional services.
- Now the focus turns to how CACI International's investment narrative could shift as the ARKA acquisition and record backlog reshape its technology mix.
CACI International Investment Narrative Recap
Owning CACI International means buying into a long pipeline of government work that leans more toward defense tech, software defined systems, and higher value space programs than traditional staffing contracts. The recent 11% revenue growth and US$32b backlog keep that thesis intact. The short term swing factor is still how efficiently those large, long duration awards convert into margin and cash generation.
The biggest operational risk is execution and cash flow. Management is pushing into more complex programs and higher capital needs, especially with manufacturing and acquisitions, while debt is not well covered by operating cash flow. If integration costs, capex, and pricing do not line up, free cash flow and returns on capital could stay under pressure.
The ARKA acquisition looks most relevant to the current story because it adds space based sensors and agentic AI that align directly with CACI International's defense tech focus. That fits with management's push into electronic warfare, counter UAS, and space programs such as Spectral, Domestic Shield, NITE STAR, and Enterprise Space Terminal that sit in the record backlog.
For you as a shareholder, the question is how smoothly ARKA is absorbed into existing operations. Success would show up in timely program milestones, clean contract performance, and no visible drag on already scrutinized free cash flow margins. Any integration missteps or overruns could reinforce concerns about capital efficiency at the same time the business is leaning further into more complex, fixed price style work.
CACI International's current analyst narrative points to US$12.2b in revenue and US$727.8m in earnings by 2029, based on an assumed 8.3% annual top line growth rate. That compares with earnings today of US$535.8m, which implies an increase of roughly US$192m over the forecast period if those consensus estimates play out.
Uncover why CACI International's fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view around CACI International focuses less on ARKA and more on the older concern that government funding and award processes were patchy, with bookings sometimes trailing revenue. The most optimistic analysts still pencilled in about US$12.7b of 2029 revenue and US$857.6m of earnings, so you can see how opinions may shift sharply once this latest news filters into updated models.
Explore 3 other CACI International fair value estimates, including one that suggests as much as 75% above the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CACI International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CACI International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CACI International's overall financial health at a glance.
Looking For More Ideas Beyond CACI International?
Once you are comfortable with where CACI International fits in your portfolio, it can help to scan a wider opportunity set using focused stock lists that match your priorities on quality, value, or risk.
- If you care most about stronger balance sheets and dependable fundamentals, start with our list of solid balance sheet and fundamentals (25 results) to see which businesses clear that bar.
- For investors hunting for mispriced opportunities, filter the market using the 33 high quality undervalued stocks and see which companies currently screen as potentially better value.
- If capital preservation sits higher on your list than aggressive growth, consider our 32 resilient stocks with low risk scores to find shares that align more closely with a lower risk profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com