


Is Aerospace Expansion Altering The Investment Case For Parker Hannifin (PH)?
- Parker-Hannifin recently highlighted strong momentum in its Aerospace Systems segment, announced an acquisition of CIRCOR International's Commercial and Defense Aerospace business, and issued fiscal 2027 guidance that targets total sales growth of 5.5% to 8.5%.
- The planned addition of CIRCOR’s aerospace assets points to a heavier tilt toward longer-cycle aerospace and defense work. This could reshape how Parker-Hannifin balances industrial cyclicality against more contracted, backlog-driven demand.
- We will examine how Parker-Hannifin's investment narrative is influenced by its aerospace acquisition push, especially the CIRCOR transaction.
Scan how Parker-Hannifin’s aerospace push compares to other industrials tilting into longer-cycle demand and shortlist the 41 power grid technology and infrastructure stocks.
Parker-Hannifin Investment Narrative Recap
To own Parker-Hannifin, you need to believe it can keep turning a high quality motion and control portfolio into solid earnings and cash flow, even as parts of its industrial base slow. The near term story leans heavily on execution in Aerospace Systems and continued discipline in operations rather than a big rebound in underlying demand.
The CIRCOR aerospace acquisition and fiscal 2027 sales guidance put more weight on longer cycle, backlog rich aerospace and defense work as a key catalyst. The biggest near term risk still looks operational. Softer organic growth, high debt levels and a premium P/E leave little room for integration missteps or weaker margins.
The move to acquire CIRCOR International's Commercial and Defense Aerospace business sits at the center of this story. It increases Parker-Hannifin's exposure to aerospace programs that tend to be supported by long contracts and sizeable order books, which ties directly into management's confidence in that 5.5% to 8.5% fiscal 2027 sales growth guidance.
For you as an investor, the question is less about deal headlines and more about execution. Folding CIRCOR's assets into Parker-Hannifin's existing aerospace platform needs to support the Win Strategy goals on margins and cash conversion, while not stretching a balance sheet that already carries meaningful debt or amplifying the risk around a premium valuation.
Parker-Hannifin's analyst narrative points to revenues of US$28.2b and earnings of US$5.2b by 2029, built on assumed revenue growth of 9.4% per year and an earnings increase of roughly US$1.6b from US$3.6b today.
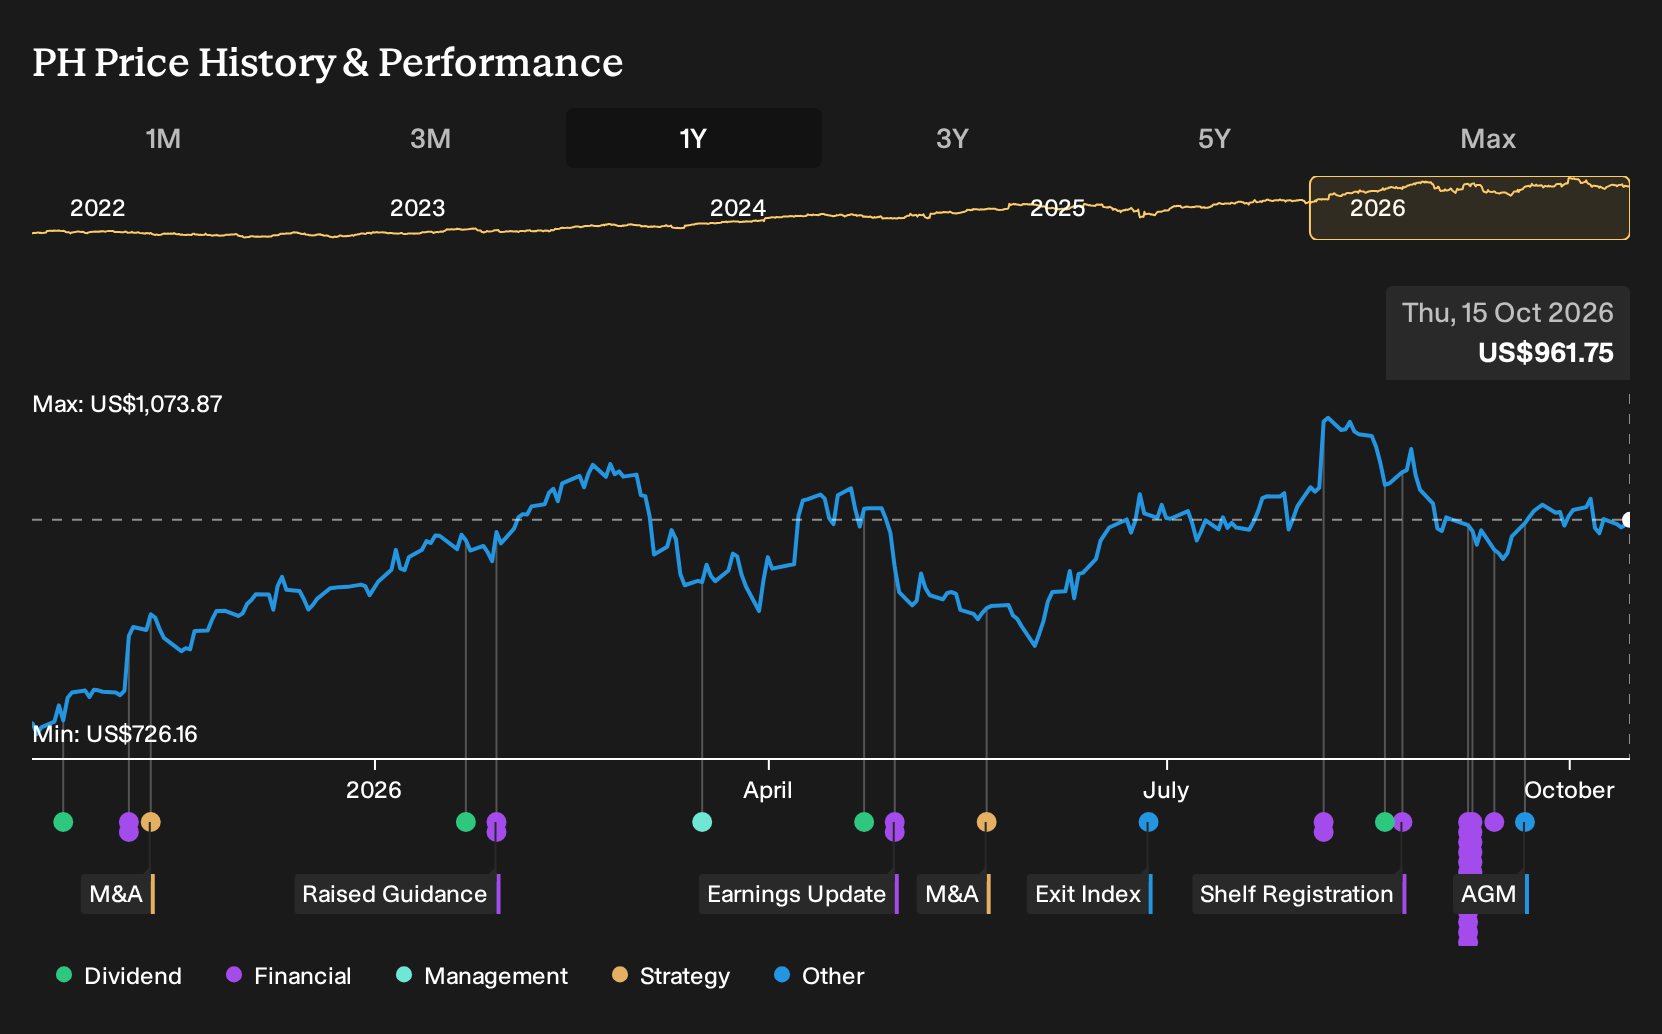
Uncover why Parker-Hannifin's fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative view focuses on valuation risk rather than aerospace upside. The most bearish Parker-Hannifin analysts were assuming about US$26.9b of revenue and US$4.9b of earnings by 2029, alongside a lower 28.0x P/E. That is a far more cautious story than the consensus; treat this acquisition news as a reason to compare several competing narratives, not just one.
Explore 3 other Parker-Hannifin fair value estimates, including one that suggests it could be worth just $950.45.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Parker-Hannifin research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Parker-Hannifin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Parker-Hannifin's overall financial health at a glance.
Looking for more Parker-Hannifin style investment ideas?
If the Parker-Hannifin story has you thinking about where to look next, use this momentum to broaden your watchlist with other stocks that match the kind of quality, balance sheet strength, or value profile you prefer.
- If capital preservation comes first for you, start with a set of companies screened for resilience and lower risk using the 32 resilient stocks with low risk scores.
- If you are hunting for quality at a sensible price, benchmark Parker-Hannifin against a curated 33 high quality undervalued stocks that combine fundamentals and valuation discipline.
- If you want sturdier finances backing your ideas, filter for companies with stronger balance sheets and cleaner fundamentals through the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com